
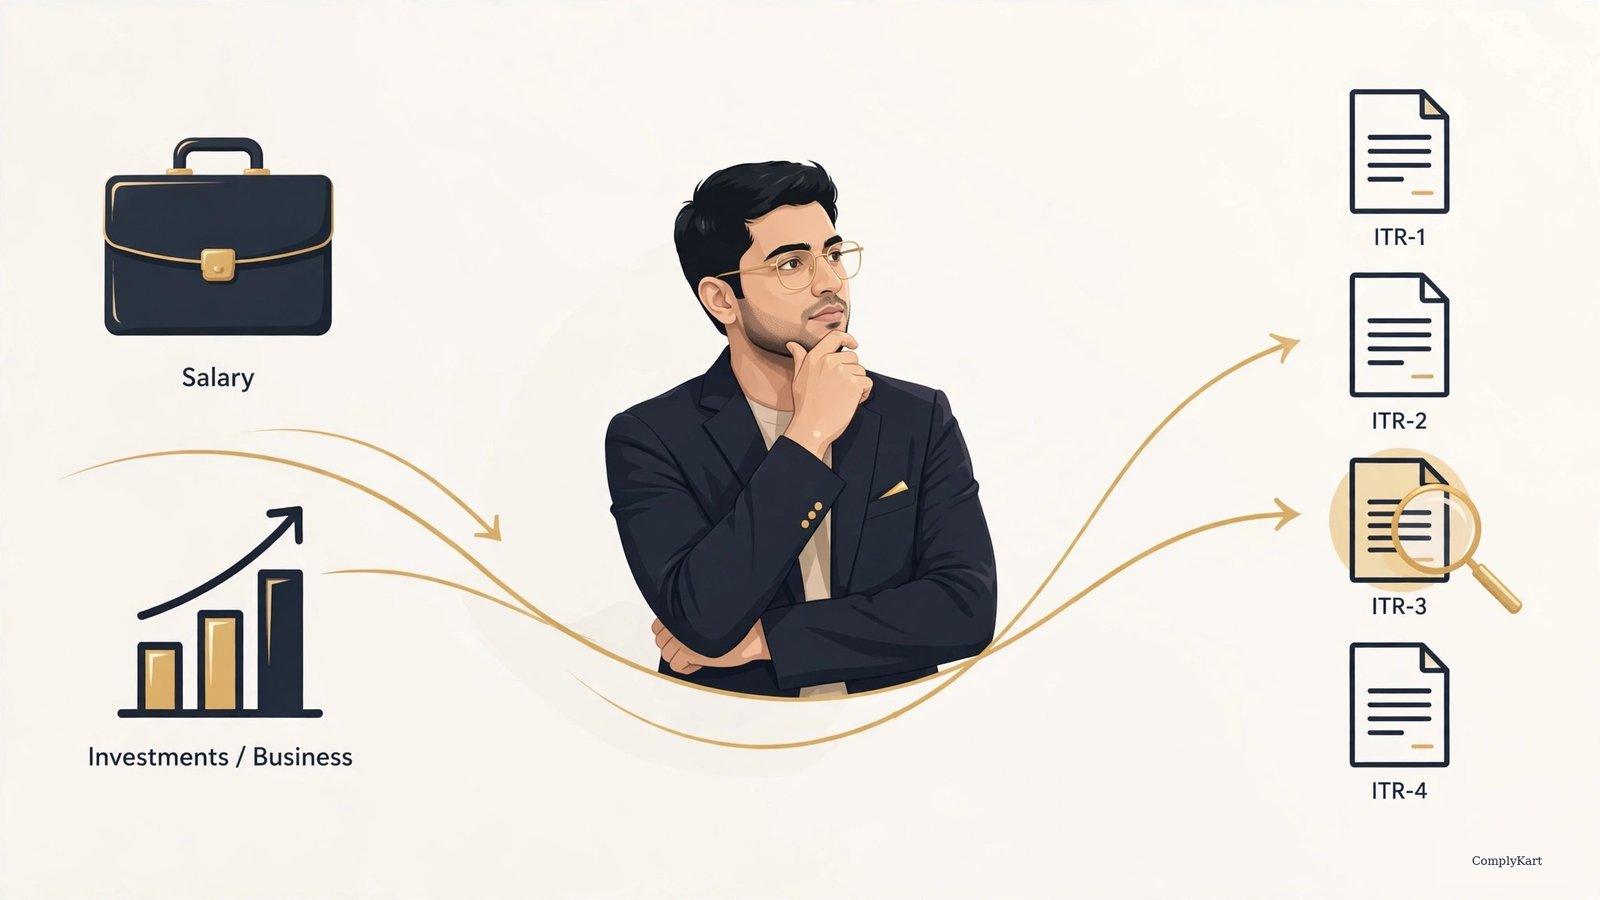
Every July, I watch the same ritual. Someone with a salary and a mutual fund redemption files ITR-1, gets a defective-return notice, and discovers that the "simple" form was never theirs. The form you file is not a preference. It is decided by where your income came from.
CBDT notifies the ITR forms each year, and the logic rarely changes. Here is the map, in plain English.
ITR-1 (Sahaj): the narrowest gate
ITR-1 is for resident individuals — not resident-but-not-ordinarily-resident — with total income up to ₹50 lakh, from salary or pension, one house property, and other sources like interest. Agricultural income must stay under ₹5,000.
You cannot use ITR-1 if you are a director in an unlisted company, hold unlisted equity shares, have capital gains of any kind, own more than one house property, have foreign assets or signing authority abroad, or earn from a business or profession. That "capital gains of any kind" exclusion is the trap. One equity redemption, one property sale, and ITR-1 is closed to you.
ITR-2: salary plus investments, no business
Individuals and HUFs whose income comes from salary, capital gains, multiple house properties, foreign assets, or agricultural income above ₹5,000 — but not from a business or profession — file ITR-2. Salaried people with ESOPs, RSUs, mutual fund redemptions, or crypto sit here.
The rule of thumb: if your money came from investments rather than a business you run, ITR-2 is probably yours.
ITR-3: you run a business or profession
Freelancers, consultants, proprietors, partners — anyone with income from business or profession files ITR-3. This is also the form for people who opted out of presumptive taxation, and for those whose accounts needed audit. If you billed clients this year, start here.
ITR-4 (Sugam): the presumptive shortcut
If you declare income presumptively — Section 44AD for small businesses, 44ADA for specified professionals, 44AE for goods carriages — and your total income is within ₹50 lakh, ITR-4 is your form. It is the shortest route, because you declare a percentage of receipts instead of maintaining full books.
ITR-5, ITR-6, ITR-7: entities
ITR-5 covers firms, LLPs, associations of persons, bodies of individuals, co-operative societies, and local authorities. ITR-6 is for companies. ITR-7 is for trusts, political parties, research associations, and institutions filing under the special clauses of Section 139 — the nonprofit and institutional corner.
Think of them as railway ticket counters
Same station, same destination — paying your tax. But the counters are split by ticket type, and joining the wrong queue means redoing the trip. Filing ITR-1 when you needed ITR-2 does not get "adjusted." You get a notice under Section 139(9) calling the return defective, and you refile. The tax department is not grading your effort; it is matching income types to forms.
Edge cases that confuse everyone
Salary plus freelancing on the side. The moment business or professional income appears, ITR-1 and ITR-2 are both closed. You are in ITR-3 (or ITR-4 if you go presumptive). Many salaried people with a small consulting gig file ITR-1 "because the salary is the main income." The form does not care which income is bigger. It cares which incomes exist.
Partner in an LLP or firm. Your share of firm profit is exempt in your hands, but the existence of business income puts you in ITR-3. Remuneration and interest from the firm are taxable in your hands and reported there too.
NRI with Indian income. Non-residents cannot file ITR-1 or ITR-4 at all. Depending on income sources, they land in ITR-2 or ITR-3. If you moved abroad mid-year, check your residential status before you touch any form.
Three mistakes I see every season
Filing last year's form from memory. The notified forms change in small ways each year — new schedules, new disclosures. Open this year's form, not last year's habit.
Forgetting that income type beats income size. A ₹40 lakh salary with one mutual fund redemption is ITR-2, not ITR-1. A freelancer with ₹6 lakh of billing is ITR-3 or ITR-4, not ITR-1. The source decides.
Skipping verification. Filing is not complete until the return is verified — Aadhaar OTP, net-banking EVC, or a signed ITR-V sent to CPC. An unverified return is a return that was never filed.
One more thing: the regime
The new tax regime is the default since FY 2023-24. It changes how your income is computed, not which form you file. Pick your regime with a calculation, pick your form with the map above, and do both before the deadline instead of after it.
Once you know your form, run your numbers first — our income tax calculator compares both regimes so you file the right form with the right computation. And if you are filing as a business for the first time, read the form's instructions for your assessment year before you start — fifteen minutes with the instructions saves a defective-return notice later.

Comments
No comments yet — ask the first question below.
Join the discussion
Questions go straight to our expert desk. Comments appear after a quick review — no spam, no noise.