
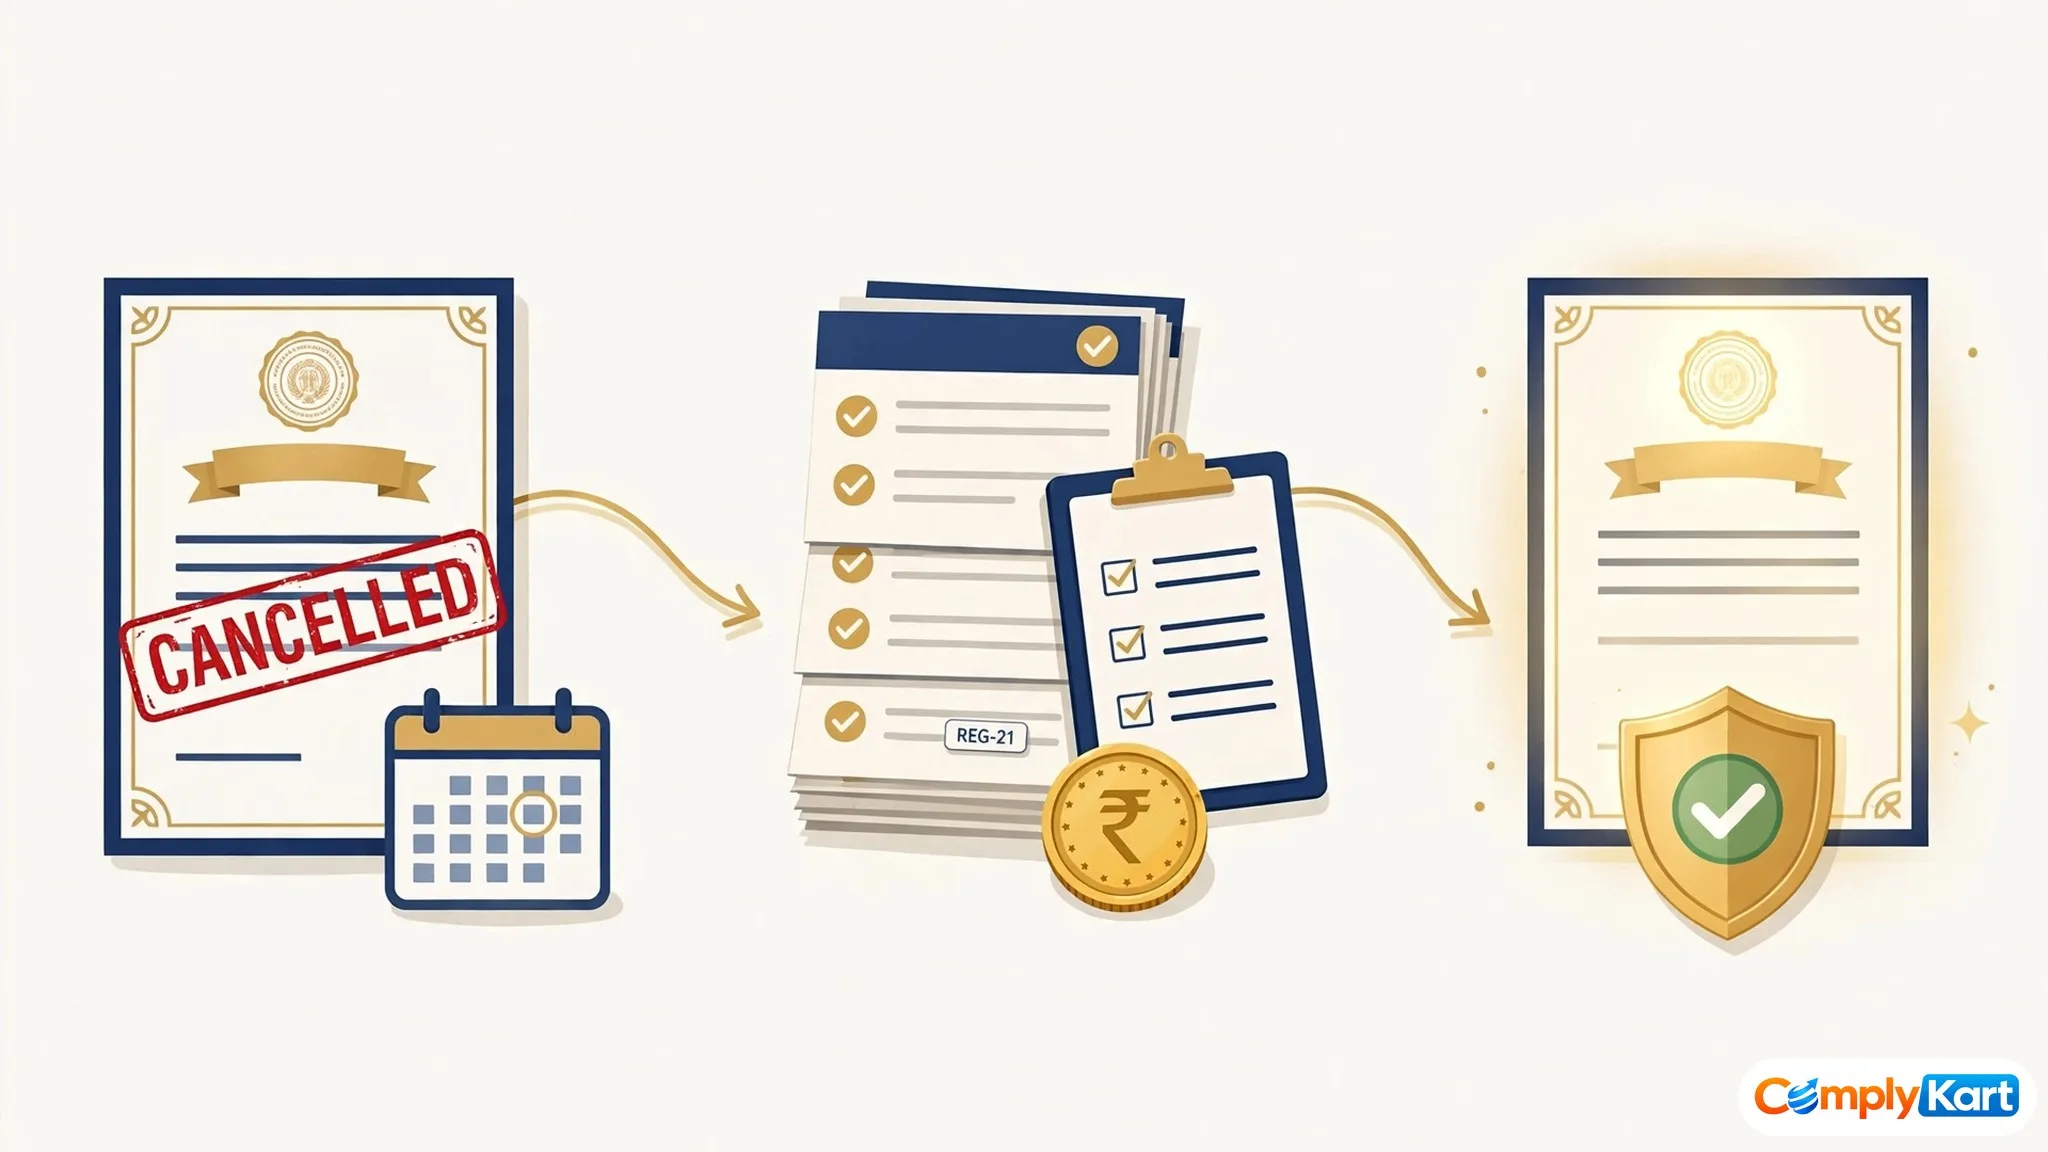
The cancellation order arrives quietly — an email, a status change on the portal — and your GSTIN reads "Cancelled" to every buyer. You cannot raise a tax invoice; customers start asking uncomfortable questions.
Where the officer cancelled it on his own motion — missed returns are the commonest trigger, as our complete guide to GST return filing explains — Section 30 gives you a route back: revocation, in Form GST REG-21. The same GSTIN, the same history. But it runs on a clock — and the clock is where people get hurt.
The short answer: If the officer cancelled your registration on his own motion, apply in Form GST REG-21 within 90 days of service of the order. File every missed return and pay the dues first. The officer decides in Form REG-22 within 30 days; if unconvinced, you get seven working days to answer a REG-23 notice.
Is the revocation time limit 30 days or 90 days?
Ninety. This is the most expensive confusion in this corner of GST. Until 30 September 2023, Rule 23 allowed just 30 days. Notification No. 38/2023–Central Tax (4 August 2023) rewrote the limit: for cancellation orders (Form GST REG-19) served on or after 1 October 2023, the window is 90 days from service. Rule 23's current text on CBIC's website says "ninety days" in so many words.
Yet guides still ranking on Google's first page — IndiaFilings' revocation pages among them — tell you 30 days, with an extension ladder that no longer exists. Count from the date of service, not the date you noticed.
What if the 90 days have already run out?
Rule 23 has a proviso for this. On sufficient cause shown, for reasons recorded in writing, the Commissioner — or an officer he authorises, not below Additional or Joint Commissioner rank — may extend it by up to 180 more days. The outer wall: 270 days from the cancellation order. Inside the rule, there is no fourth door.
"Sufficient cause" must be documented, not asserted: a hospitalisation, a portal failure, records locked with a departed accountant. And it buys only time to apply — the backlog underneath stays.
Why must every pending return be filed before REG-21?
Because the rule forbids it. Where registration was cancelled for failure to furnish returns, Rule 23 bars the application unless those returns are furnished and their tax, interest, penalty and late fee paid. The portal enforces this literally — until the backlog is cleared, REG-21 will not go through.
Think of reviving an insurance policy. The insurer does not start with the revival form — you first pay every missed premium, with interest, and only then does the policy come back to life. Returns first, form last.
The backlog has a price. GSTR-3B late fee runs at ₹50 per day (₹20 for a nil return), capped at ₹500 for nil returns, ₹2,000 up to ₹1.5 crore turnover, ₹5,000 up to ₹5 crore, ₹10,000 above that. Interest runs separately at 18% per annum on tax paid late in cash. The portal computes both.
In real numbers: a trader with ₹80 lakh turnover stops filing; after June and July GSTR-3Bs go missing, the officer cancels the registration — order served 12 September 2026. He wakes up on 20 October, day 38 of his 90. Three returns are outstanding — June (92 days late), July (61 days), August (30 days) — carrying ₹18,000 of tax a month, ₹54,000 in all. Late fee: ₹2,000 + ₹2,000 + ₹1,500 = ₹5,500 (two hit his slab cap). Interest: roughly ₹1,625. Total: about ₹61,125, tax included. He files REG-21 the same day.
How do you file Form GST REG-21, step by step?
1. Log in at gst.gov.in with the cancelled GSTIN's credentials — login still works.
2. Open Services → Registration → Application for Revocation of Cancellation of Registration.
3. Give your reasons; attach return acknowledgements and challans.
4. Submit with DSC or EVC and keep the ARN. There is no government fee for REG-21.
5. Track the status — REG-22 follows within 30 days if the officer is satisfied.
If the backlog looks heavy, get it computed return by return first — that clean-up is what our GST return filing desk handles; our compliance fee calculator estimates the cost before you commit.
What happens if the officer issues Form REG-23?
REG-23 is a show-cause notice: the officer is inclined to reject, and must hear you first. Reply in Form GST REG-24 within seven working days of service, with documents. He then passes the order within 30 days of your reply — REG-22 revoking, or REG-05 rejecting. Treat the seven days as hard; an unanswered REG-23 usually ends the application.
What happens to your ITC and gap-period invoices?
While cancelled, you held no registration at all — no tax invoices, no collecting GST. Once REG-22 revokes the cancellation, Rule 23 gives you 30 days from that order to file returns for the gap period. Those returns make the revival real on the portal.
Your own purchase credit has express protection. Section 16(6), inserted by the Finance (No. 2) Act, 2024, lets you claim ITC on cancelled-period invoices in those gap returns — provided the credit was not already time-barred under Section 16(4) when the cancellation order was passed. Miss the 30-day window and the protection lapses.
Your buyers stand differently — this deserves a phone call, not silence. Section 16(6) protects the cancelled person, not his customers. Their credit follows the normal road: once your GSTR-1 for the gap months is filed, your invoices appear in their GSTR-2B, claimable under the usual rules. Tell them before their accountant finds the gap.
When is revocation not available at all?
Three situations close the door. First, you applied for the cancellation yourself: Section 30 revocation exists only where the officer cancelled on his own motion, a voluntary cancellation under Section 29(1) cannot be revoked — the answer is a fresh GST registration. Second, the 270-day wall has passed. Third, a REG-05 rejection.
For the second and third, the remedy is an appeal under Section 107 against the order, in Form APL-01, within three months of its communication. The Appellate Authority can condone at most one further month; the GST Appellate Tribunal confirmed in 2026 that this ceiling is a jurisdictional hard stop. High Courts have restored registrations by writ in exceptional cases, but a writ is a last resort, not a plan. Move while REG-21 is open.
Frequently asked questions
Can I take a fresh GSTIN instead of revoking?
Sometimes a fresh start is genuinely faster, especially if the business has changed shape. But you give up ITC continuity and filing history — and the old dues follow the same PAN. Our breakdown of what GST registration costs in India lets you compare on numbers, not instinct.
Can a retrospectively cancelled registration be revoked?
Yes, through the same REG-21 route, though expect closer scrutiny. Rule 23 adds a condition: every return from the effective date of cancellation to the revocation order must be filed within 30 days of it. The deeper the backdating, the longer that tail.
Is there any fee for filing Form REG-21?
None — the application is free. Your money goes into the backlog (tax, interest, late fee) and into professional help only if you take it.
The officer rejected my application in REG-05. Is it over?
No. A rejection is itself appealable: appeal under Section 107 in Form APL-01 within three months of communication, with at most one month of condonable delay. What ends is a second REG-21 on the same facts.

Comments
No comments yet — ask the first question below.
Join the discussion
Questions go straight to our expert desk. Comments appear after a quick review — no spam, no noise.