
IN BRIEF
A private company under section 2(68) of the Companies Act, 2013 restricts share transfers in its articles, caps membership at 200 and bars invitations to the public to subscribe for its securities. A public company under section 2(71) is any company that is not a private company, with no member limit, transferable shares and the freedom to invite the public to subscribe, subject to the Act and SEBI rules.
Most founders pick "Private Limited" because everyone else does. Then, two years later, an investor asks a question nobody prepared for — can this company take 300 shareholders, or list, or sell shares to the public? The answer sits in two short definitions in the Companies Act, 2013, and it decides far more than the suffix on your letterhead. I have watched founders discover the difference at the worst possible moment: mid-fundraise, with a term sheet waiting.
Short answer: A private company under section 2(68) restricts share transfers, caps members at 200 and cannot invite the public to subscribe for its securities. A public company under section 2(71) is any company that is not private — no member cap, generally freely transferable shares, and it may offer securities to the public and seek a listing.
The difference in one paragraph
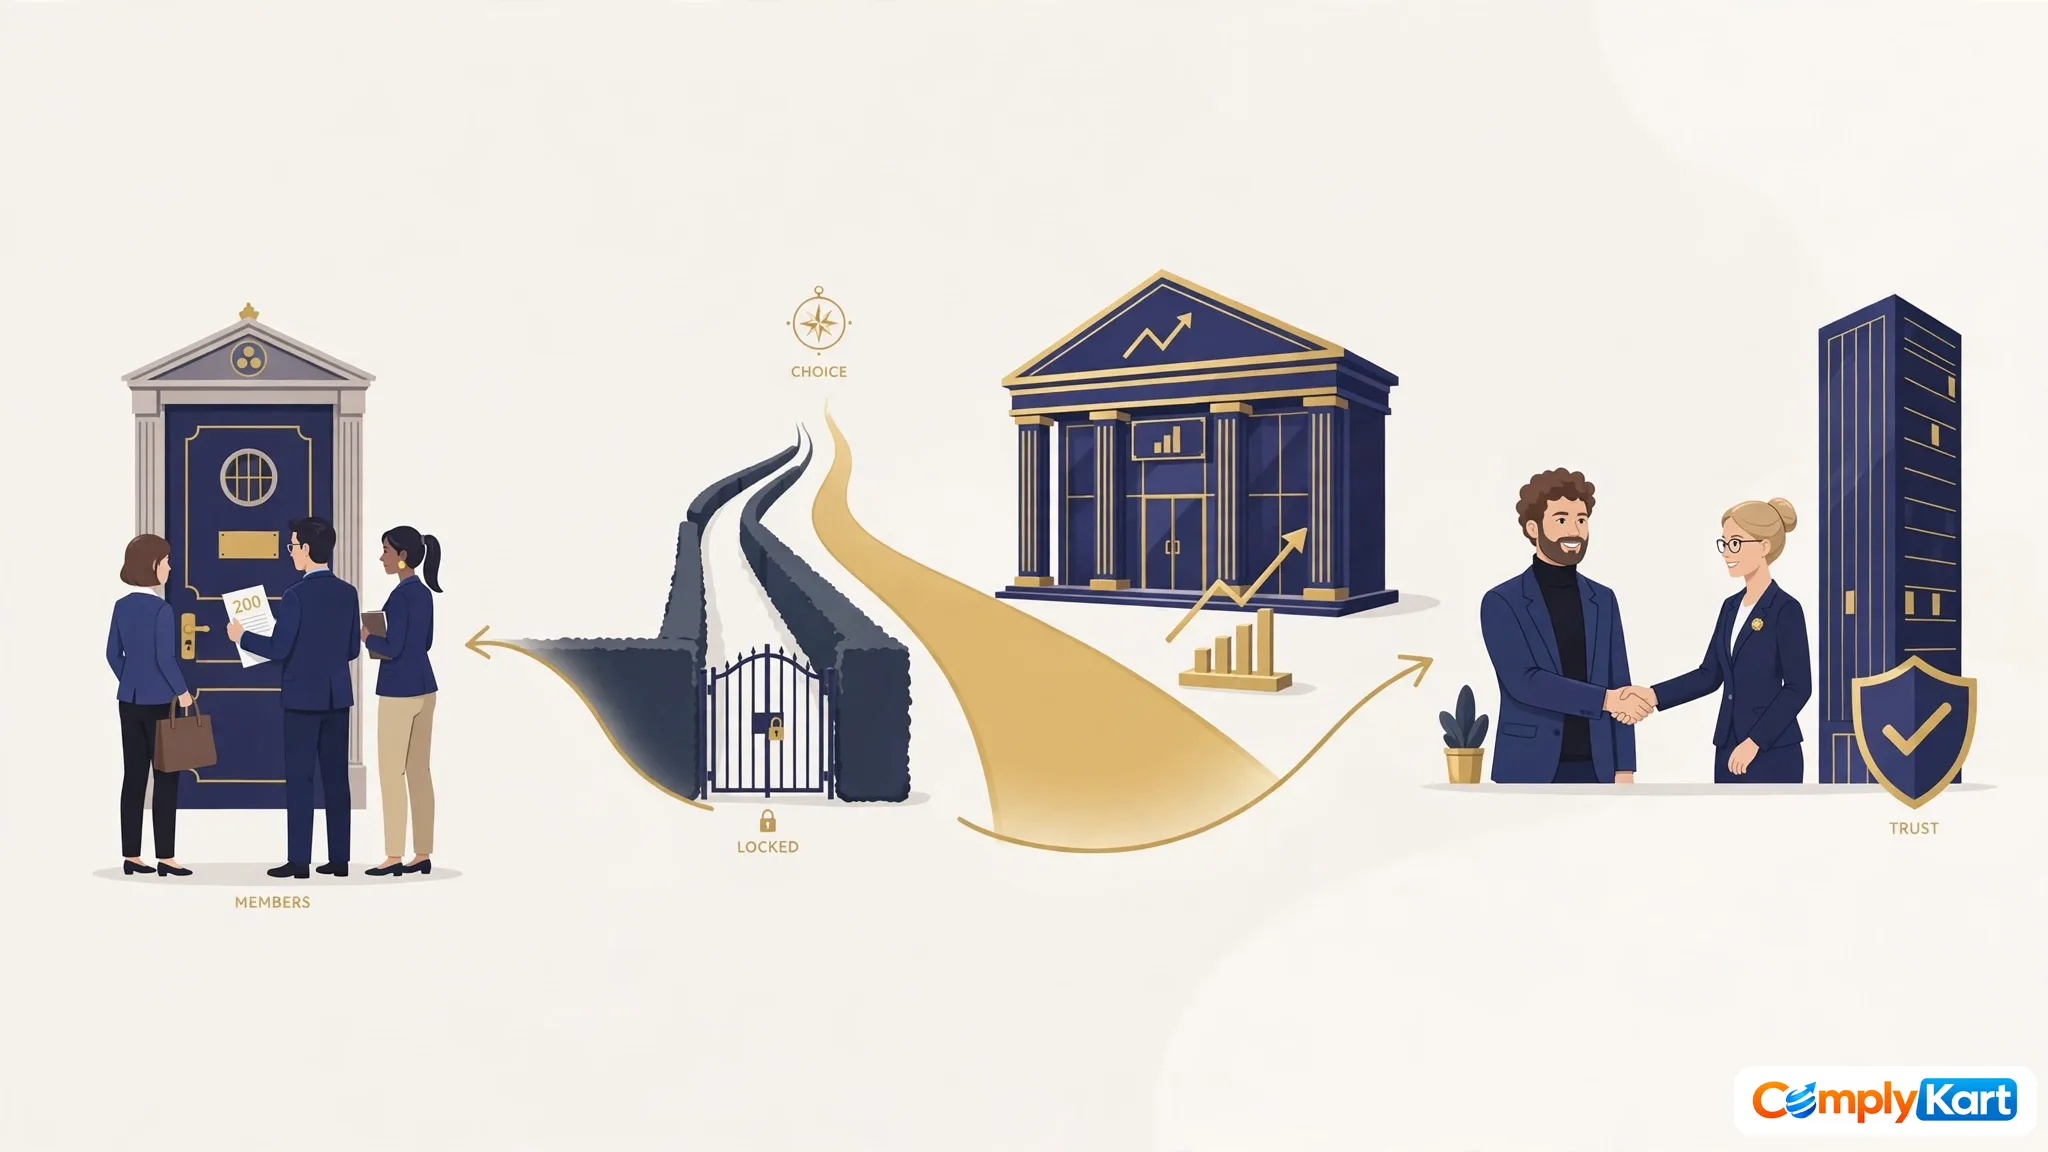
Think of a private company as a members-only club. The door is locked, the membership list is capped at 200, and nobody gets in unless the existing members agree. A public company is a shop on a high street with the shutters up — anyone can walk in and buy. The club is quieter and cheaper to run. The shop can serve far more people, but it pays for the footfall with rules, records and strangers watching.
That is the whole distinction, really. Section 2(68) defines a private company by three restrictions written into its articles of association: it restricts the right to transfer shares, it limits membership to 200, and it prohibits any invitation to the public to subscribe for its securities. Section 2(71) defines a public company the other way round — it is simply a company that is not a private company. No separate list of features. If your company drops even one of the three private restrictions, it stops being private.
One thing the name does not tell you: size. A private company can turn over ₹100 crore with three shareholders. An unlisted public company can turn over ₹2 crore with eight. "Private" describes ownership and fundraising, not how big the business is.
Private vs public company at a glance
| Point | Private limited company | Public limited company |
|---|---|---|
| Governing section | Section 2(68), Companies Act, 2013 | Section 2(71), Companies Act, 2013 |
| Name suffix | "Private Limited" (Pvt. Ltd.) | "Limited" (Ltd.) |
| Minimum members | 2 (1 for a One Person Company) | 7 |
| Maximum members | 200, with statutory exclusions | No limit |
| Minimum directors | 2 (1 for an OPC) | 3 |
| Maximum directors | 15, unless a special resolution allows more | 15, unless a special resolution allows more |
| Share transfer | Restricted by the articles of association | Generally freely transferable under section 58 |
| Inviting the public to subscribe | Prohibited | Permitted, subject to the Act and SEBI rules |
| Stock-exchange listing | Cannot list equity shares | Can list, after meeting listing conditions |
| Minimum paid-up capital | None — the 2015 amendment removed the old ₹1 lakh floor | None — the 2015 amendment removed the old ₹5 lakh floor |
| AGM quorum (section 103) | 2 members personally present | 5, 15 or 30 members, by total membership |
| Board meetings (section 173) | Minimum 4 a year; small companies need 2 | Minimum 4 a year, gap under 120 days |
| Annual return | MGT-7, or MGT-7A for an eligible small company or OPC | MGT-7 |
| Small-company status (section 2(85)) | Possible, if capital is up to ₹10 crore and turnover up to ₹100 crore | Excluded — a public company can never be a small company |
What "private" actually restricts
The three restrictions in section 2(68) are not slogans. Each one bites in a specific way.
First, the share-transfer restriction. Your articles must limit how shares change hands. In practice that usually means a right of first refusal — a selling shareholder offers the shares to existing members first — or a board-approval clause. The restriction does not ban sales. It controls who the buyer can be. Two private companies can have very different transfer clauses, so an investor should read the actual articles before signing anything.
Second, the 200-member cap. Joint holders of shares count as one member. Current and former employees who became members during their employment and kept their shares are excluded from the count. So a company with 190 outside shareholders and 40 ex-employee shareholders is still inside the cap. The count is tested on members, not on shares — one person holding 90% of the shares is still one member.
Third, the ban on public invitations. A private company cannot advertise shares or debentures to the general public, run a public issue, or list. It can still raise money — rights issues, private placements, venture capital, bank debt — all of that stays open. What it cannot do is make a general offer to strangers.
The trap: a private company that is already public
Here is the rule founders miss. A private company that becomes a subsidiary of a public company is treated as a public company for the purposes of the Act, even if its articles still say "Private Limited" and nothing else changes. That is the deeming rule inside section 2(71).
Picture it. A family-owned Pvt Ltd sells 60% of its shares to a listed company. The name on the door does not change. The certificate of incorporation does not change. But the company's legal character does — overnight, the heavier public-company rules start applying. Board restrictions under section 180, remuneration limits under section 197, the committee and audit thresholds in the next section: all of them switch on.
If your group structure includes a listed parent anywhere above you, check this before you assume you are private. What a CIN tells you is a useful starting point — the letters in a CIN record the company class — but the group structure is what decides it.
Can you sell your shares?
In a private company, selling is a process, not a transaction. You check the articles, you offer the shares to existing members if a right of first refusal applies, you get board approval where the articles ask for it, and only then does the transfer go through. A buyer who skips those steps can find the transfer refused. That friction is the point — it is what keeps ownership inside a known circle.
In a public company, section 58 makes securities freely transferable. A shareholder can sell to anyone, and the company cannot refuse on a whim. That is the freedom founders quote when they talk about going public. But freedom is not the same as liquidity. An unlisted public company's shares are legally transferable and still hard to sell, because there is no market quoting a price and no ready buyer. Listing is what creates the market. A public company without a listing has transferable shares that may sit unsold for years.
So the honest comparison is not "restricted vs free". It is "controlled and slow vs free but possibly illiquid". An investor buying into an unlisted public company should ask the same question as one buying into a private company: who will buy these shares from me, and at what price?
How each one raises money
| Funding route | Private company | Public company |
|---|---|---|
| Rights issue (section 62) | Yes — offer to existing shareholders first | Yes |
| Private placement (section 42) | Yes — the standard VC/angel route | Yes |
| Public issue / IPO (sections 23, 26) | No | Yes, with a prospectus and SEBI compliance |
| Listing on NSE/BSE | No | Yes, after meeting listing conditions |
| Deposits from members (section 73) | Yes, within 100% of paid-up capital, free reserves and securities premium, with conditions | Yes, on the full statutory conditions |
| Deposits from the public (section 76) | No | Only for an eligible public company — net worth of ₹100 crore or turnover of ₹500 crore, plus a credit rating and approvals |
| Bank debt and debentures | Yes | Yes |
Most startups never need the public routes. Angel money, venture capital and private placements all work inside a private company, and they work without a prospectus or a listing. The public routes matter when the funding need outgrows what a small group of investors can write — or when the founders want an exit through the market rather than a trade sale.
One more distinction worth knowing: a public company is not automatically a listed company. Listing is a separate step under SEBI rules and stock-exchange requirements. Most public companies in India stay unlisted. They get the wider shareholder base and the transfer freedom, but not the trading, the market price or the continuous disclosures of a listed company.
Where the compliance gap actually bites
Both forms file annual returns, hold AGMs, keep books and get audited. The gap is not in the basics. It is in the governance that switches on at certain sizes — and almost all of it switches on for public companies first.
| Requirement | When it applies | Private company | Public company |
|---|---|---|---|
| Independent directors (section 149(4), Rule 4) | Paid-up capital ₹10 crore+, or turnover ₹100 crore+, or loans/debentures/deposits above ₹50 crore | Not required | At least 2 (listed companies: at least one-third of the board) |
| Audit committee (section 177) | Same thresholds as above | Not required | Minimum 3 directors, independent directors in the majority |
| Nomination and remuneration committee (section 178) | Same thresholds as above | Not required | Minimum 3 non-executive directors, at least half independent |
| Woman director (section 149(1), Rule 3) | Listed companies; public companies with paid-up capital ₹100 crore+ or turnover ₹300 crore+ | Not required | At least 1 |
| Whole-time KMP (section 203, Rule 8) | Listed companies; public companies with paid-up capital ₹10 crore+ | Not required as a set — but see the next row | Managing director/CEO, company secretary and CFO |
| Whole-time company secretary (section 203, Rule 8A) | Paid-up capital ₹10 crore+ | Required — this one catches private companies too | Required, as part of the KMP set |
| Secretarial audit, Form MR-3 (section 204, Rule 9) | Listed companies; public companies with paid-up capital ₹50 crore+ or turnover ₹250 crore+; any company with bank/public-financial-institution borrowings of ₹100 crore+ | Only via the ₹100 crore borrowings limb | Required once a threshold is crossed |
| Internal audit (section 138) | Private: turnover ₹200 crore+ or borrowings ₹100 crore+; unlisted public: capital ₹50 crore+, turnover ₹200 crore+ or borrowings ₹100 crore+ | Required once a threshold is crossed | Required once a threshold is crossed |
Two points in that table surprise people. First, the company-secretary rule catches private companies: any private company with paid-up capital of ₹10 crore or more must appoint a whole-time company secretary. Second, the secretarial-audit rule catches private companies through the borrowings limb — a private company with ₹100 crore or more in bank borrowings needs an MR-3 audit even though the ₹50 crore/₹250 crore limbs are public-only. If you want the full applicability picture, read who needs a secretarial audit.
There is also a newer rule that changed the private-company picture quietly. Since 27 October 2023, Rule 9B requires every private company that is not a small company to issue its securities only in dematerialised form and to get its existing securities dematerialised. The first cohort's deadline was 30 September 2024, extended to 30 June 2025. After the compliance date, a covered company files Form PAS-6 every half year — within 60 days of 30 September and 31 March. And since 1 December 2025, a small company means paid-up capital up to ₹10 crore and turnover up to ₹100 crore, so the Rule 9B net is drawn by those new limits. Read the new small-company limits before deciding whether your company is inside it.
Then there are the rules that apply to public companies only. Section 180 restricts what the board can do without shareholder approval — borrow beyond paid-up capital plus free reserves, sell or lease a substantial undertaking, and a few other big decisions. Section 197 caps managerial remuneration. Private companies are exempt from both. A private company can also use the conditional exemption from the section 185 ban on loans to directors, provided it meets the conditions. None of this makes a public company unworkable. It makes it slower, more documented and more expensive to run — which is the trade for access to public money.
Meetings, filings and the name on the door
The yearly rhythm looks similar from the outside. Every company except a One Person Company holds an AGM under section 96, within six months of the financial year-end. Every company files its financial statements in AOC-4 and its annual return — MGT-7 for a public company, MGT-7 or MGT-7A for a private one. Every company with share capital files the INC-20A commencement filing within 180 days of incorporation.
The differences sit in the room, not the calendar. A private company's AGM needs 2 members personally present for quorum. A public company's quorum scales with its membership: 5 members up to 1,000, 15 between 1,001 and 5,000, and 30 above 5,000. Board meetings follow section 173 — at least four a year with no gap above 120 days, though a small company, a dormant company or an OPC needs only two, one in each half of the year. A quick check on what your year actually costs is the compliance fee calculator.
One correction worth making, because a competitor page still gets it wrong: there is no statutory meeting under the Companies Act, 2013. Statutory meetings belonged to section 165 of the old 1956 Act. The 2013 Act runs on AGMs, EGMs and board meetings. If a guide tells you a public company must hold a statutory meeting, it is quoting a repealed law.
And the name: a private company ends with "Private Limited", a public company with "Limited". The suffix is not branding. It tells anyone dealing with you which set of rules you live under — which is why getting it wrong in a contract or an invoice creates real confusion.
Which one should you choose?
Start from the funding plan, not the form. Four situations cover most founders I meet.
Stay private if your owners are a known group — founders, family, a handful of investors — and your funding will come from private placements, rights issues or debt. This is most startups, most family businesses and most professional firms. You keep control of who owns the company, and your compliance bill stays at the baseline.
Go public (unlisted) if you need a wide shareholder base — an employee-ownership plan with hundreds of holders, a large supplier or customer group taking shares, or a pre-IPO structure — but you are not listing yet. You accept the governance thresholds and the transfer freedom, without the SEBI listing load.
Go public with a listing in view only when there is a genuine plan to offer securities to the public. A listing is a project, not a status. It needs a prospectus, a merchant banker, continuous disclosures and a board that can live with market scrutiny. Converting first and listing "someday" buys you the compliance without the capital.
Reconsider entirely if you are choosing between private and public when your real question is about size. "Private" does not mean small, and "public" does not mean large. A ₹100 crore-turnover company can stay private. Check the small-company limits separately — that classification, not the private/public choice, is what trims your compliance bill.
Converting, in both directions
Private to public is the easier direction. The company raises its members to at least seven and its directors to at least three, passes a special resolution under section 14 to alter its articles and its name clause, and files MGT-14 and INC-27 with the Registrar. No government approval is needed for this direction. The articles lose the three private restrictions, "Private" drops from the name, and the company is public from the Registrar's approval.
Public to private is harder, deliberately. The company passes the special resolution under section 14, then needs approval from the Regional Director. The application in Form RD-1 must reach the Regional Director within 60 days of the special resolution — miss that window and the resolution lapses for this purpose. There is a newspaper advertisement, notice to creditors and regulators, and a chance for objections before the order comes. Only after the Regional Director's approval does the company file INC-27 and take "Private" back into its name. Listed companies need a separate delisting assessment on top of all this; an RD application is not a substitute for one.
Either way, conversion is not a paperwork afternoon. It changes who can own the company, how shares move, and which governance thresholds apply from the conversion date. Get the articles, the shareholder agreements and the lender consents checked before the resolution, not after.
5 mistakes founders make here
- Assuming "private" means small. It does not. A private company can be larger than most public ones. Size is governed by the small-company limits, not by this choice.
- Assuming "public" means listed. It does not. Most public companies never list. An unlisted public company has transferable shares and no market for them.
- Missing the deemed-public trap. A Pvt Ltd that becomes a subsidiary of a public company is public for the purposes of the Act, whatever its name says.
- Counting members wrong. Joint holders count as one; employee-members are excluded. Companies have tripped the 200 cap — or thought they had — on a miscount.
- Forgetting the demat rule. A private company that is not small must hold its securities in dematerialised form and file PAS-6 every half year. Physical share certificates are no longer a filing system.
FAQs
What is the main difference between a private and a public company?
A private company restricts share transfers, caps its members at 200 and cannot invite the public to subscribe for its securities. A public company has no member cap, generally freely transferable shares, and may offer securities to the public and seek a listing.
Can a private limited company become a public limited company?
Yes. Pass a special resolution under section 14 to alter the articles and the name clause, bring members to at least seven and directors to at least three, then file MGT-14 and INC-27 with the Registrar. No Regional Director approval is needed for this direction.
Can a private company sell shares to the general public?
No. A private company cannot invite the public to subscribe for its securities. It can raise money through rights issues, private placements and debt, but a public offer needs a public company — and a prospectus.
Is every public company listed on a stock exchange?
No. Listing is a separate step under SEBI rules. Most public companies stay unlisted; their shares are transferable under section 58 but can be hard to sell without a market.
Does a public company have more compliance than a private company?
Yes, once it crosses the thresholds — independent directors, audit and remuneration committees, whole-time KMP and secretarial audit all switch on for public companies at set sizes. But a private company is not exempt from the basics: a whole-time company secretary at ₹10 crore capital and a secretarial audit at ₹100 crore of bank borrowings catch private companies too.
The choice is rarely permanent, and it is rarely about prestige. Pick the form that fits how you will raise money and who you will let own the company — and if the answer changes, convert deliberately, with the articles and the thresholds checked first. If you are still deciding, start with registering a private limited company for a closely held venture, read the public limited company registration route if you need a wider base, or talk through converting a private company into a public one before the fundraise forces the timetable. A secretarial audit is the right check once your company crosses any of the thresholds in this guide.


Comments
No comments yet — ask the first question below.
Join the discussion
Questions go straight to our expert desk. Comments appear after a quick review — no spam, no noise.