
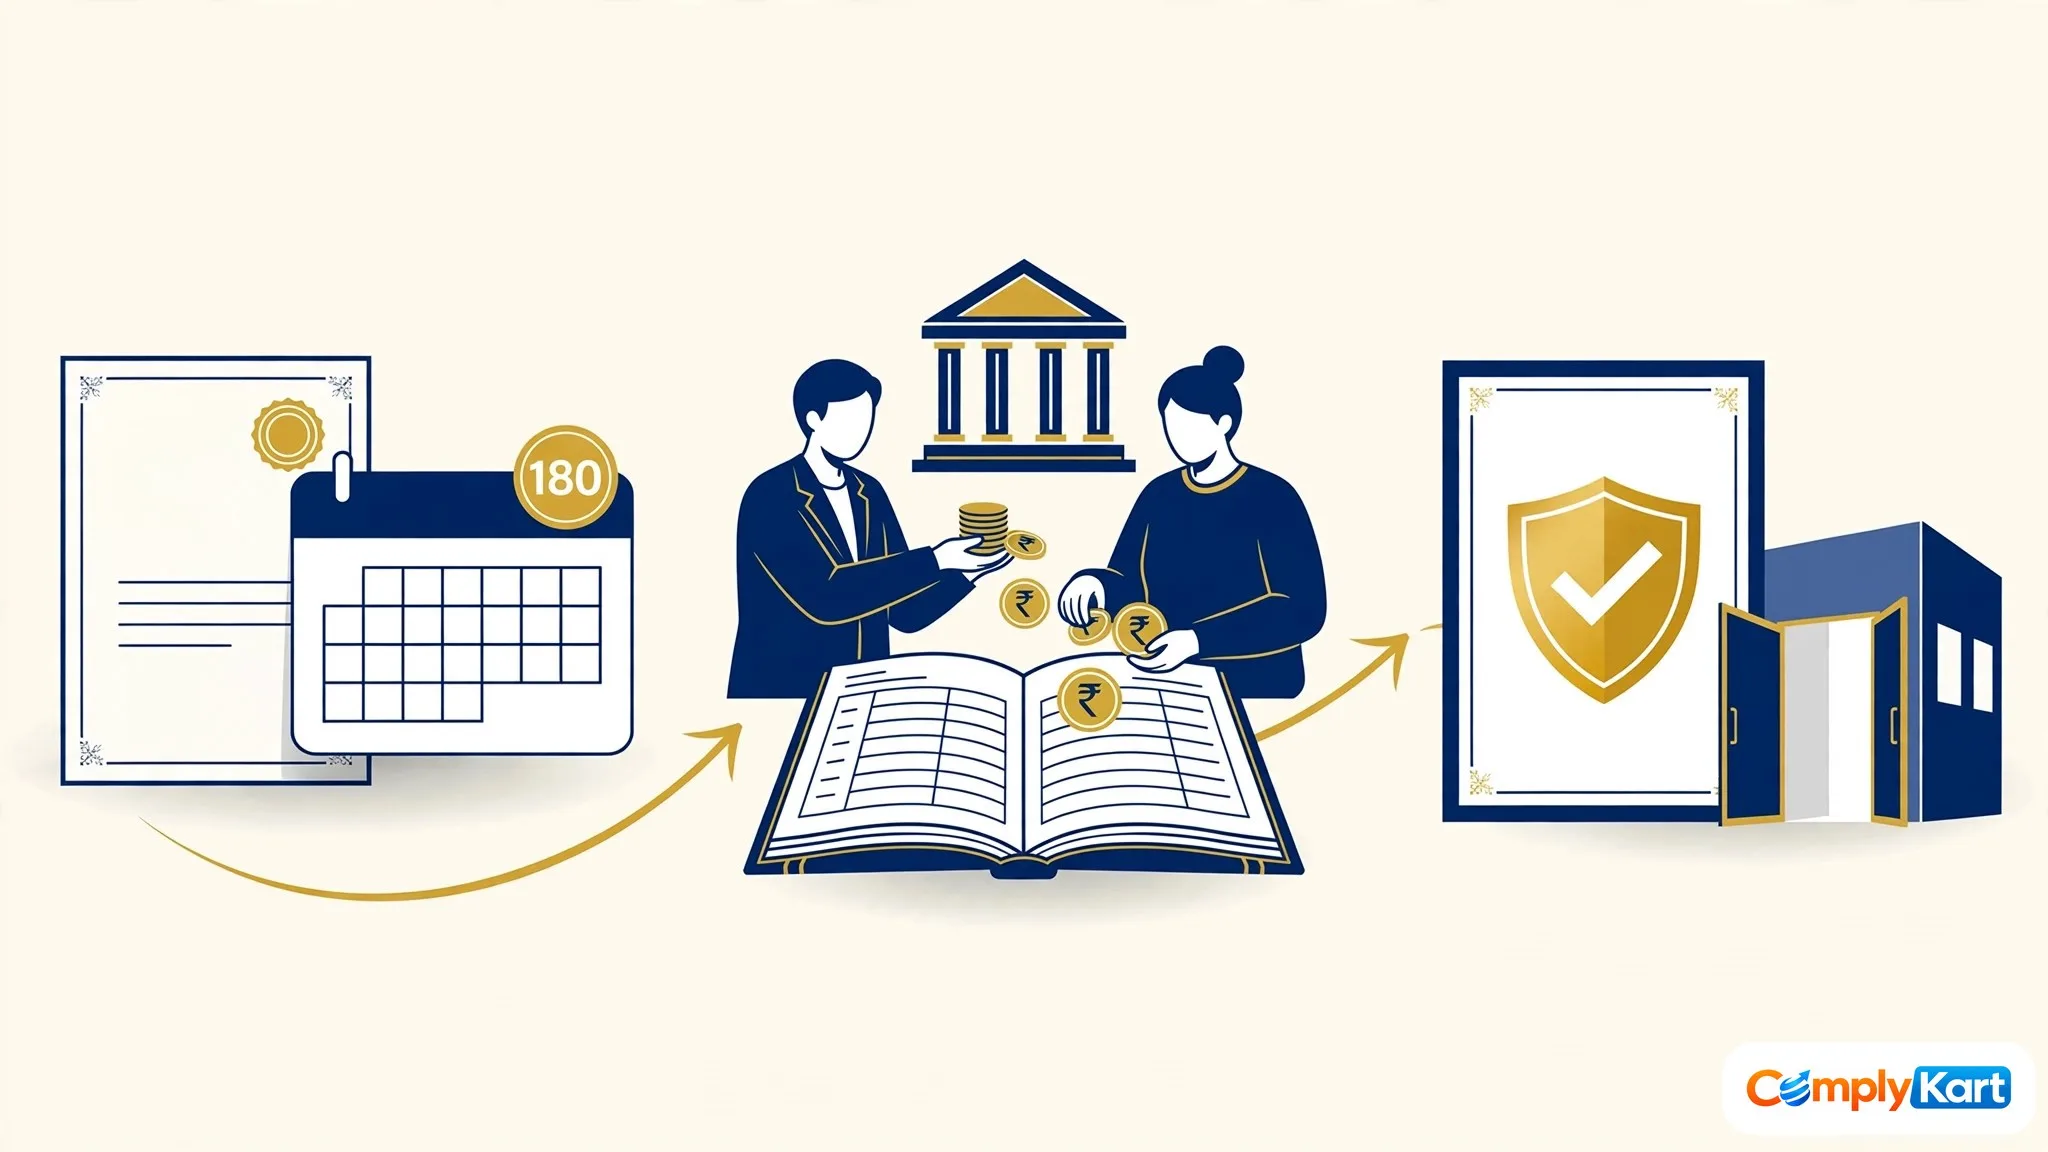
You incorporated, got the certificate, and got busy building the business. Buried in that first six months is a filing most first-time founders have never heard of: INC-20A. Miss it, and the law treats your company as one that never legally started.
The short answer: Every company with share capital incorporated on or after 2 November 2018 must file Form INC-20A within 180 days, declaring that every subscriber has paid for their shares (Section 10A, Companies Act 2013). Until filed, the company cannot commence business or borrow. Default: ₹50,000 on the company, plus ₹1,000 a day per officer in default, capped at ₹1,00,000 each.
What does INC-20A actually declare?
One thing, and it is simple: the owners have put their money in. At incorporation, your subscribers promised to take a certain number of shares. INC-20A is a director's declaration to the Registrar of Companies that each has actually paid for those shares. The proof travels with it: the bank statement showing each subscriber's payment.
Think of a current account that exists on paper but has never received its first deposit — the bank has your file, but nothing can move until money lands. Incorporation is the same: the certificate gives your company a name and a CIN; INC-20A tells the ROC the promised capital is actually in.
Two practical points. First, a director signs the declaration, but a chartered accountant, company secretary or cost accountant in practice must certify the form — that signature is not optional. Second, Section 10A has a second limb: registered office verification (Form INC-22). A pending INC-22 holds the whole thing up.
Who must file INC-20A — and who is exempt?
It applies if your company was incorporated on or after 2 November 2018 and has a share capital. That covers private limited companies and, yes, One Person Companies — an OPC has share capital, so the clock runs for it too. Not trading yet is no excuse.
Two categories sit outside it: companies incorporated before 2 November 2018, and companies with no share capital at all, like a guarantee company without share capital. Everyone else with shares to their name files. Still at the registration stage? Put this deadline on your calendar — it is part of the real cost of registering a private limited company, though nobody quotes it in the package.
What does INC-20A cost if you file on time?
Very little. The government fee follows your authorised capital: ₹200 if it is under ₹1,00,000; ₹300 between ₹1,00,000 and ₹5,00,000; ₹400 up to ₹25,00,000; ₹500 up to ₹1 crore; and ₹600 above that. Most startups pay ₹300 — check your slab on our compliance fee calculator.
What happens if you do not file INC-20A?
Three consequences, and only one of them is money.
First, the legal bar itself: until the declaration is filed, the company shall not commence business or exercise any borrowing powers. Invoices raised, contracts signed, a loan taken — all sit on a company that had not legally switched itself on. Any bank or investor running an MCA check finds it in minutes.
Second, the penalty under Section 10A(2): ₹50,000 on the company, and ₹1,000 for every day the default continues on every officer in default, up to ₹1,00,000 each. In published ROC Pune orders, one company that started business without filing paid ₹50,000 with ₹1,00,000 on each of its two directors; in another, three officers paid ₹1,00,000 each despite having eventually filed.
Third, the existential one. If it is still not filed at day 180 and the Registrar has reasonable cause to believe the company is not carrying on business, Section 10A(3) lets the ROC begin strike-off under Section 248. A strike-off notice in year one is hard to explain to anyone.
Already past day 180? You can still file — here is what it costs
The door does not close: INC-20A stays fileable on the MCA portal, with an additional fee charged as a multiple of the normal fee — 2 times up to 30 days late, 4 times to 60, 6 times to 90, 10 times to 180, 12 times beyond. On a ₹300 fee, 40 days late means ₹1,200 in additional fee — ₹1,500 all in. Trivial money.
But read this carefully: the additional fee buys you the filing, not immunity. It is separate from the Section 10A penalty, and the ROC can still adjudicate the penalty for the period of default — the Pune order above is proof, because that company had filed and paid before the penalty landed. File the moment you discover the gap: two directors, 40 days late, means ₹50,000 plus up to ₹40,000 per director if the ROC adjudicates. Every extra day adds ₹1,000 per officer until the cap. Delay is the expensive option.
On day 120? Do these five things this week
Say you incorporated on 24 June 2026. Today you are around day 120, and your day 180 falls on 21 December 2026. Use this week properly:
- Count your exact deadline. Incorporation date plus 180 days — not six calendar months. Our post-incorporation checklist covers the rest of this window.
- Check the money, subscriber by subscriber. Every subscriber must have paid in full, into the company's bank account, from their own account. One short payment means the declaration cannot truthfully be signed yet.
- Get a clean bank statement. It must show each subscriber's credit clearly. Cash deposits are the classic problem — they do not prove who paid.
- Confirm INC-22 is done. If it is still pending, file it first; INC-20A will ask.
- Get the form certified and filed — with buffer. Aim for day 150, not day 179. Portal glitches do not move deadlines.
Already past day 180? Do the same five steps now — both the additional fee and the per-day penalty stop growing the day you file.
Once commencement is sorted, the annual dates follow — see our MGT-7 due date guide and the ROC annual filing calendar. Our breakdown of private limited registration costs is the companion read — INC-20A is the step that cost sheet usually forgets.Frequently asked questions
Does an OPC need to file INC-20A?
Yes. A One Person Company has share capital, so Section 10A applies — same 180 days, same penalties. The single-member structure changes a lot about an OPC; this is not one of those things.
A subscriber paid in cash. Can we still file?
Not safely. The bank statement is the proof of payment, and a cash deposit shows money arriving without showing who paid it — an open invitation to an ROC query. Route each payment through the subscriber's own account so the credit names them.
Do we get a commencement certificate after filing?
No — no separate certificate is issued. The form is processed straight-through and taken on record electronically; your filed INC-20A and its SRN are the proof. Keep both.
One subscriber has paid only part of their shares. What now?
Collect the balance first. The declaration covers every subscriber and the full value of the shares each agreed to take. Signing while a payment is short makes the declaration untrue — far worse than filing a few days later with an additional fee.
We filed INC-20A but never actually started business. Are we safe from strike-off?
Filing closes the Section 10A risk. It does not protect a company that stays dormant for years — the ROC can still act against non-operating companies under the general strike-off provisions, and annual filings continue.

Comments
No comments yet — ask the first question below.
Join the discussion
Questions go straight to our expert desk. Comments appear after a quick review — no spam, no noise.