
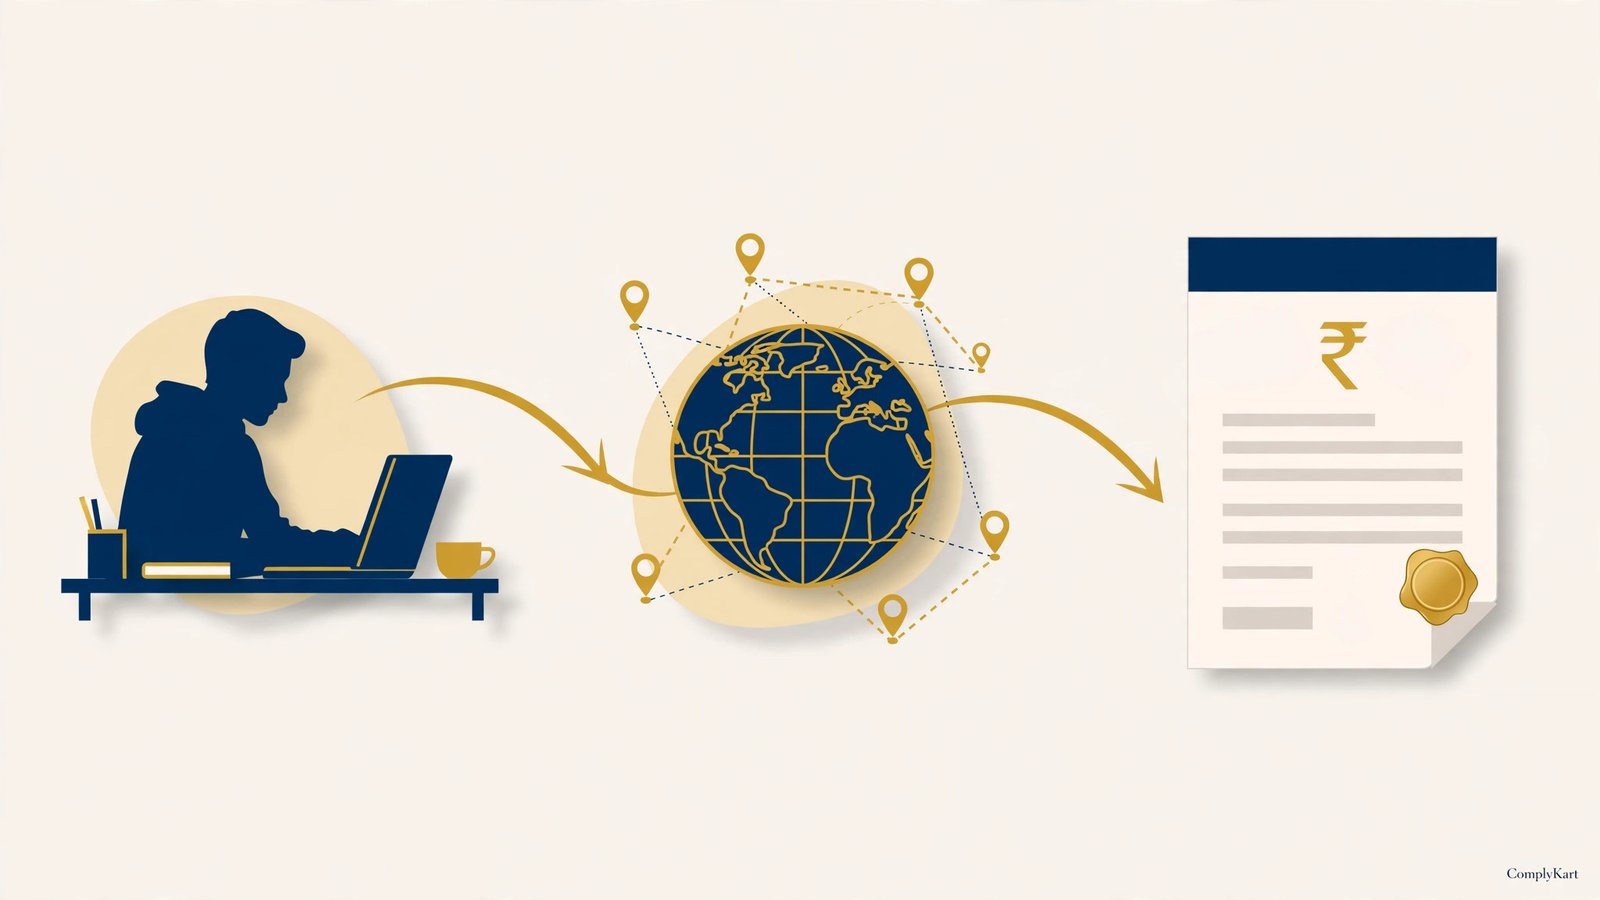
Freelancers supplying services must register for GST once aggregate turnover crosses ₹20 lakh in a financial year (₹10 lakh in Mizoram, Tripura, Manipur and Nagaland). Foreign clients don't remove the obligation — export of services is zero-rated through a yearly LUT — and the composition scheme is not available to anyone making inter-state supplies, which includes exports.
Freelancers ask me about GST more than any other tax. The confusion is understandable — the rules were written with traders and manufacturers in mind, and service professionals have to translate everything into their own context. Here are the questions that come up, with straight answers.
Key takeaways
- Service freelancers: mandatory GST registration at ₹20 lakh aggregate turnover (₹10 lakh in Mizoram, Tripura, Manipur and Nagaland) — turnover, not profit.
- Exports are zero-rated, not exempt: file the Letter of Undertaking (LUT) every April to avoid paying IGST upfront.
- The composition scheme is unavailable to anyone making inter-state supplies — which includes service exporters.
- Collect a FIRC for every foreign receipt, and check reverse-charge exposure on services you buy from abroad.
Do I need GST registration at all?
It depends on your turnover. If you supply services, registration becomes mandatory once your aggregate turnover crosses ₹20 lakh in a financial year (₹10 lakh in Mizoram, Tripura, Manipur, and Nagaland). Aggregate turnover means everything — all your supplies, across all states, including exempt ones.
Two things freelancers get wrong here. First, the threshold is about turnover, not profit — ₹20 lakh of billings, even if your costs eat most of it. Second, crossing the threshold creates the liability; you then have 30 days to register, and the registration applies from the date you crossed it. Bill a client in April, cross ₹20 lakh in November, and November's invoices needed GST on them.
All my clients are abroad. Do I still need to register?
Yes — if you cross the threshold. Export of services does not exempt you from registration. What it does is change the tax treatment: exports are zero-rated, which means you charge 0% GST on foreign client invoices.
But "zero-rated" is not "ignore GST." You still file returns, and you still need a mechanism for the zero rating. That mechanism is the Letter of Undertaking (LUT) — a yearly declaration filed on the GST portal that lets you export services at zero rate without paying IGST upfront. With a valid LUT, you export without blocking your input tax credit. Without it, you pay IGST on exports and claim it back as a refund — which is slower, messier, and ties up your money.
File the LUT in April. It takes minutes, it is free, and forgetting it is one of the most common freelancer mistakes I see.
Can I just take the composition scheme? It looks simpler.
No — and this is the trap. The composition scheme is not available to anyone making inter-state supplies, and exports of services count as inter-state supplies. A freelancer with foreign clients cannot legally be in composition.
Even for purely domestic freelancers, composition is usually a bad deal: you pay tax out of your own pocket at a flat rate, you cannot claim input tax credit, and your clients cannot claim credit on your invoices — which makes you more expensive than a regular-registered competitor for any B2B client. Composition was designed for small local traders. It was not designed for you.
What about invoices in foreign currency?
Your invoice can show the foreign currency your client pays in, but for GST purposes the value is converted to rupees at the RBI reference rate (or the CBIC-notified rate) on the date of supply. Keep a record of the rate you used — it goes into your returns, and "I used whatever Google showed" is not a defensible position in an audit.
What records do I actually need to keep?
Less than a manufacturer, more than most freelancers keep. Invoices issued (with GSTIN once registered, invoice numbers in a continuous series), foreign inward remittance certificates (FIRCs) from your bank for every foreign receipt — these are your proof of export — the LUT acknowledgement, and your filed returns. The FIRC point matters: without it, a foreign receipt is just an unexplained credit in an audit.
What about GST on things I buy from abroad?
Here is the mirror image most freelancers miss. When you import services — a foreign SaaS subscription, stock photos, a subcontractor sitting in another country — the reverse charge mechanism can apply. Under RCM, the recipient of the service pays the GST instead of the supplier. If you are registered, you pay it and claim it back as input tax credit in the same return, so the net cost is usually nil — but the entries must still be made.
The uncomfortable part: RCM liability can arise even if you are below the registration threshold, because the threshold exemption does not cover reverse-charge supplies in all cases. If you pay significant amounts to foreign vendors, check your RCM position separately. It is a small corner of the law that produces a surprising number of notices.
Should I register voluntarily, before hitting ₹20 lakh?
Sometimes, yes. If your clients are GST-registered businesses, they prefer suppliers who can give them a proper tax invoice with input credit. Being registered can win you corporate clients you would otherwise lose to a registered competitor. The cost is compliance — monthly or quarterly returns, depending on your turnover — so weigh it honestly. Voluntary registration is a business decision, not a tax obligation, and it should be made like one.
Freelancing across borders adds one layer of tax complexity to an already uncertain income. Getting the GST structure right early — registration timed correctly, LUT filed, FIRCs collected — means the tax side runs quietly in the background while you do the actual work. If you are approaching the threshold or signing your first foreign client, that is the moment to get professional advice, not after the first notice arrives.
Frequently asked questions
Does the ₹20 lakh freelancer threshold count profit or turnover?
Turnover — aggregate turnover, meaning all supplies across all states, including exempt ones. ₹20 lakh of billings triggers it even if your costs eat most of it. Once crossed, you have 30 days to register, effective from the crossing date.
I only have foreign clients. Can I skip GST registration?
No. Export of services does not exempt you from registration once you cross the threshold. What changes is the tax treatment: exports are zero-rated, so you charge 0% — but you still register, still file returns, and still need the LUT.
What happens if I forget to file the LUT?
Without a valid LUT you must pay IGST on your exports and claim it back as a refund — slower, messier, and it ties up your money. The LUT takes minutes, is free, and is filed each April. Forgetting it is one of the costliest small mistakes in freelancer GST.
Can I claim input tax credit as a freelancer?
Yes, once registered as a regular taxpayer — GST paid on business expenses like software, equipment and professional services becomes input tax credit against your output liability. This is one more reason composition is a poor fit: it blocks ITC entirely.
Is voluntary registration before ₹20 lakh worth it?
Sometimes. GST-registered corporate clients prefer suppliers who give proper tax invoices with input credit, and being registered can win you clients you would otherwise lose. Weigh that against the compliance cost — monthly or quarterly returns — and make it a business decision, not a reflex.

Comments
No comments yet — ask the first question below.
Join the discussion
Questions go straight to our expert desk. Comments appear after a quick review — no spam, no noise.