
IN BRIEF
The Fund of Funds for Startups is a Government of India scheme, operated by SIDBI under DPIIT's oversight, that commits public capital to SEBI-registered Alternative Investment Funds, which in turn invest in DPIIT-recognised startups; founders cannot apply to the fund directly. Budget 2025-26 announced a second fund, Startup India FoF 2.0, with a fresh ₹10,000 crore corpus on the same indirect design.
Every few months, a founder asks me some version of the same question: "The government has put ₹10,000 crore into a Fund of Funds for startups — how do I apply?" The honest answer disappoints people. You do not apply. There is no application form with your name on it, no portal window, no SIDBI officer who will sanction a cheque for your company. The money reaches founders, but it reaches them indirectly, through venture funds that take their own investment decisions. Once you understand that design, the scheme stops looking like a locked door and starts looking like what it is — a bigger, better-funded pool of venture capital sitting one level above you.
And there are now two of these funds, not one. The first Fund of Funds for Startups (FFS) was announced in 2016 with a ₹10,000 crore corpus. In the Union Budget presented on 1 February 2025, the Finance Minister announced that a new Fund of Funds, with expanded scope and a fresh contribution of another ₹10,000 crore, would be set up. That second fund has since been notified as the Startup India Fund of Funds 2.0, and DPIIT has issued its operational guidelines. Same design. Same indirect route. Double the headline money.
Two funds, one design
Here is the shape of both schemes side by side.
| Point | Fund of Funds for Startups (FFS 1.0) | Startup India FoF 2.0 |
|---|---|---|
| Announced | 2016, under the Startup India Action Plan | Budget 2025-26, as a new fund with a fresh ₹10,000 crore contribution; notified in 2026 |
| Corpus | ₹10,000 crore | ₹10,000 crore, spread across the 16th and 17th Finance Commission cycles |
| Who runs it | SIDBI operates the scheme; DPIIT monitors it | SIDBI is the initial Implementation Agency; DPIIT will onboard one more domestic agency |
| Who receives the money | SEBI-registered Alternative Investment Funds (AIFs) | SEBI-registered Category I and II AIFs |
| Who finally gets invested in | DPIIT-recognised startups chosen by those AIFs | DPIIT-recognised startups chosen by those AIFs |
| Can a founder apply directly? | No | No |
Read the last row again. It is the whole post in two letters.
How the money actually travels
The chain has four links, and your company sits only at the last one.
- The government commits capital. The corpus is not handed out in one year. Under FoF 2.0, commitments to AIFs are spread across the 16th and 17th Finance Commission cycles, so the money enters the system in tranches over a long period.
- SIDBI runs the process. SIDBI, as Implementation Agency, screens AIF proposals and does the initial due diligence. Under FoF 2.0, a Venture Capital Investment Committee then evaluates the shortlisted funds on the fund team's track record, its fund management capability and its investment strategy.
- AIFs raise the rest privately. A supported AIF must pull in private money alongside the government's commitment. The FoF 2.0 guidelines mandate minimum private capital mobilisation, and under the first fund, AIFs supported by the scheme were expected to invest at least twice the amount committed under the FFS into startups. Government money is the anchor, never the whole fund.
- The AIF invests in startups — on its own judgement. The fund manager picks companies, negotiates terms and writes the cheque. The government does not sit in that room. Neither does SIDBI.
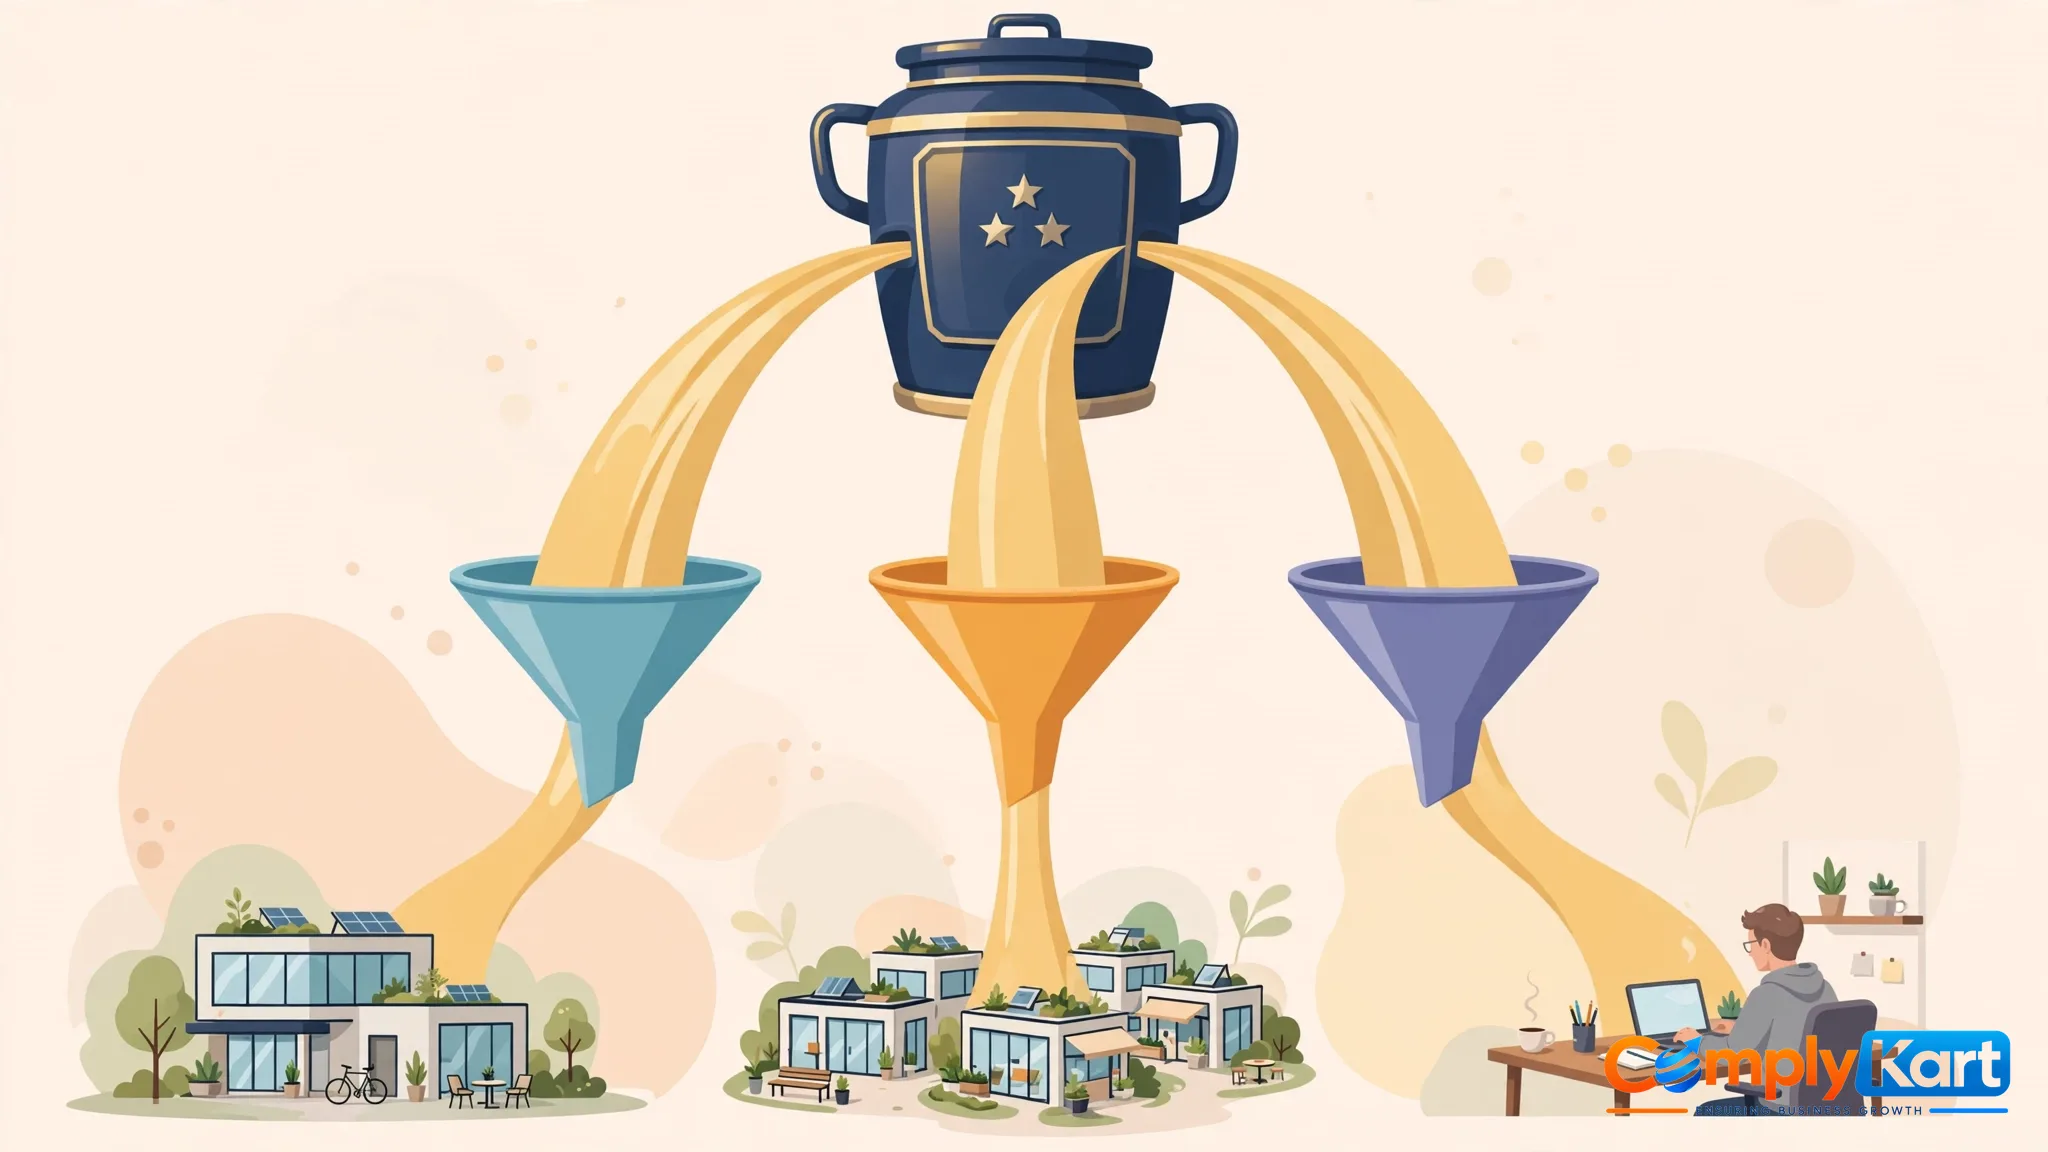
Think of it the way a wholesale market feeds a neighbourhood shop. The wholesaler never sells a single tomato to the family at the end of the lane, yet the family eats because the wholesaler kept the shop stocked. The Fund of Funds is the wholesaler. The AIF is the shop. You are funded when the shop decides your business is worth stocking — not when you queue up at the wholesale godown.
Why the government works this way
Founders sometimes read the indirect design as bureaucratic distance. It is deliberate, and the Budget speech of 1 February 2025 tells you why. The Finance Minister told Parliament that the AIFs for startups had received commitments of more than ₹91,000 crore, supported by a Fund of Funds set up with a government contribution of ₹10,000 crore. Sit with those two numbers. Roughly ₹9 of commitments gathered around every ₹1 the government put in.
That is the point of the design. A government department cannot judge ten thousand pitch decks, and it should not try. What it can do is anchor credible fund managers, insist they raise serious private money beside the public money, and let people whose careers depend on picking winners do the picking. The public money takes the first, patient position; private capital follows because the anchor is there.
One confusion to clear before it costs you time: the same Budget also said a Deep Tech Fund of Funds would be explored. That was a separate idea under exploration, aimed at next-generation deep tech. It is not FoF 2.0, and FoF 2.0's priority segments are a different thing — though deep tech funds are one of those segments, as the next section shows.
What FoF 2.0 changed
The second fund is not a photocopy of the first. The operational guidelines issued by DPIIT sort eligible AIFs into four segments, each with its own parameters on corpus, government contribution limits, tenure and private capital mobilisation:
- Deep tech funds — backing startups building hard technology with long gestation.
- Micro venture capital funds — smaller funds supporting early growth-stage startups, the cheques that bigger funds often skip.
- Innovative, technology-led manufacturing funds — for startups making things, not only apps.
- Sector and stage agnostic funds — the generalists.
The selection runs in two stages: the Implementation Agency screens and does due diligence first, and the Venture Capital Investment Committee evaluates after that. A portion of returns can also be set aside for ecosystem work such as mentorship and shared infrastructure. For a founder, the practical meaning is narrower and simpler — over the coming years, more AIFs, including smaller and more specialised ones, will be raising and deploying with a government anchor behind them. The pool of investors who might plausibly write your cheque gets wider, especially if you are in deep tech, manufacturing, or an early stage that large funds ignore.
What this means for you, practically
Your DPIIT recognition is the entry ticket, not the prize. Both funds flow only into startups recognised by DPIIT — the FoF 2.0 release says the AIFs will invest in entities recognised as startups by the Central Government. Without recognition, an AIF investing under this scheme cannot count you. With recognition, you are inside the universe these funds can back. Nothing more is promised, and anyone who promises more is selling you something.
You raise from AIFs the normal way. You build a deck, you target funds whose thesis fits your sector and stage, you go through diligence, you negotiate a term sheet. The government anchor changes the fund's economics; it does not change your fundraising process by one step. If a fund has received an FoF commitment, that is background knowledge worth having — it tells you the fund has passed SIDBI's screening and the committee's evaluation — but the fund will still say no if your numbers do not work.
Keep the neighbouring benefits separate in your head. Recognition also sits behind the tax side of Startup India. If you are approaching profitability, the Section 80-IAC tax holiday guide explains the three-year exemption and its Inter-Ministerial Board certificate, and our comparison of the 80-IAC holiday with the 115BAA and 115BAB tax routes helps you decide which route your company should actually take. Those are claims you file. The Fund of Funds is not.
Traps I keep seeing
Paying an agent for "FFS approval". There is nothing to approve. No consultant can get your startup sanctioned under the Fund of Funds, because no such sanction exists. Money paid for that promise is money gone.
Confusing three different schemes. The Seed Fund Scheme works through incubators, and there you do apply. The credit guarantee scheme works through lenders, and there the bank applies its mind to your loan. The Fund of Funds works through AIFs, and there you simply raise venture capital. Founders waste months writing to the wrong door because all three carry the Startup India name.
Waiting for government money instead of raising. FoF commitments land with funds over years, across two Finance Commission cycles. Your runway is measured in months. Raise from the market that exists today; if some of that market turns out to be government-anchored, treat it as a pleasant detail.
The honest summary
₹10,000 crore went in first. Another ₹10,000 crore is now following it, with a wider scope and a sharper focus on deep tech, early growth and manufacturing. None of it will ever arrive in your bank account with the government as the sender. It arrives, when it arrives, as an investment from a fund that chose you — which means your job has not changed at all: get recognised, build something a fund manager can defend in an investment committee, and go and raise.
If you want the full map of what recognition puts within your reach — the tax holiday, the IPR rebates, the procurement relaxations and this fund — our DPIIT recognition benefits page walks through the Fund of Funds section alongside every other benefit, and we can tell you plainly which of them your company can actually use.

Comments
No comments yet — ask the first question below.
Join the discussion
Questions go straight to our expert desk. Comments appear after a quick review — no spam, no noise.