
Two of the most useful funding routes for Indian founders sit behind government guarantees, and founders constantly mix them up. One asks who you are. The other asks what stage your company is at. Stand-Up India reserves serious bank credit for SC/ST and women entrepreneurs starting something new. CGSS — the Credit Guarantee Scheme for Startups — backs loans to DPIIT-recognised startups that have outgrown grants but cannot offer a bank any security. Both are loans, neither is a grant, and the guarantee behind each is what gets the bank to listen.
The short answer: Stand-Up India, in its original run up to March 2025, gave composite bank loans of ₹10 lakh to ₹1 crore to SC/ST and women entrepreneurs for greenfield enterprises, repayable over up to 7 years including a moratorium of up to 18 months. CGSS guarantees loans to DPIIT-recognised startups up to ₹20 crore per borrower — covering 85% of the default amount up to ₹10 crore and 75% above that — so banks and venture-debt funds can lend without collateral.
Stand-Up India: who it is for, exactly
Launched on 5 April 2016 by the Department of Financial Services, Stand-Up India has a specific social design: every branch of every scheduled commercial bank is expected to finance at least one SC/ST borrower and at least one woman borrower. The loan is a composite facility — term loan plus working capital in one sanction — between ₹10 lakh and ₹1 crore.
First, check the scheme's current status. The Department of Financial Services records that the Stand-Up India scheme ran up to 31 March 2025, in line with the 15th Finance Commission cycle. Budget 2025-26 announced a successor aimed at the same founders — term loans up to ₹2 crore for 5 lakh first-time women, Scheduled Caste and Scheduled Tribe entrepreneurs over the next five years — and the department's page notes that the proposal is still under preparation. So read the terms in this section as the original scheme's terms, and confirm what is live at your bank branch before you apply.
Eligibility is narrow, deliberately. The borrower must be an SC/ST entrepreneur and/or a woman entrepreneur, aged 18 or above. The enterprise must be greenfield — your first venture in manufacturing, services, trading or activities allied to agriculture. Expanding an existing business does not count, however worthy. If the borrower is a company, LLP or firm, at least 51% of shareholding and controlling stake must sit with the SC/ST or woman entrepreneur. And you must not be in default to any bank or financial institution.
Repayment terms are built for a business that needs time to stand up: up to 7 years including a moratorium of up to 18 months. Margin money can go up to 15% of project cost through convergence with eligible central or state schemes, but at least 10% must be your own contribution. Interest is capped by the guidelines at the bank's lowest applicable rate for the category, not exceeding the base rate (MCLR) plus 3% plus tenor premium. Loans are secured by the assets created, and can be covered by the Credit Guarantee Fund Scheme for Stand-Up India (CGFSI) through NCGTC instead of collateral. Working capital up to ₹10 lakh can come as an overdraft with a RuPay debit card.
Applications under the original scheme went through a bank branch, standupmitra.in, Jan Samarth, or your district's Lead District Manager. One myth to drop first: there is no interest subsidy inside this scheme. Margin-money support through other schemes is real; a subsidised rate is not.
CGSS: the startup guarantee, and its new ceiling
CGSS works from the opposite direction. It does not care who the founder is; it cares that the company is a DPIIT-recognised startup a lender can appraise. DPIIT runs the scheme; the National Credit Guarantee Trustee Company (NCGTC) operates it.
The headline number changed recently, and many guides still carry the old one. Under the revised framework notified in 2025, the maximum debt eligible for guarantee cover is ₹20 crore per borrower, doubled from ₹10 crore. On transaction-based cover, the Trust guarantees 85% of the amount in default for loans up to ₹10 crore, and 75% above ₹10 crore. An umbrella model also exists for SEBI-registered AIFs and venture-debt funds, where cover equals actual losses or 5% of the pooled investment, whichever is lower. Covered instruments run wider than a plain term loan: working capital, venture debt, mezzanine and subordinated debt, and debentures can all sit under the guarantee.
The fee is an Annual Guarantee Fee of 2% on transaction-based cover — 1.5% for startups in the North-East and women-led startups, and 1% for startups in the 27 identified Champion Sectors. The lender pays NCGTC; expect the cost priced into your deal. Check the maths: a fully drawn ₹4 crore venture-debt facility at 2% carries roughly ₹8 lakh a year of guarantee cost; in a Champion Sector at 1%, roughly ₹4 lakh. Worth knowing before you negotiate, not after.
Who qualifies for CGSS — and who quietly doesn't
The tests are short: DPIIT recognition; not in default to any lending or investing institution; not classified as an NPA; eligibility certified by the member institution. Lenders who can use the scheme are scheduled commercial banks and financial institutions, RBI-registered NBFCs rated BBB or above with net worth of at least ₹100 crore, and SEBI-registered AIFs.
The quiet disqualifier is viability. Guarantee cover issues automatically once parameters are met, but the loan sanction does not — the institution appraises your project under its own credit norms first. A pre-revenue startup with no visible debt-service capacity will usually fail that appraisal, guarantee or not. CGSS rewards startups that already sell something. Earlier than that, the grant routes in our startup grants playbook are the honest first step — and DPIIT recognition is the document everything else hangs on.
How the CGSS process actually runs
You apply for the loan, not the guarantee. Approach a member institution directly, or apply through Jan Samarth and choose your lender. The institution examines feasibility, sanctions the credit if the file works, and simultaneously applies on the NCGTC portal — cover issues automatically once eligibility parameters are met. On default, the institution invokes the guarantee and the Trust pays the covered share to the institution. Your debt is not forgiven; recovery against the company continues.
Paperwork decides speed here. DPIIT recognition must be current, the compliance record clean, and financials consistent across MCA filings, GST returns and bank statements. Still setting up? Finish your startup registration and company incorporation first, and cost annual compliance with the compliance fee calculator — lenders notice tidy books.
Stand-Up India or CGSS: which door is yours?
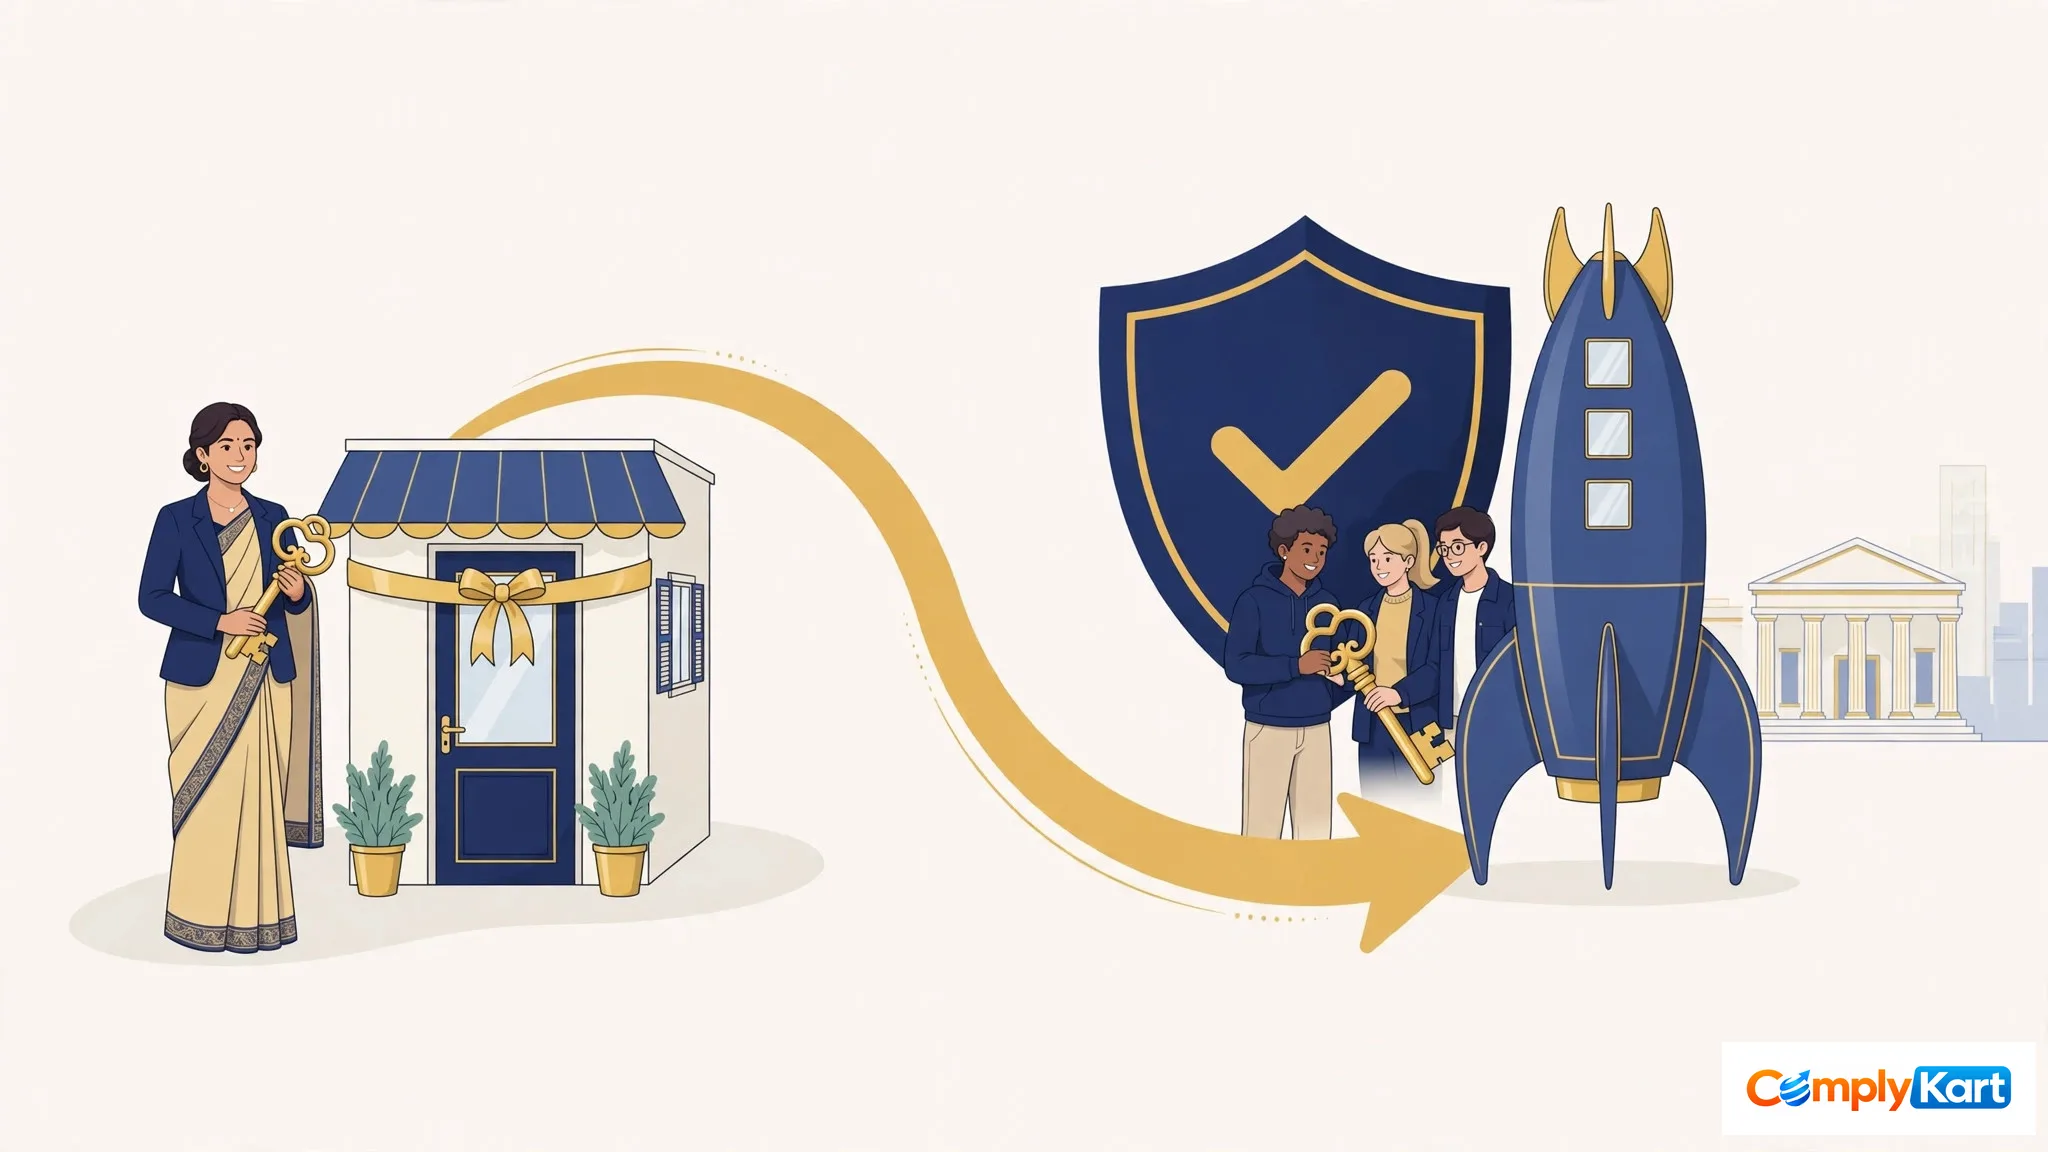
Two different keys. The Stand-Up India key is cut to the founder: SC/ST or woman, first venture, up to ₹1 crore, from a bank branch. The CGSS key is cut to the company: DPIIT-recognised, revenue-bearing, up to ₹20 crore of guaranteed debt, from banks, NBFCs and venture-debt funds. A woman founder with a recognised startup and early revenue could qualify for both — never on the same facility — and the choice should follow amount and stage, not the brochure. Smaller, first-venture, branch-led: Stand-Up India, subject to the status note above. Larger, growth-stage: CGSS.
Frequently asked questions
Is Stand-Up India only for individuals, or can my company apply?
Companies, LLPs and firms can apply, provided at least 51% of the shareholding and controlling stake is held by the SC/ST and/or woman entrepreneur. A company where the eligible founder is a minority shareholder does not qualify.
Can I use Stand-Up India to expand my existing business?
No. The scheme funds greenfield enterprises only — the beneficiary's first venture in the sector. Expansion of an existing unit belongs to MUDRA, CGTMSE or a regular bank facility.
What does DPIIT recognition need to look like for CGSS?
It must be live and current, and the entity must fit the startup definition — incorporated within the recognition window and within the turnover ceiling. If recognition has lapsed or the entity has crossed the definition limits, the file fails at the first test.
Can a startup take both a grant and a CGSS-backed loan?
Yes — they are different instruments, and founders routinely sequence them: grant first, debt when revenue starts. What you cannot do is stack two guarantees on one facility, and grant schemes have their own caps on prior government support that you must declare honestly.

Comments
No comments yet — ask the first question below.
Join the discussion
Questions go straight to our expert desk. Comments appear after a quick review — no spam, no noise.