
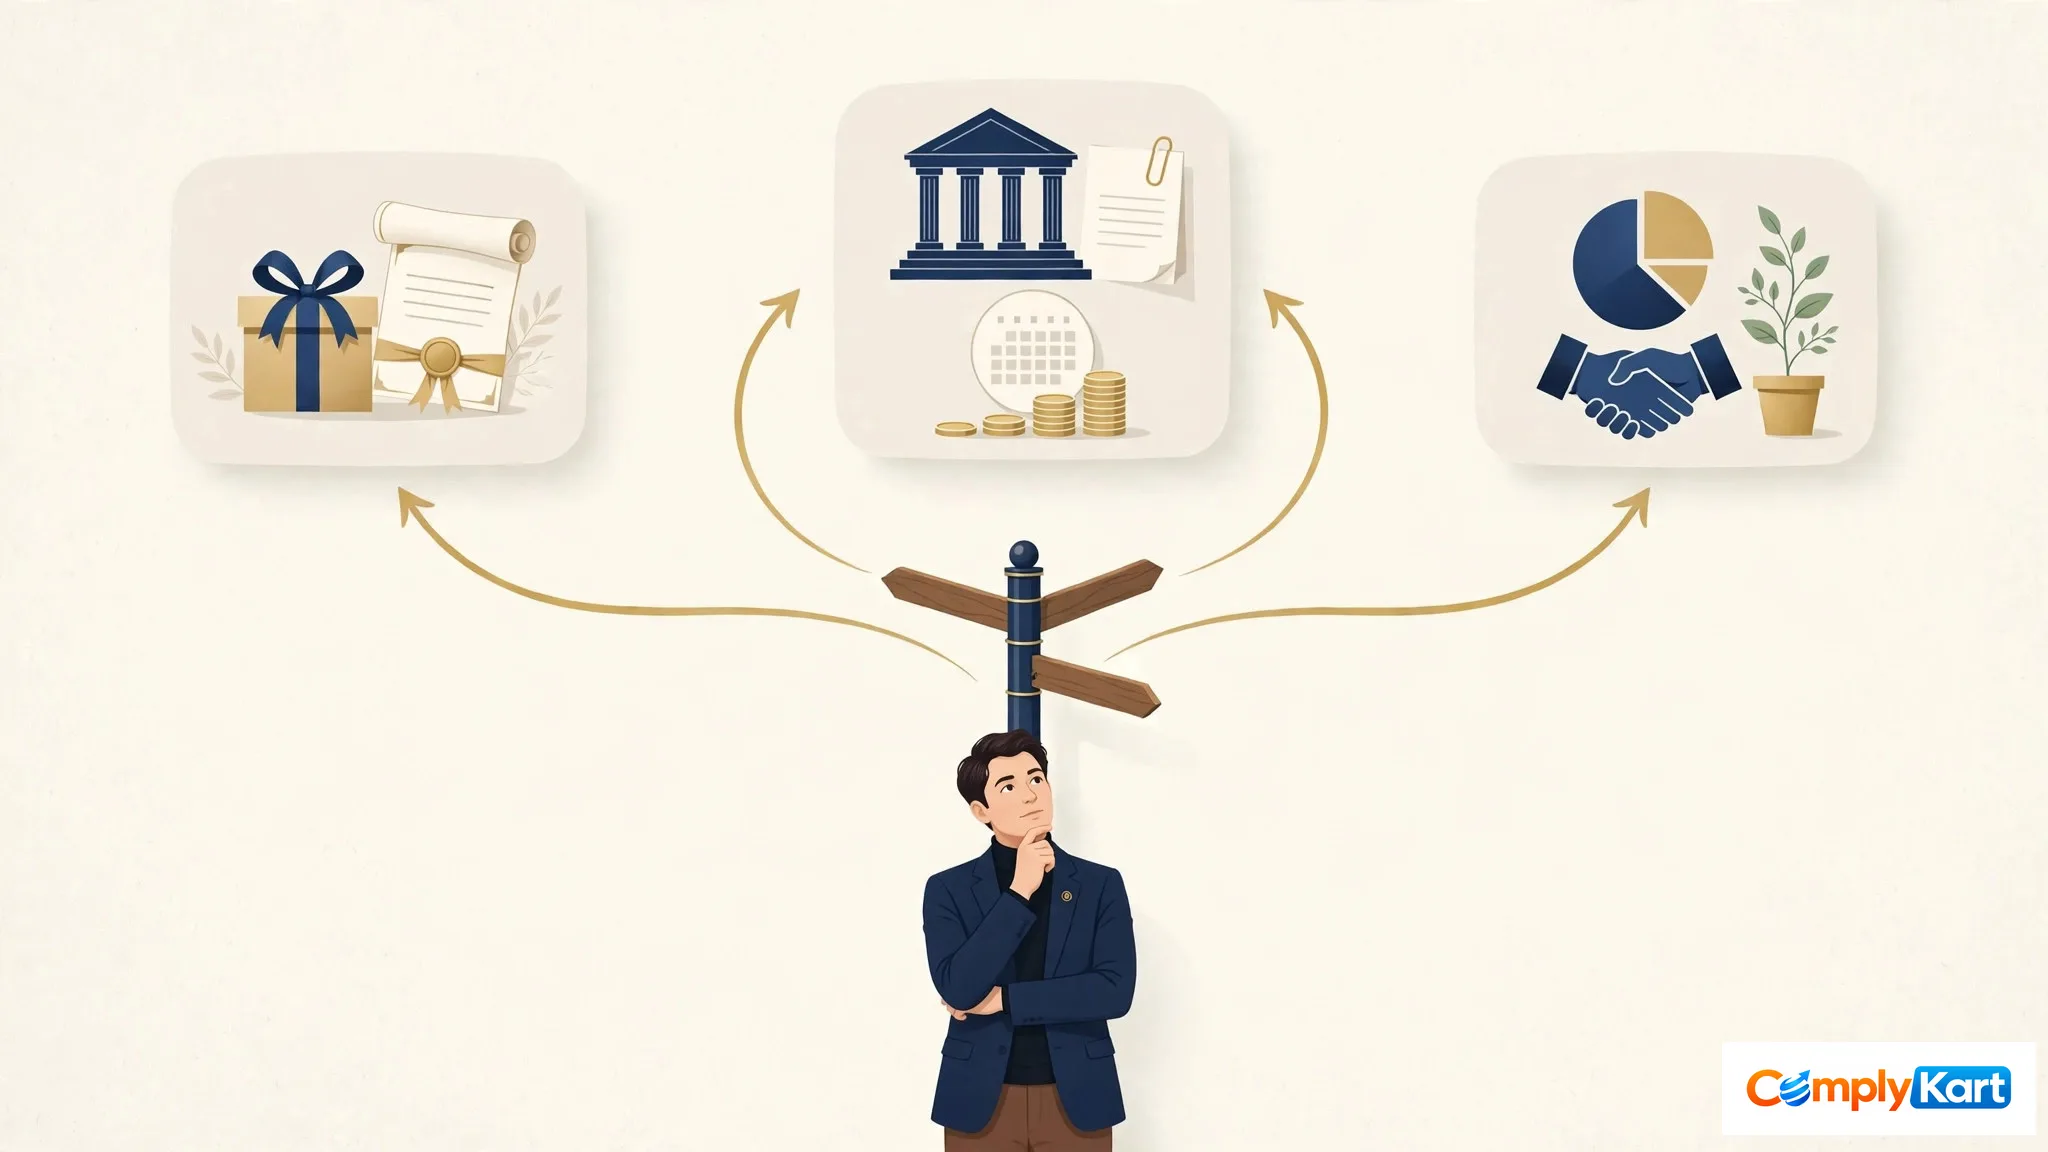
"We need ₹30 lakh" is where most funding conversations start, and it is the wrong starting point. The right question is what kind of money it should be — a grant, a loan and equity can all put ₹30 lakh in your bank account, and they could not differ more in what they take back. Founders who pick by habit — equity because startups "raise rounds", loans because grants "take too long" — pay for the choice for years.
The short answer: A grant is money you neither repay nor give ownership for, won through competition and paid in milestone tranches. A loan is money you repay with interest while your ownership stays untouched — and government guarantee schemes now let many founders borrow without collateral. Equity is money you never repay, bought with a slice of your company forever. Match the instrument to the job: grants for validation and prototypes, debt for assets and working capital once revenue exists, equity for growth debt cannot safely fund.
The three routes, honestly defined
Think of it as three ways to get a house. A grant is a gift deed — the house comes with conditions on how you use it, and someone checks that you do. A loan is a mortgage — the house is yours, but a fixed payment leaves your account every month, good business or bad. Equity is taking a co-owner — no monthly payment, ever, but a share of the house, and a say in it, is someone else's permanently. None of the three is "free". They charge in different currencies: time and compliance, cash flow, or ownership.
| Grant | Loan (incl. guaranteed) | Equity | |
|---|---|---|---|
| Repay? | No | Yes, with interest | No |
| Ownership given up | None | None | Yes — permanently |
| Who decides | Committee / incubator | Bank or NBFC | Investor |
| Typical speed | 3–12 months | Weeks to ~3 months | 3–9 months |
| Gate you must pass | Innovation + selection | Repayment capacity | Growth story + traction |
| Hidden cost | Milestones, reports, utilisation certificates | EMI pressure in lean months | Dilution compounds every round |
When a grant is the right money
Grants pay for proof, not scale. Prototypes, product trials, first pilots — spending that produces evidence rather than revenue. If you need to show that something works before anyone funds the next stage, grant money is designed for exactly that gap, and it takes no ownership in return. Our startup grants playbook maps the live routes — central schemes, state grants, sector programmes — and the Startup India Seed Fund guide covers the best-known one in detail.
The catches are real. Selection is competitive and committee-driven; most schemes disburse through incubators in milestone tranches, with utilisation certificates before the next instalment. Timelines run in months — and schemes open and close: the Seed Fund's startup application window is currently closed, so check the portal before planning around any scheme. Grants are generally taxable as income unless they are capital-purpose grants applied exclusively to the specified project — and a grant tied to a specific asset is not simply tax-free either: under Explanation 10 to Section 43(1) of the Income-tax Act it reduces the asset's actual cost, so the benefit comes back through lower depreciation. Talk to your CA before the money lands. And grants interact: the Seed Fund excludes startups that have already taken more than ₹10 lakh of government monetary support, so the order you apply in decides what stays open. The rejection patterns repeat across schemes — read them before you apply.
When a loan is the right money
Debt suits money that earns its way back: machinery that raises output, inventory against confirmed orders, working capital on a short cycle. The test is simple — can the business service an EMI in a bad month, not just a good one? If yes, a loan is often the cheapest growth capital available, because the ownership cost is zero.
The old objection — "the bank wants my house" — is weaker than it was. MUDRA covers micro loans up to ₹20 lakh without collateral; CGTMSE guarantees facilities up to ₹10 crore for micro and small enterprises; Stand-Up India finances first ventures of SC/ST and/or women entrepreneurs up to ₹1 crore; CGSS guarantees startup debt up to ₹20 crore. None of these schemes removes the appraisal: guaranteed or not, a lender must believe the cash flows. Pre-revenue startups usually fail that test — which is why debt is a second-stage instrument for most tech startups, and a first-stage one for trading and manufacturing units with early sales.
When equity is the right money
Equity funds what debt cannot: losses today for a market tomorrow. If the plan is to spend ahead of revenue — two years building a product, buying growth in a new geography — there is no cash flow to service a loan, and forcing one onto the business is how founders drown good companies. An investor also brings hiring networks, follow-on capital, and a second brain in the room.
The price is permanent. Every round dilutes you, and early rounds are cheapest in rupees and dearest in percentage. Equity also changes governance — reporting, board seats, investor consent on big decisions. Chosen knowingly, that is a fair trade; chosen by default, it is an expensive one. Founders mostly reach institutional equity through funds — the Fund of Funds for Startups routes public money via SIDBI into SEBI-registered AIFs, which then invest in DPIIT-recognised startups.
One need, three prices: a worked example
Say you need ₹30 lakh for a pilot production line. As a grant, the cash cost is zero and ownership stays 100% — but expect a 3–12 month selection cycle, milestone tranches, and a real chance of rejection. As a loan at an assumed 10% over 5 years, the EMI is roughly ₹63,700 a month — about ₹38.2 lakh repaid in total, so ₹8.2 lakh of interest buys you speed and full ownership. As equity, ₹30 lakh for, say, 10% implies a ₹3 crore valuation; if the company is worth ₹10 crore in five years, that 10% has cost you ₹1 crore of value — the dearest option by far, unless the investor's help is what gets you to ₹10 crore at all. Same ₹30 lakh, three very different bills. (The interest figure is an illustration at an assumed rate; your lender's rate will differ.)
A decision framework you can run in ten minutes
- Is there revenue to service debt? No revenue yet → grant or equity. Steady revenue → debt enters the room.
- What does the money buy? A prototype or trial → grant. A revenue-generating asset or order cycle → debt. Market creation and team ahead of revenue → equity.
- How much ownership can you give? If control matters, exhaust grant and debt routes first.
- How fast must it land? A confirmed order in 30 days cannot wait for a grant committee. Match the instrument's clock to yours.
- What does taking it close? Some grants cap prior government support, and fellowships stop when other funding arrives. Plan the order, not just the amounts.
Whatever route you choose, the paperwork underneath decides your speed — DPIIT recognition for grants and CGSS, clean registrations for lenders, tidy cap-table records for investors. Our state startup grants guide covers the grant side state by state; if the structure needs work, start with startup registration and company incorporation.
Frequently asked questions
Can I combine a grant, a loan and equity in one startup?
Yes — most well-funded startups do, in sequence: grants first for validation, debt once revenue can service it, equity for growth. Declare every government support you have received when a scheme asks; undisclosed double-funding of the same project is where founders get disqualified.
Is a government-guaranteed loan the same as a grant?
No. MUDRA, Stand-Up India, CGTMSE and CGSS are loans or guarantees behind loans. Every rupee is repaid with interest. The guarantee only removes the collateral demand — it does not make the money free.
Do grants affect my taxes?
Generally, yes — a grant is usually taxed as income unless it is a capital-purpose grant applied exclusively to the specified project. Eligible startups can also claim the Section 80-IAC deduction — 100% of profits for any three consecutive years out of the first ten, if you are an eligible DPIIT-recognised startup with Inter-Ministerial Board approval — which can shelter the impact when the grant year falls inside the block you choose. Confirm your position with your CA in the year the grant is received.
I'm pre-revenue. Should I even try for a loan?
You can apply, but expect the appraisal to fail on debt-service capacity — the guarantee protects the lender; it does not waive your need to repay. Pre-revenue founders are usually better served by grants, fellowships and seed equity first.

Comments
No comments yet — ask the first question below.
Join the discussion
Questions go straight to our expert desk. Comments appear after a quick review — no spam, no noise.