
IN BRIEF
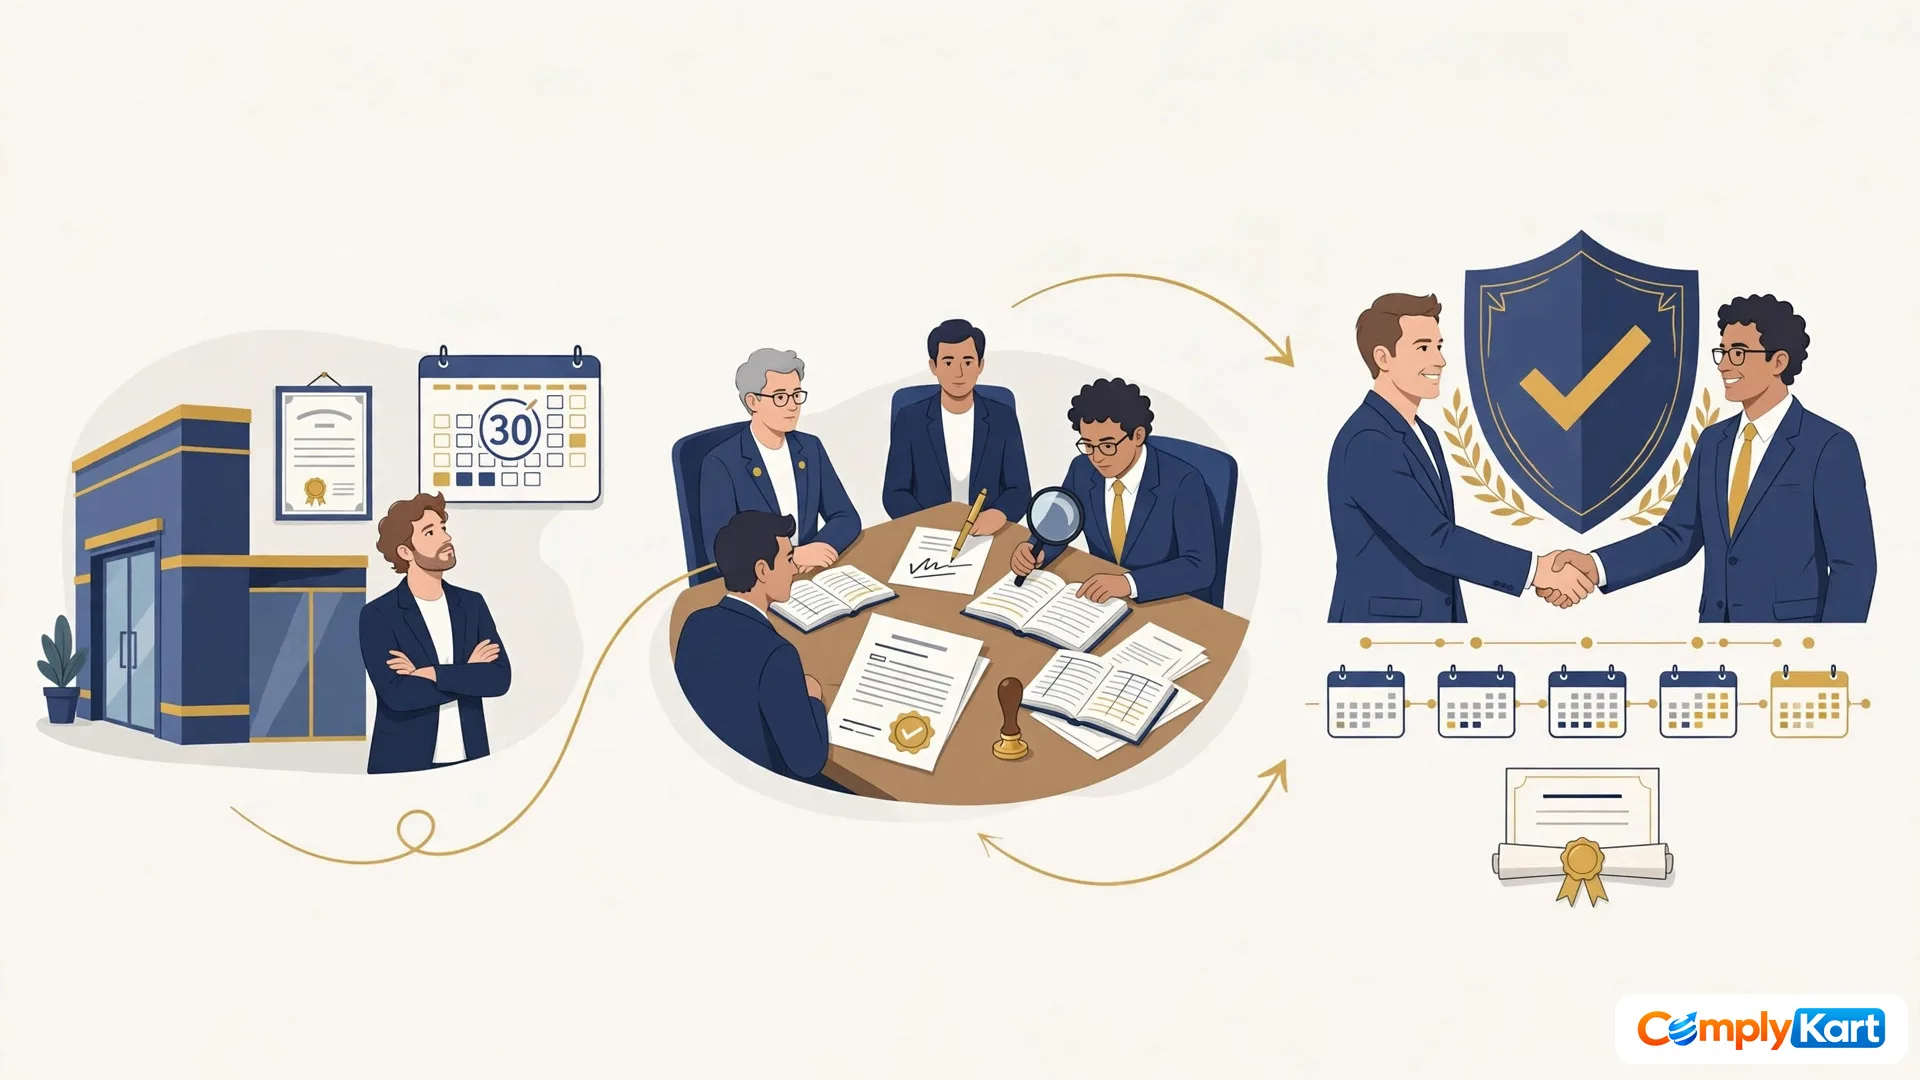
Appointing an auditor in a private limited company is the process by which the company engages a practising Chartered Accountant to audit its accounts under Chapter X of the Companies Act, 2013. The Board must appoint the first auditor within 30 days of registration under section 139(6), and the appointment is reported to the Registrar in Form ADT-1 within 15 days under the Companies (Audit and Auditors) Rules, 2014.
Your Board must appoint the first auditor within 30 days of the company's registration, under section 139(6) of the Companies Act, 2013. The appointment is reported to the Registrar in Form ADT-1 within 15 days. The first auditor serves only until the first AGM, where the members appoint an auditor for five years.
A new private limited company meets its first statutory deadline fast. There is no reminder from the Registrar, no portal nudge, nothing in the incorporation certificate that tells you the clock is running. Thirty days after registration, the law expects your company to have an auditor. Miss it, and the appointment does not vanish — it gets harder, costlier, and it moves out of the Board's hands.
This guide walks through the whole appointment: the first auditor, the ADT-1 question everyone argues about, the five-year appointment at the first AGM, who can and cannot audit you, and what a delay actually costs.
Who appoints the first auditor, and by when?
The Board of Directors appoints the first auditor. Not the shareholders, not the promoters in their personal capacity — the Board, by resolution at a Board meeting, within thirty days from the date of registration of the company. Section 139(6) of the Companies Act, 2013 says so in plain words, and it applies to every company other than a Government company.
Take a company registered on 1 April 2026. The Board must appoint its first auditor by 1 May 2026. If the Board appoints on 28 April, the ADT-1 filing (more on that below) falls due by 13 May.
If the Board misses the 30 days, the power does not stay with the Board. The Board must inform the members, and the members then appoint the first auditor at an extraordinary general meeting within ninety days. The Act does not spell out from which day those ninety days run, and practitioners read it from the date the members are informed — so keep the Board's intimation letter and its date on record. Either way, a missed deadline means calling a general meeting for something a Board resolution could have settled in an afternoon.
The first auditor holds office only until the conclusion of the first AGM. That meeting must be held within nine months of the close of the first financial year, under section 96(1). So the first auditor audits the company's opening period — from incorporation to that first AGM — and then the members make the real appointment.
Government companies run a different route: the Comptroller and Auditor General appoints the first auditor within sixty days of registration, under section 139(7). Everything in this guide is written for an ordinary private limited company.
Think of it like appointing the referee before the match starts. The players do not pick the referee after the game is played — and the referee cannot be someone on either team's payroll. The law wants an independent pair of eyes in place before the company's first set of accounts is drawn up, not after.
Is ADT-1 really mandatory for the first auditor?
Here is where the guides disagree, and the honest answer has two halves.
The first half: the form changed. On 30 May 2025 the MCA notified the Companies (Audit and Auditors) Amendment Rules, 2025 — G.S.R. 359(E) — effective 14 July 2025. The amendment substituted all four auditor forms, ADT-1 to ADT-4. The revised Form ADT-1 now carries a "Nature of Appointment" field that includes "First Auditor by Board of Directors" and "First Auditor by Members". Before that date, the form had no first-auditor option at all, and companies simply did not file ADT-1 for a Board-appointed first auditor. Most guides read the change as the end of the story: ADT-1 is now mandatory for the first auditor.
The second half: the rule did not change. The duty to file ADT-1 lives in Rule 4(2) of the Companies (Audit and Auditors) Rules, 2014, which says the notice of appointment under the fourth proviso to section 139(1) shall be filed in Form ADT-1. Section 139(1) covers appointments made by members. Section 139(6), which governs the first auditor, is not mentioned. G.S.R. 359(E) substituted the forms and amended the fraud-reporting rule — it did not amend Rule 4(2). So as a matter of strict law, no provision expressly compels ADT-1 for a Board-appointed first auditor. The Institute of Company Secretaries of India said exactly this when it wrote to the MCA on 16 April 2026 asking for a clarification. No clarification has followed.
So what should you do? File it. Three practical reasons settle the question even while the legal one stays open. First, the MCA V3 portal now expects the filing — the form offers the first-auditor option for a reason. Second, the AOC-4 annual filing validates the ADT-1 SRN, so a skipped ADT-1 creates friction a year later when you file your first financial statements. Third, the filing costs a few hundred rupees and fifteen minutes; the argument for skipping it saves nothing and buys a dispute with your own records. Prudence wins this one, and ICSI itself recommends filing while the clarification is pending.
The real appointment happens at the first AGM
The first auditor is a stopgap. At the first AGM, the members appoint an auditor to hold office from the conclusion of that AGM until the conclusion of the sixth AGM — a five-year term, under section 139(1). The appointment is made by ordinary resolution, and the company must inform the auditor of the appointment and file Form ADT-1 with the Registrar within fifteen days of the meeting.
Two details founders usually miss. The remuneration is fixed by the members at the AGM, under section 142 — agree it before the meeting, not after. And if an AGM fails to appoint or re-appoint an auditor, the existing auditor simply continues in office under section 139(10); the company does not suddenly find itself without one, but it should not treat that as a plan.
Every appointment after that runs on the same rhythm: five years at a time, ADT-1 within fifteen days of the AGM, until rotation or a vacancy interrupts it.
Who can be your auditor — and who cannot
Only a Chartered Accountant in practice can be appointed as a company auditor, under section 141(1). A firm — including an LLP — qualifies where the majority of its partners practising in India are Chartered Accountants, and only the CA partners may act and sign on the firm's behalf.
Section 141(3) then lists who cannot be appointed, and the list is mostly about conflicts of interest. Your auditor cannot be an officer or employee of the company, or the partner or employee of such an officer or employee. A relative of a director or key managerial personnel cannot audit you. Neither can a person who renders any of the prohibited services under section 144 to the company — bookkeeping, internal audit, actuarial or investment advisory work, among others.
The money limits matter most in practice, and Rule 10 of the Audit Rules puts numbers on them. A relative of the auditor may hold securities in the company up to ₹1 lakh in face value — above that, the auditor is disqualified. A person who is indebted to the company above ₹5 lakh cannot be its auditor. A person who has given a guarantee or security for a third person's debt to the company above ₹1 lakh cannot either. A business relationship — any transaction entered into for a commercial purpose — disqualifies too, though ordinary arm's-length dealings as a customer and professional services permitted under the Chartered Accountants Act are carved out.
Two more bars complete the list: a person in full-time employment elsewhere, and a person already holding appointment as auditor of more than twenty companies. And a fraud conviction disqualifies outright. If an auditor becomes disqualified after appointment, section 141(4) says the auditor must vacate office — and that vacancy is treated as a casual vacancy.
Before you appoint anyone, ask for two documents: a written consent to act as auditor, and a certificate confirming the appointment is within the limits of section 141. Every careful company secretary asks for both. The certificate is what protects you if the appointment is ever questioned.
When your auditor changes mid-term
Auditors leave. Death, disqualification or resignation creates what the Act calls a casual vacancy, and section 139(8) sets the clock: the Board must fill the vacancy within thirty days. If the vacancy arose from a resignation, the Board's choice must also be approved by the members at a general meeting held within three months of the Board's recommendation. The auditor appointed against a casual vacancy holds office only until the conclusion of the next AGM.
The resigning auditor has a duty of their own. Under section 140(2), the auditor who resigns must file a statement in Form ADT-3 with the company and the Registrar within thirty days of the resignation, giving the reasons and the relevant facts. The company files ADT-1 for the incoming auditor; the outgoing auditor files ADT-3. One does not substitute for the other. Our guide on what happens when your auditor resigns mid-year walks through the ADT-3 side in full.
Removing an auditor before the term ends is harder still: section 140(1) requires a special resolution and the previous approval of the Central Government. That is deliberate. An auditor who can be sacked by an ordinary vote is not independent in any meaningful sense.
Rotation: most private companies are exempt
Rotation sounds like everyone's problem. For most private limited companies, it is not. Section 139(2), read with Rule 5 of the Audit Rules, makes rotation compulsory only for listed companies and three classes of unlisted companies — and it expressly excludes One Person Companies and small companies.
| Company type | Rotation applies when |
|---|---|
| Unlisted public company | Paid-up share capital of ₹10 crore or more |
| Private limited company | Paid-up share capital of ₹50 crore or more |
| Any company (below those capital limits) | Public borrowings from banks or financial institutions, or public deposits, of ₹50 crore or more |
Where rotation does apply, an individual auditor may serve one term of five consecutive years and an audit firm two terms of five years — ten years in all — followed by a five-year cooling-off period before re-appointment in the same company. Below those thresholds, your auditor can be re-appointed for further five-year blocks without a cooling-off period.
The point worth carrying into your planning is the quiet one. A private company does not need to be large to cross the ₹50 crore borrowings test — a term loan and a working-capital facility can get there while the paid-up capital is still small. Check the test every year as you grow; the rotation duty arrives without a reminder.
What a late ADT-1 actually costs
ADT-1 is a small filing, and its late fees are built to sting in multiples, not in rupees. The normal fee itself is a few hundred rupees, set by your authorised capital under the Companies (Registration Offices and Fees) Rules, 2014. The additional fee for delay is a multiple of that normal fee, under the table substituted by G.S.R. 12(E) with effect from 1 July 2022:
| Delay in filing ADT-1 | Additional fee |
|---|---|
| Up to 15 days | 1 time the normal fee |
| More than 15 days, up to 30 days | 2 times the normal fee |
| More than 30 days, up to 60 days | 4 times the normal fee |
| More than 60 days, up to 90 days | 6 times the normal fee |
| More than 90 days, up to 180 days | 10 times the normal fee |
| Beyond 180 days | 12 times the normal fee |
Work it through. Say the normal fee for your company is ₹500. File 45 days late and the additional fee is four times the normal fee — ₹2,000 — so the filing costs ₹2,500 in all. File more than six months late and the additional fee is twelve times — ₹6,000 on top of the ₹500. The numbers are small in absolute terms, and that is exactly why companies let them slide. The real cost is not the fee. It is the AOC-4 validation failing a year later, the SRN missing from your records, and the annual filing held up while you explain a form that should have taken fifteen minutes.
Then there is the penalty for not appointing an auditor at all. Section 147(1) punishes a contravention of sections 139 to 146 with a fine on the company of not less than ₹25,000 and up to ₹5,00,000, and a fine on every officer in default of not less than ₹10,000 and up to ₹1,00,000. The imprisonment that once applied to officers in default was omitted by the Companies (Amendment) Act, 2020, with effect from 21 December 2020 — but the fines stand, and they apply per contravention.
Every deadline in this appointment, in one place:
| Event | Deadline | Source |
|---|---|---|
| Board appoints first auditor | Within 30 days of registration | Section 139(6) |
| Members appoint first auditor (if Board fails) | At an EGM within 90 days | Section 139(6) |
| File ADT-1 after any appointment | Within 15 days of the meeting | Fourth proviso to section 139(1); Rule 4(2) |
| First AGM | Within 9 months of close of first financial year | Section 96(1) |
| Five-year term at first AGM | Conclusion of first AGM to conclusion of sixth AGM | Section 139(1) |
| Board fills a casual vacancy | Within 30 days | Section 139(8) |
| Members approve a resignation vacancy | General meeting within 3 months of Board's recommendation | Section 139(8) |
| Resigning auditor files ADT-3 | Within 30 days of resignation | Section 140(2) |
The appointment, step by step
For a first auditor, the sequence is short. First, pick an eligible auditor and get the written consent and the section 141 eligibility certificate — before the Board meeting, not after. Second, hold the Board meeting within the thirty days and pass the resolution appointing the auditor. Third, send the auditor the intimation letter recording the appointment. Fourth, file Form ADT-1 on the MCA V3 portal within fifteen days of the Board meeting, choosing "First Auditor by Board of Directors" as the nature of appointment, attaching the certified resolution and the consent and certificate, and signing with a director's DSC. Fifth, keep the SRN. It is the proof of filing, and the AOC-4 will ask for it.
For the AGM appointment, the same shape holds with one difference: the appointment is made by the members by ordinary resolution at the AGM, and the fifteen days run from the AGM. If your company is close to a rotation threshold, check it before the AGM — appointing an auditor who must rotate out next year wastes everyone's time.
Five mistakes that cost companies money
Treating the first auditor as optional. Some founders file nothing for the first auditor because "the form didn't exist before". It exists now, and the AOC-4 will look for its SRN.
Counting the thirty days from the wrong date. The clock runs from the date of registration — the date on the certificate of incorporation — not from the date you receive the certificate or open the bank account.
Appointing a friend who cannot act. A relative of a director, a CA who owes the company money, a firm already auditing twenty companies — check section 141 before the resolution, not after the ROC raises it.
Letting a resignation drift. An auditor resigns, the Board moves on, and nobody files anything. Three clocks run at once: thirty days for the ADT-3, thirty days for the Board to fill the vacancy, three months for the members to approve. All three are easy to miss together.
Forgetting the ₹50 crore tests. Rotation does not apply to most private companies — until borrowings cross ₹50 crore and it suddenly does. A growing company should check the test every year, not discover it at the AGM.
Frequently asked questions
Who appoints the first auditor of a private limited company?
The Board of Directors, within 30 days of the company's registration, under section 139(6) of the Companies Act, 2013. If the Board fails, it must inform the members, who appoint the auditor at an extraordinary general meeting within 90 days.
Is filing Form ADT-1 mandatory for the first auditor?
The revised form, effective 14 July 2025, carries a first-auditor option and the MCA portal expects the filing — but the rule that creates the duty, Rule 4(2), was never amended to cover section 139(6), and ICSI has asked MCA to clarify. File it anyway: the portal and the AOC-4 SRN check make skipping it costlier than filing.
How long does the first auditor hold office?
Until the conclusion of the first AGM. At that meeting the members appoint an auditor for five years, holding office from the conclusion of the first AGM until the conclusion of the sixth AGM.
Can a private limited company appoint any Chartered Accountant as auditor?
Only a Chartered Accountant in practice — or a firm or LLP whose majority of partners practising in India are Chartered Accountants. Section 141 disqualifies officers and employees of the company, relatives of directors, anyone the company is owed more than ₹5 lakh by, and anyone who has given a guarantee above ₹1 lakh, among others.
What happens if the auditor resigns in the middle of the year?
The resigning auditor files Form ADT-3 within 30 days of resigning. The Board fills the casual vacancy within 30 days, and because the vacancy arose from a resignation, the members must approve the appointment at a general meeting within three months of the Board's recommendation. The new auditor holds office until the next AGM.
What is the penalty for not filing ADT-1 on time?
The additional fee rises in multiples of the normal fee — 1 time up to 15 days late, 2 times up to 30 days, 4 times up to 60 days, 6 times up to 90 days, 10 times up to 180 days, and 12 times beyond 180 days. Separately, section 147 fines a company ₹25,000 to ₹5,00,000 and officers in default ₹10,000 to ₹1,00,000 for contravening the auditor-appointment provisions.
Appointing an auditor is the first compliance a new company owes, and it is also the simplest — a Board resolution, a consent letter, and a fifteen-minute filing. Put the thirty-day date in the diary on the day of incorporation, alongside the private limited company registration itself. If you are working through your annual filing of a private limited company, the auditor's appointment is where that calendar starts. LLPs reading this should note that auditor appointment in an LLP follows different rules, and OPCs have their own relaxations in our OPC annual compliance guide. If the thirty days have already passed, do not wait for the AGM — call the Board, inform the members, and start the EGM route now. And if you want the dates tracked for you, our compliance fee calculator and the first annual filing guide carry the rest of the year's deadlines.

Comments
No comments yet — ask the first question below.
Join the discussion
Questions go straight to our expert desk. Comments appear after a quick review — no spam, no noise.