
IN BRIEF
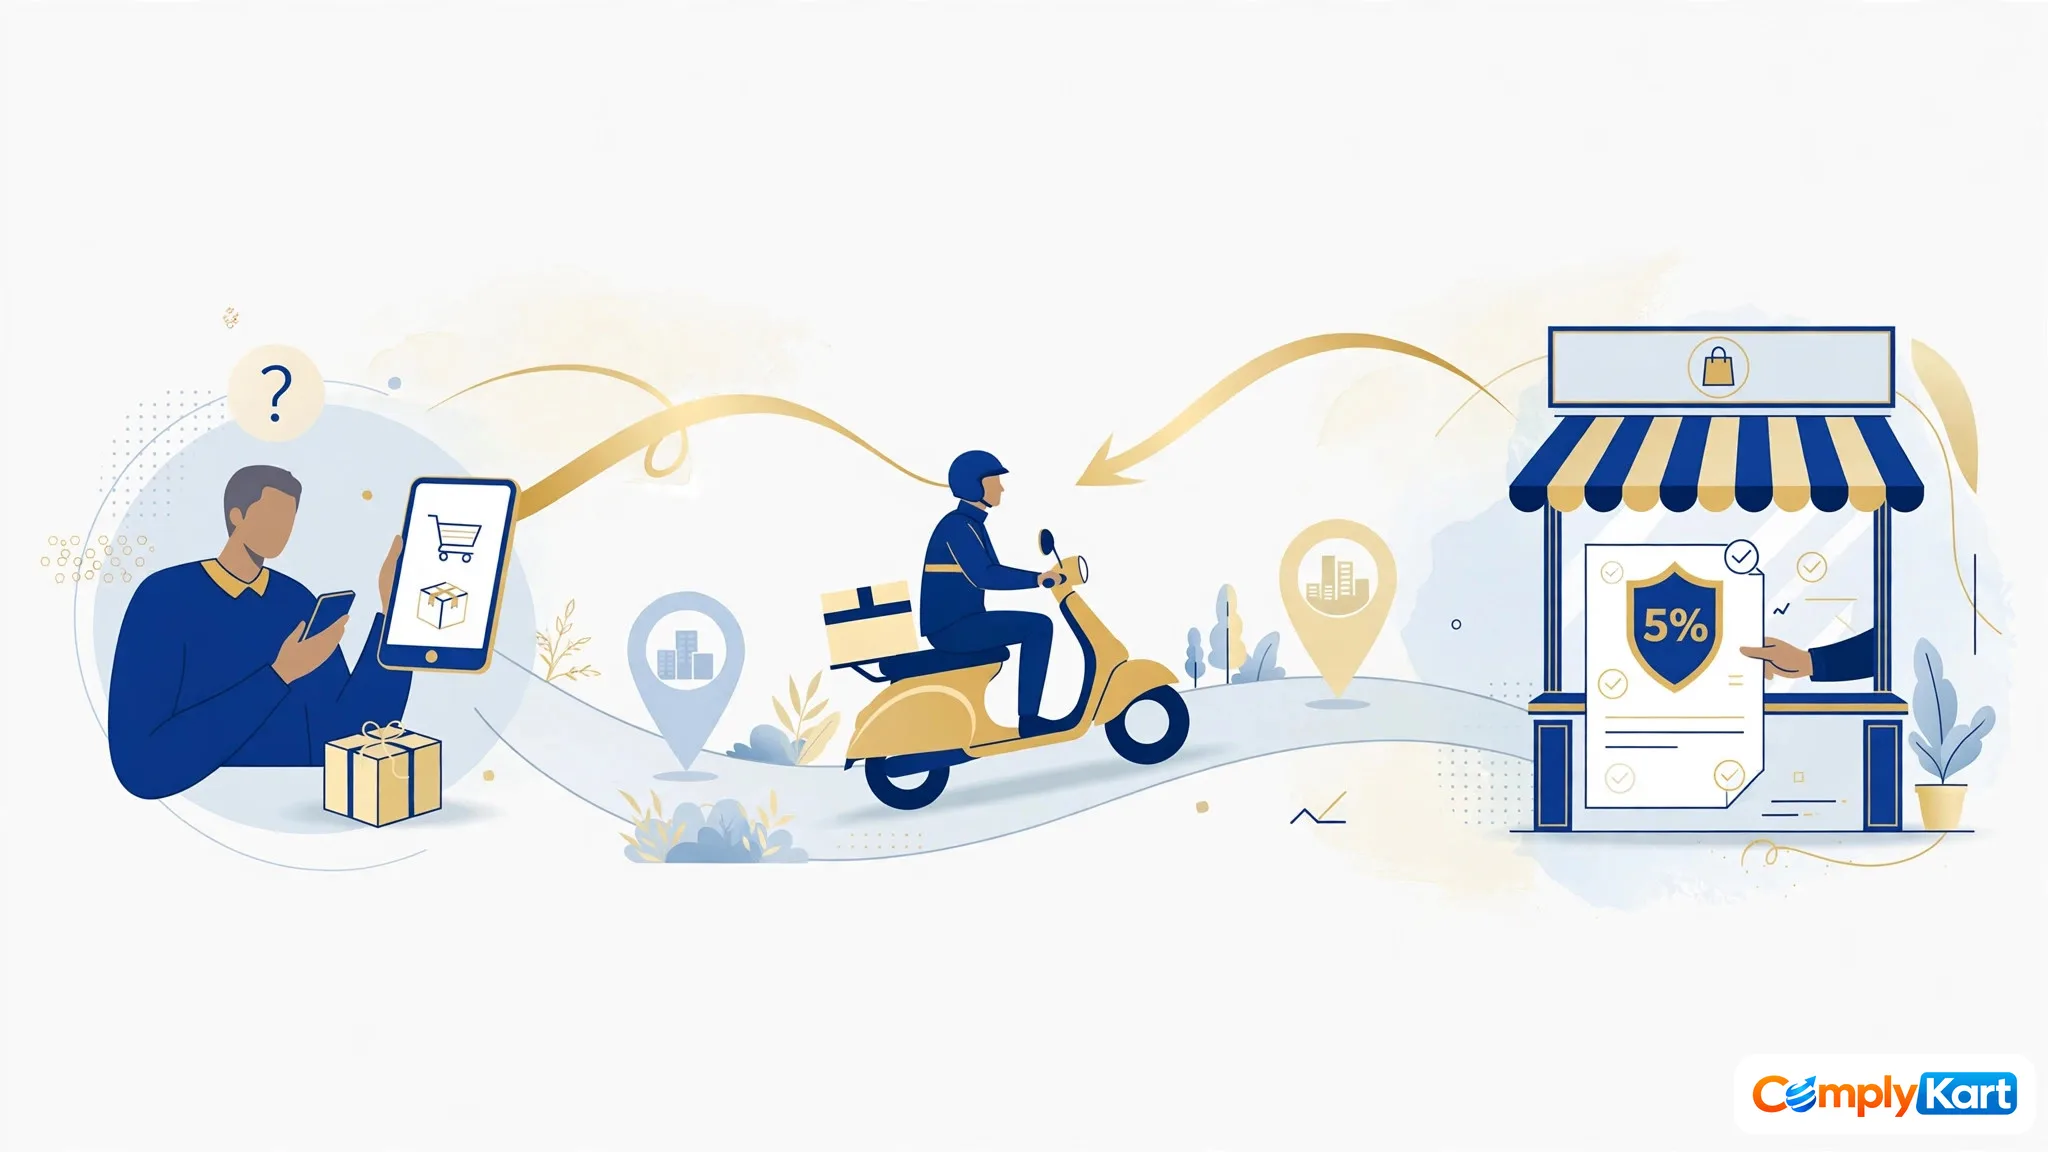
GST on e-commerce delivery services is the tax on the delivery leg of a platform order, not on the goods themselves. From 1 November 2026, such deliveries — other than postal and courier services — are taxed at 5% without input tax credit under section 9(5) of the CGST Act, 2017, paid by the platform where the partner is unregistered and by the partner itself where it is.
Tomorrow, 1 November 2026, the GST on deliveries arranged through an online platform changes. The rate drops from 18% to 5%, the credit goes away, and the word "local" disappears from the rule. If you run a platform, sell through one, or run a delivery fleet, this is the one change you need to understand before your billing system rolls over to November.
Short answer: From 1 November 2026, delivery services supplied through an e-commerce operator — other than postal and courier services — carry GST at 5% with no input tax credit. If the delivery partner is not liable for GST registration, the platform pays the tax under section 9(5) of the CGST Act. If the partner is registered, the partner pays it.
What exactly changes on 1 November?
Three things change at once: the scope, the rate, and the credit. All three come from two notifications dated 27 October 2026, issued on the 57th GST Council's recommendation. Notification No. 09/2026–Central Tax (Rate) rewrites the entry. Notification No. 06/2026–Central Tax (Rate) sets the new rate. Matching notifications under the IGST and UT GST laws carry the same change across state lines.
The old entry, in force since 22 September 2025, covered "services by way of local delivery" supplied through an e-commerce operator, where the person supplying the service was not liable for registration. It was taxed at 18% with input tax credit. The word "local" was never defined, and that single word caused months of argument about inter-city deliveries arranged through platforms. The new entry settles it.
| Point | 22 September 2025 – 31 October 2026 | From 1 November 2026 |
|---|---|---|
| Scope | "Local delivery" through an e-commerce operator | "Delivery services" through an e-commerce operator — any distance |
| Rate | 18% (9% CGST + 9% SGST) | 5% (2.5% CGST + 2.5% SGST; 5% IGST) |
| Input tax credit | Available | Not available |
| Who pays (unregistered partner) | Platform, under section 9(5) | Platform, under section 9(5) |
| Who pays (registered partner) | Partner itself | Partner itself, at 5% without credit |
One myth first, because it flooded social media in October. This is not a brand-new tax on your delivery fee. Deliveries through platforms were already taxed — at 18% since 22 September 2025. The tax department's fact-check unit called the "new 5% tax" posts false on that exact ground. What changes tomorrow is the rate, the scope, and the credit — not the existence of the tax. Delivery is one of several changes landing on 1 November; the discount and provisional-refund changes are covered separately.
Who pays — the platform or the delivery partner?
This is the question that decides your invoicing, so here is the rule in full. Section 9(5) of the CGST Act lets the government name services where the e-commerce operator pays the tax "as if the operator were the supplier". Delivery services are one such named category. The new entry reads, in full: "Delivery services, other than postal and courier services, except where the person supplying such services through electronic commerce operator is liable for registration under sub-section (1) of section 22 of the Central Goods and Services Tax Act, 2017."
That one sentence splits every delivery into two cases.
Case 1: the delivery partner is not liable for registration. This is the typical gig partner, below the GST registration threshold. The platform pays the 5% under section 9(5). The platform invoices the delivery charge to the customer as supplier, and discharges the tax on it. The partner files nothing extra for that delivery.
Case 2: the delivery partner is liable for registration. A fleet company or logistics firm above the threshold pays the 5% itself, without input tax credit, on deliveries it makes through the platform. The platform does not pay under section 9(5) for those deliveries. It collects tax collected at source under section 52 on them instead, as it does for other supplies by registered sellers on its platform.
Think of it like a mandi commission agent. A small farmer too small to register cannot pay the market fee himself, so the agent who sells his produce pays it on his behalf. A big trader with his own registration pays his own fee. Section 9(5) works the same way — the platform steps into the shoes of the partner who is too small to be in the tax net, and steps back out the moment the partner is big enough to stand in it.
One loose end remains. The Council also recommended amending section 9(5) itself, to make the platform's liability clear whatever business model it follows. That amendment needs a Finance Bill, so it has not happened yet. The notifications are the law from tomorrow; the section amendment is still to come.
What counts as a delivery service now — and what does not?
The wider wording covers intra-city and inter-city delivery alike: parcels, documents, food, groceries and other goods arranged through a platform. A Delhi-to-Jaipur parcel booked through a platform, which sat in a grey zone under the "local" wording, is plainly inside the new entry.
Two exclusions matter. Postal services and courier services are expressly outside the entry. A courier company keeps paying tax on its own supplies at 18% with full input tax credit, even when the booking came through an aggregator platform. If your "platform delivery" is really a courier booking, tomorrow's 5% rate does not touch it.
Food delivery through a platform sits inside the entry for the delivery leg. Keep the two legs apart in your head: the food itself is taxed under the restaurant-service entry, and the delivery of that food is taxed under this entry. They are two supplies with two rates, and mixing them up is how platforms misconfigure their billing.
Deliveries by your own staff or your own vehicles, not arranged through an e-commerce operator, are outside section 9(5) altogether. The platform rule only bites where the supply runs through a platform. Your own fleet's tax position follows the ordinary rules for your own supplies.
The maths: will your delivery bill actually fall?
On headline tax, yes. On real cost, it depends on your input mix. Work through one illustration — my own numbers, not a real company's books.
Take a delivery charge of ₹100. Until today, the GST on it was ₹18, and the person paying it could set input tax credit against it — credit on vehicles, fuel, maintenance, software, all the inputs that go into running deliveries. From tomorrow, the GST is ₹5, and that credit is gone. The headline tax falls by ₹13 on every ₹100 of delivery charge.
Scale it up. A platform collecting ₹10 lakh of delivery charges in a month paid ₹1,80,000 of GST on them at 18%. From November it pays ₹50,000 at 5%. That is a ₹1,30,000 headline saving — before counting the credit it can no longer take.
That last line is the catch. A fleet-heavy operator with a large credit pool on vehicles and fuel loses more credit than a gig model with almost no inputs. For the gig model, the saving is close to the full headline figure. For the fleet model, part of it evaporates. And nothing in the notifications forces any platform to cut the delivery fee it charges you. The tax falls; whether your delivery fee falls is the platform's pricing decision, not a legal one. You can run your own delivery volumes through the compliance fee calculator to see the headline difference for your business.
What platforms must change before 1 November
If you run a platform, tonight's checklist is short and unforgiving. Miss one item and your November invoices carry the wrong rate.
- Reconfigure the rate: 18% with credit becomes 5% without credit for platform delivery services, from time of supply on or after 1 November 2026.
- Reconfigure the scope: every distance counts now, not just local runs. Inter-city platform deliveries move into the entry.
- Check every partner's registration position: liable for registration under section 22(1) or not decides whether you pay under section 9(5) or the partner pays and you collect tax collected at source.
- Invoice delivery charges as supplier for your section 9(5) supplies, report them in the section 9(5) row of Table 3.1 of GSTR-3B, and in Tables 14 and 15 of GSTR-1 as applicable.
- Ring-fence the credit: inputs used for 5% delivery supplies carry no credit now. Your vehicle, fuel and maintenance credits need a new home in your workings, or they will leak into returns where they do not belong.
- Keep courier bookings on their own track at 18% with credit — do not let the new 5% configuration swallow them.
What sellers and restaurants should watch
If you sell through a platform, you do not pay this tax directly when the platform pays under section 9(5). Your job is to watch three things. First, the delivery-fee lines on your platform statements from November — the tax component should read 5%, not 18%. Second, your own invoices: do not add delivery GST on top of a delivery the platform already taxed. Third, if you run your own registered fleet on a platform, remember you are now the payer at 5% without credit, with tax collected at source applying on top — your invoicing and your credit workings both change. This delivery change is separate from the simplified registration route for online sellers, which deals with getting registered, not with the delivery rate.
Restaurants, one specific warning. Your food delivery through an aggregator is inside this entry for the delivery leg, but your restaurant service is not. If your aggregator statement ever merges the two into one line, ask for the split. A merged line hides errors in both rates.
Nasscom asked for more time — plan for 1 November anyway
On 28 October 2026, Nasscom wrote to the Finance Ministry asking for the new framework to be deferred to 1 January 2027, with an industry consultation first. Its case is practical: platforms and logistics firms got the notifications on 27 October and must rebuild billing, accounting and tax systems for 1 November. That is four days over a festival-season weekend, and the industry body says it is not enough time to test the changes.
As this post is published, no deferral has been notified. A representation is a request, not a change in law. If the government does defer, it will need a notification to do it, and this post will need an update. Until then, the only safe plan is 1 November. Build for the notified date; treat a deferral, if it comes, as a bonus.
Five mistakes to avoid
- Calling the 5% a new tax — it replaces an 18% tax that has applied since 22 September 2025.
- Applying 5% to courier deliveries — postal and courier services are expressly excluded.
- Assuming the platform always pays — a registered delivery partner pays its own 5%, and the platform collects tax collected at source instead.
- Leaving the billing system at 18% past 1 November — the rate change follows time of supply, so November supplies at the old rate are wrong from day one.
- Forgetting the credit — inputs for 5% delivery supplies carry no credit, and old credit workings will overstate what you can claim.
Frequently asked questions
Does the 5% rate apply to courier deliveries booked through an app? No. Postal and courier services are expressly excluded from the new entry. Courier companies continue to pay 18% with full input tax credit on their own supplies, even when the booking came through a platform.
I am a small seller on a marketplace. Do I file anything extra for delivery GST? No, not for deliveries by unregistered partners — the platform pays under section 9(5) and invoices the delivery charge as supplier. Your filings cover your own supplies, as before. Check your platform statements from November for the 5% delivery line.
Will delivery fees on food and grocery apps fall from 1 November? The tax on the delivery leg falls from 18% to 5%, but the fee you see is the platform's price, not just its tax. Platforms also lose input tax credit on delivery inputs. Some of the saving may reach you; none of it is guaranteed by the notifications.
My delivery fleet is GST-registered and works through platforms. What changes for me? You pay 5% without input tax credit on your platform deliveries from 1 November, instead of 18% with credit. The platform does not pay under section 9(5) for your deliveries, but it collects tax collected at source under section 52 on them. Rework both your invoicing and your credit position before November billing starts.
What happens if Nasscom's deferral request succeeds? A deferral would need a fresh notification moving the effective date, and platforms would keep the old 18% treatment until the new date. Until such a notification appears, 1 November 2026 stands. Watch for it, but do not bill on the assumption of it.
Sources for the key facts in this post: Notification No. 09/2026–Central Tax (Rate) dated 27 October 2026, Notification No. 06/2026–Central Tax (Rate) dated 27 October 2026, the 57th GST Council's recommendations, and the 28–30 October 2026 coverage of Nasscom's representation. If a deferral notification appears, this guide will be updated to match it.

Comments
No comments yet — ask the first question below.
Join the discussion
Questions go straight to our expert desk. Comments appear after a quick review — no spam, no noise.