
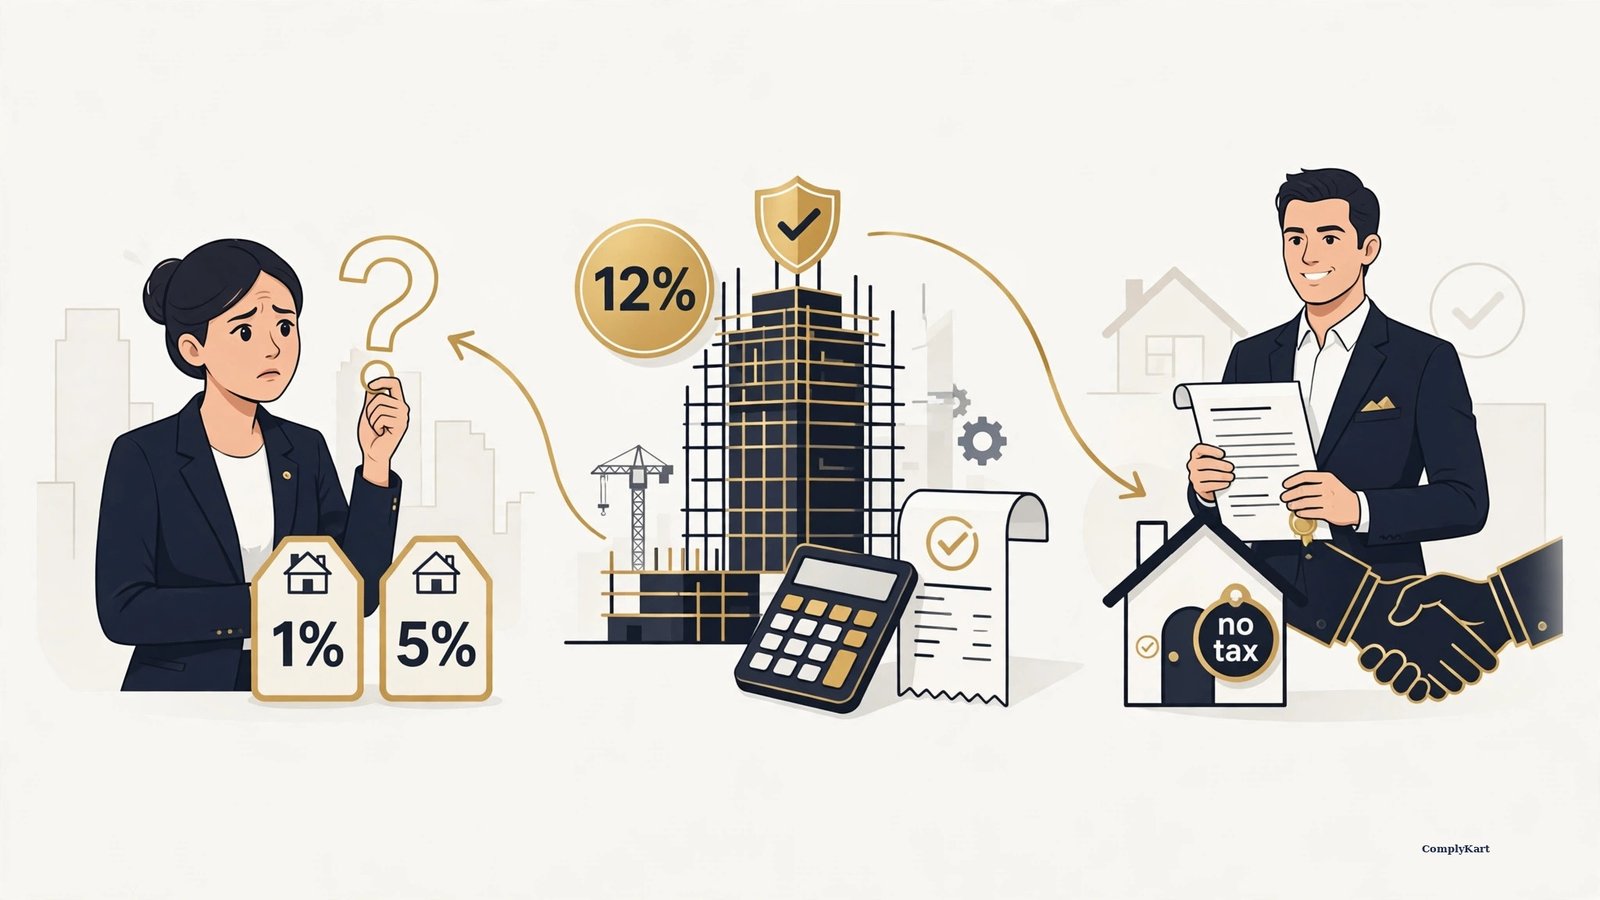
If you develop and sell flats under construction, GST is not a footnote on your cost sheet — it is the line item most developers get wrong, and the costliest to fix. Builders charge 5% on shop units that should be 12%; luxury-tower developers pay 5% on full consideration while their land cost is 70% of the deal. The rules date to April 2019, the arithmetic is simple, and the mistakes are almost always the same five.
The short answer: Under-construction residential units attract 1% GST for affordable housing (up to ₹45 lakh and 60/90 sqm carpet) or 5% for other residential — both with no input tax credit. Commercial units in a Residential Real Estate Project (RREP) are 5% without ITC; in a purely commercial project they are 12% effective with ITC. Sale of land and ready-to-move flats are outside GST entirely.
Which GST rate does your project charge?
The rate depends on what you are selling, not on the project's brand or city. Three buckets cover almost everything (Notifications 03/2019 and 04/2019-Central Tax (Rate), effective 1 April 2019).
Affordable residential — 1%, no ITC. Two hard conditions must both be met: agreement value up to ₹45 lakh, and carpet area up to 60 sqm in metros (Delhi NCR, Mumbai MMR, Chennai, Kolkata, Hyderabad, Bengaluru) or 90 sqm in non-metros. Miss either and you are in the next bucket.
Other residential — 5%, no ITC. Every other under-construction flat. The headline looks cheap, but here is the catch: no input tax credit. GST on cement, steel, contractor bills, and professional services is a sunk cost — baked into the price, never reclaimed.
Commercial — it depends on the project type. Shops and offices inside a Residential Real Estate Project (RREP) get 5% without ITC. In a commercial-only project — an office tower, a mall — the effective rate is 12% with ITC. Which type your project is, is the most misunderstood question in developer GST.
Is your project an RREP or an REP — and why does it matter?
A Residential Real Estate Project (RREP) keeps commercial carpet area at or below 15% of total carpet area. Cross that line — even by a fraction — and the project is a plain Real Estate Project (REP), where commercial units shift to 12% with ITC.
Think of it like a cricket team's overseas-player cap. Four overseas players in the XI is fine; name five and the whole selection is invalid. The 15% commercial-carpet cap works the same way.
Measure carpet area project-wise at inception, document it, and re-check before converting a residential tower to commercial mid-construction. One extra shop can reclassify the project's commercial units from 5%-no-ITC to 12%-with-ITC, and the differential plus interest lands on you.
What counts as \"affordable\" — and what kills the 1% rate?
Three things, all from the registered agreement: value (≤ ₹45 lakh, inclusive of everything except stamp duty and registration), carpet area (≤ 60 sqm metro, ≤ 90 sqm non-metro), and the unit must be residential. A ₹44-lakh flat with 62 sqm carpet in Mumbai is 5%, not 1%.
Watch the quiet killers: preferential location charges, clubhouse and parking fees bundled into the agreement value push the total over ₹45 lakh; balcony areas counted wrongly against carpet. Verify the declared carpet area on the registered agreement before fixing the rate on your invoice.
ITC: what you lose, what you keep, what you reverse
On the 1% and 5% residential rates, input tax credit is simply unavailable — that is the condition of the concessional rate. GST on cement, steel, contractor bills, and architect fees becomes project cost. Price accordingly.
Where credits exist, they need surgery, not just addition. Common credits — site office costs, shared services, head-office overhead — must be apportioned under Rules 42 and 43 of the CGST Rules. And Section 17(5)(d) blocks ITC on construction of immovable property for your own account — ITC on a commercial tower you retain and rent out is a fight you will probably lose.
The rule developers underestimate most: under Section 9(4), at least 80% of a project's procurement must come from GST-registered dealers, or you pay reverse charge at 18% on the shortfall — with no credit. On a ₹200-crore project, a 10% shortfall means 18% on ₹10 crore: ₹1.8 crore out of pocket. Run the 80% check monthly, not at project end.
The land deduction — and where the maths breaks
GST applies to the construction service, not to land. Since land value is rarely separated in agreements, the valuation rule treats one-third of the total amount (including land) as land value, taxing the remaining two-thirds. That is how 7.5% statutory becomes the 5% effective rate.
But the rule assumes land is a third of the deal. In premium localities — South Mumbai, Adyar, Alipore — land can be 60–70% of the consideration while GST is charged as if it were 33%. The buyer effectively pays GST on land value, and with no ITC on the residential rate, the excess sticks.
Development agreements: the tax event hiding in the JDA
In a joint development agreement, the developer's construction service to the landowner is taxable — GST applies on the landowner's share of flats when flats are handed over or the completion certificate arrives, whichever is earlier. If the landowner sells those flats before completion, GST applies again (1%/5% as applicable). After the completion certificate, the sale is immovable property under Schedule III — no GST at all. Completion certificates are tax events, not just regulatory ones.
Mistakes that cost developers real money
- Charging 5% on commercial units in a commercial tower. Outside an RREP, commercial is 12% with ITC — the shortfall compounds with interest.
- Ignoring the 15% commercial-carpet threshold. Measure before you sell; one extra shop reclassifies the project.
- Assuming affordable on area or price alone. ₹45 lakh AND 60/90 sqm, both conditions, on the registered agreement.
- Claiming ITC on the 1%/5% rates. Rate and credit are mutually exclusive — treat embedded input GST as project cost from day one.
- Letting registered procurement slip under 80%. Section 9(4) reverse charge at 18% has no credit against it — monitor monthly.
- Forgetting the developer-to-landowner supply in a JDA. Construction service to the landowner is taxable; price it in, don't litigate later.
For the filing and reconciliation side, a compliance fee calculator estimates the full compliance cost around your project, and our GST registration service covers new projects from the first agreement. For the restaurant world's mirror image of this problem, see GST for restaurants: 5% vs 18%, and for October 2026's enforcement-side changes, the 57th Council's decriminalisation drive.
FAQs
Does GST apply to ready-to-move-in flats?
No. Once a completion certificate is issued, the sale is of immovable property under Schedule III of the CGST Act — outside GST. Only stamp duty and registration apply.
Can a developer choose the old 12%-with-ITC scheme?
Only for projects ongoing on 31 March 2019, and the one-time option had to be exercised then. New and post-2019 projects use the 1%/5%/12% structure above.
What GST applies to parking and preferential location charges?
Independent car parking and PLC with an under-construction flat attract 18% GST; maintenance above ₹7,500 per month per unit is also 18%.
Is the 57th GST Council changing real-estate rates?
Not yet. The 8 October 2026 recommendations covered arrest powers, prosecution thresholds, refunds, and return-correction mechanics — no real-estate rate change was announced. Nothing is notified.
Who pays GST in a joint development agreement?
The developer pays GST on construction services supplied to the landowner. If the landowner sells their share before the completion certificate, GST applies again. After the certificate, neither sale attracts GST.
Do I need GST registration before launching a project?
Yes — before the first taxable supply. RERA and GST registration are separate; neither substitutes for the other.

Comments
No comments yet — ask the first question below.
Join the discussion
Questions go straight to our expert desk. Comments appear after a quick review — no spam, no noise.