These are the GST law's numbers, not ours. The fee runs daily — but unlike ROC fees, it is capped.
Turnover up to ₹5 crore
₹50 per day
₹25 CGST + ₹25 SGST per day, capped at 0.04% of turnover in the State/UT (Notification 07/2023–Central Tax).
Turnover ₹5–20 crore
₹100 per day
₹50 CGST + ₹50 SGST per day, capped at 0.04% of turnover in the State/UT.
Turnover above ₹20 crore
₹200 per day
₹100 CGST + ₹100 SGST per day under Section 47(2), capped at 0.5% of turnover in the State/UT.
Due date
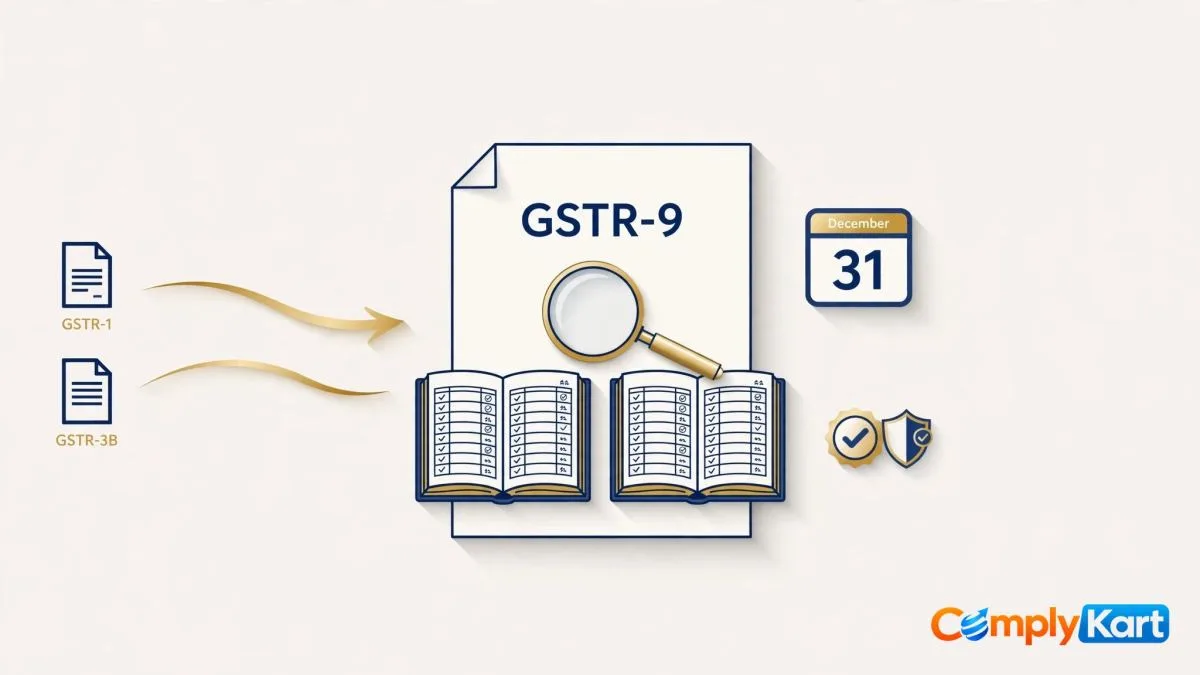
31 December
Of the year following the financial year (Section 44). Filing is optional only if turnover is up to ₹2 crore.
Put it in perspective: At ₹50–₹200 a day, one quarter's delay quietly becomes ₹4,500–₹18,000 — before the cap is even tested.
Free tool
Filing late? Price the delay before it grows
The GSTR-9 late fee runs per day and is capped as a share of your turnover — the exact bill depends on your turnover slab and how many days slip. Our calculator works it out state by state, and shows what waiting another month costs.
Five steps, no guesswork — you always know exactly what comes next. Tap a step to see what it involves.
12345
You pay securely. Payment is confirmed instantly, and your receipt with the written fee breakup lands in your inbox.
Overview
Twelve months of invoices, twelve GSTR-1s, twelve GSTR-3Bs — and then one return asking a simple question: does it all add up? GSTR-9, the annual return under Section 44 of the CGST Act, is the one filing where a business views its entire GST year as a single picture — nineteen tables forcing the year's monthly filings to reconcile with the books.
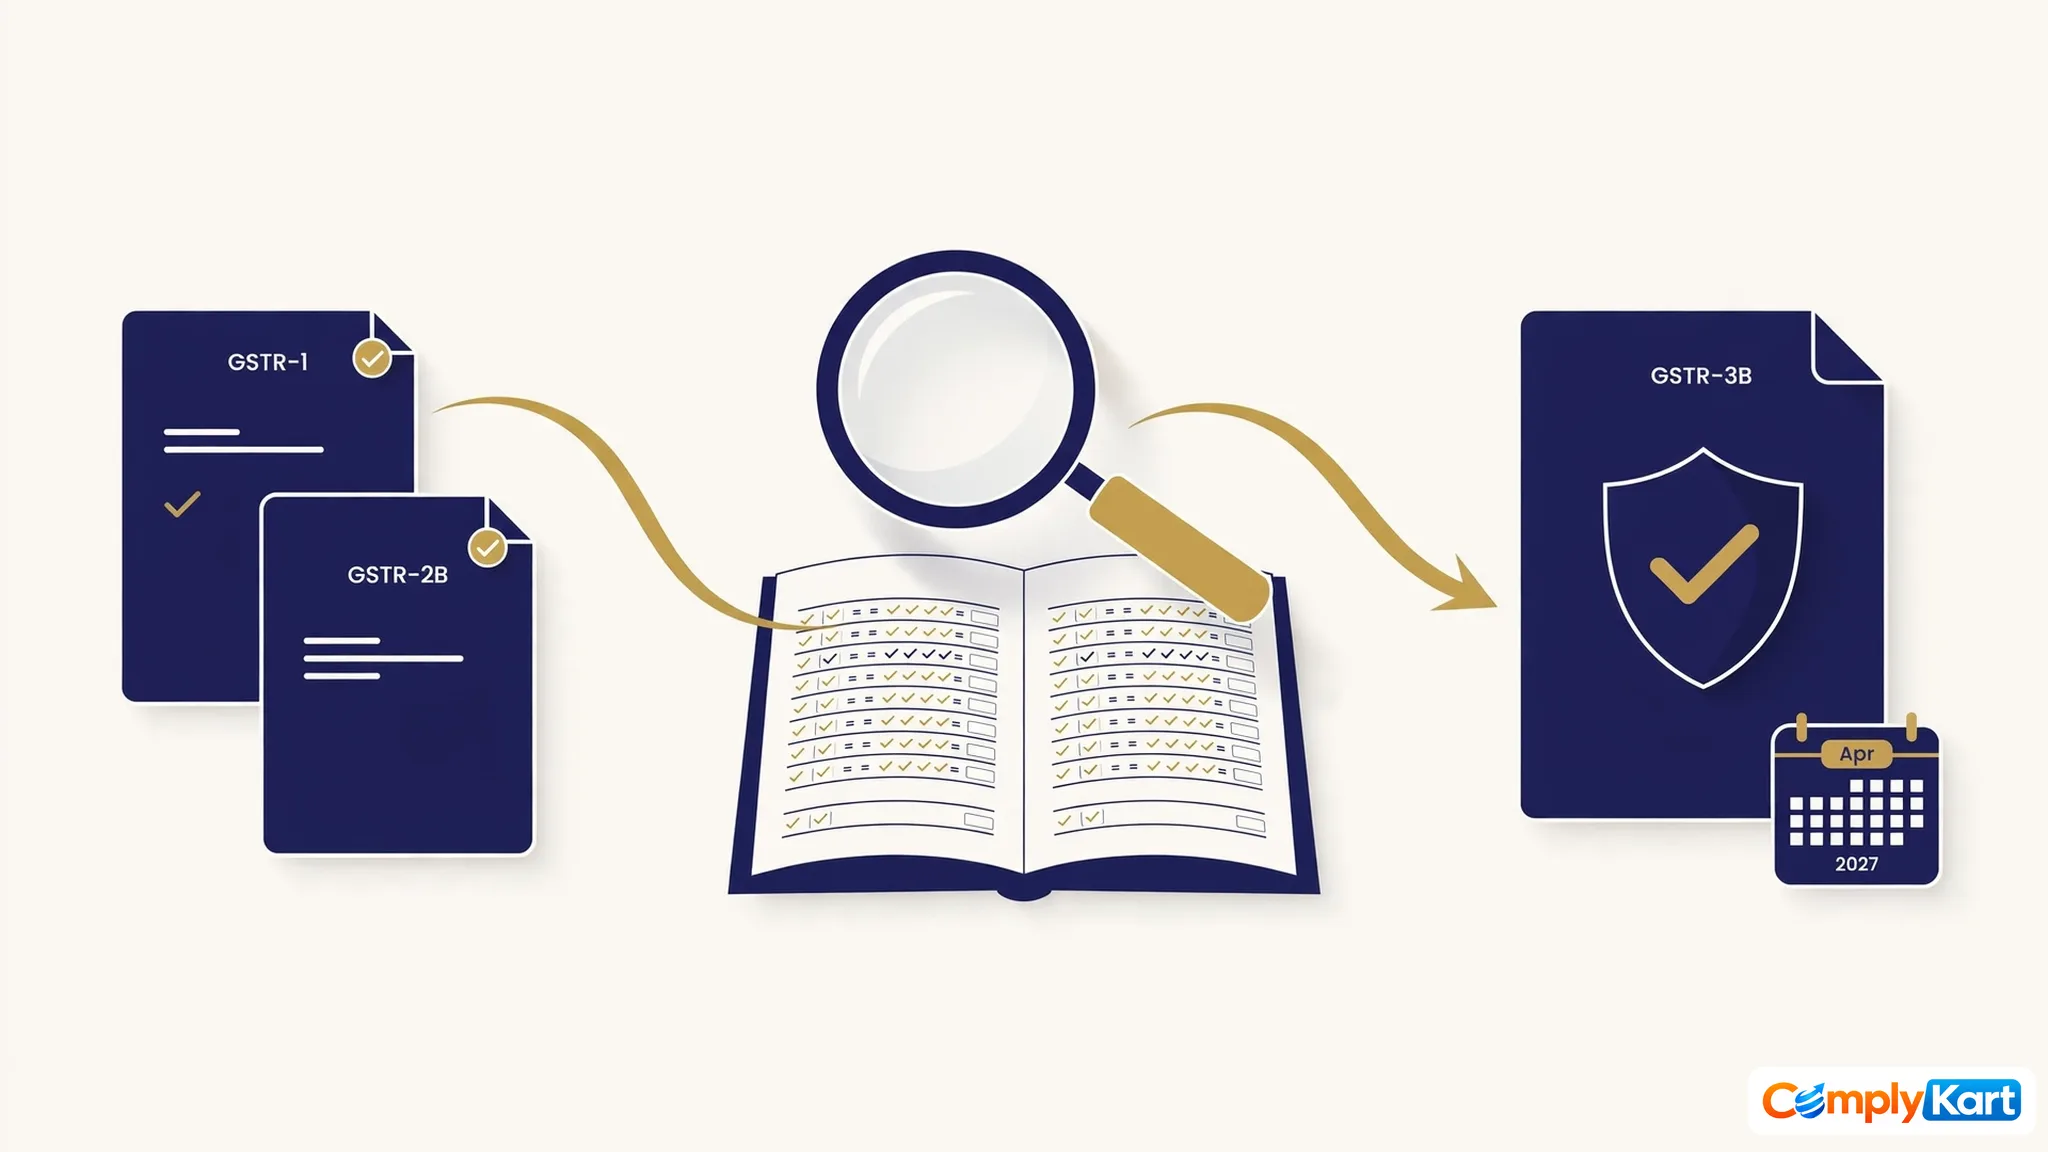
This is where the year's small discrepancies surface: a credit note booked in the wrong month, an invoice the supplier reported but the purchase ledger missed, input tax credit claimed in GSTR-3B that never appeared in GSTR-2B. Monthly returns let these pass; the annual return does not. It is a reconciliation discipline disguised as a return, and tax officers treat it that way — gaps between GSTR-9 and the books are the standard starting point for scrutiny notices.
This guide walks through the whole filing: who is caught by the ₹2 crore rule, the 31 December deadline, what goes into each of the nineteen tables, what changed for FY 2024-25, the late-fee math, and the preparation routine that keeps a filing clean.
Is GSTR-9 for You?
You must file GSTR-9 for a financial year if:
You are registered under GST as a regular taxpayer (not composition, not ISD, not a TDS/TCS deductor, not a casual or non-resident taxable person), and
Your aggregate turnover in that financial year exceeds ₹2 crore.
You should check carefully before concluding you are outside:
The turnover test is PAN-based, not GSTIN-based. Turnover across all your GST registrations under the same PAN is added up — a business with three state registrations at ₹80 lakh each crosses the ₹2 crore line.
If your aggregate turnover exceeds ₹2 crore, you must file GSTR-9 for *every* GSTIN under that PAN — including registrations that had no transactions during the year, for which a nil return is filed.
A registration cancelled during the year is not off the hook: if the turnover threshold was met, the annual return is still due for the period of registration.
You do not file GSTR-9 when:
Your aggregate turnover for the year is up to ₹2 crore — filing is optional from FY 2024-25 onwards.
You are a composition taxpayer (you file GSTR-9A instead), an Input Service Distributor, a TDS/TCS deductor, a casual taxable person, or a non-resident taxable person — each has its own form or exemption.
The ₹2 Crore Threshold — the Section That Decides Everything
The single most disputed question about GSTR-9 is also the simplest: does the ₹2 crore rule catch me? The answer turns on two words in Section 2(6) of the CGST Act — "aggregate turnover" — and a notification that reset the position from FY 2024-25.
Aggregate turnover means all taxable supplies, exempt supplies, exports and inter-state supplies of a person with the same PAN, computed pan-India, *excluding* GST taxes. Exempt and export turnover count: ₹1.5 crore of taxable sales plus ₹80 lakh of exports is ₹2.3 crore of aggregate turnover — the business files GSTR-9 even though taxable turnover alone is below the line.
The threshold itself was clarified by Notification 15/2025-Central Tax dated 17 September 2025: registered persons with aggregate turnover *up to* ₹2 crore in any financial year are exempted from filing the annual return under Section 44(1) from FY 2024-25 onwards. Below-or-at ₹2 crore, filing is optional; above ₹2 crore, it is mandatory. The word "exceeding" matters at the boundary — turnover of exactly ₹2 crore does not trigger the mandate.
Three edge cases that trap real businesses every year. First, the multi-GSTIN trap: the test aggregates across states, so businesses expand across state lines without realising the combined number has crossed. Second, the cancelled-registration trap: a GSTIN surrendered in October does not erase the April-to-October turnover from the test. Third, the voluntary-registration trap: a business that registered voluntarily with ₹50 lakh turnover and then grew past ₹2 crore during the year files for the full year, not just the months after crossing.
What Must Be Decided Before Filing
People: The person who owns the GST working — usually the accountant or the consultant — plus whoever can sign off the books: the proprietor, partner or authorised director. GSTR-9 figures must tie to the audited or final books, so the person who closed the books needs to be in the room.
Decisions: The reconciliation methodology — how you will match GSTR-1 vs books for outward supplies, GSTR-2B vs books for input tax credit, and GSTR-3B vs books for tax paid. Decide the materiality threshold below which small differences are accepted and documented. Decide who investigates the top five variances, because every filing has them.
Documents: All GSTR-1 and GSTR-3B filings with ARNs; purchase and sales registers; twelve months of GSTR-2B; debit and credit note registers; e-way bill data; the trial balance and final financial statements; and last year's GSTR-9 workings — recurring differences tend to repeat.
Why GSTR-9 Matters — Seven Things the Annual Return Actually Does
1. It closes the loop on twelve months of filings
Monthly returns are filed under time pressure, often with provisional figures. GSTR-9 is the one moment the law gives you to look at the year as a whole and confirm that what was declared month by month matches what the books say. Businesses that treat it as a formality miss the point — it is the annual true-up.
2. It forces the ITC reconciliation nobody does monthly
Table 6 (ITC availed), Table 7 (ITC reversed) and Table 8 (other ITC information) require the full year's credit position to be stated and reconciled with GSTR-2B. Credits claimed in 3B but missing from 2B, reversals under Rules 37 and 37A, reclaims — the annual return is where the credit ledger gets its audit.
3. It is the department's favourite starting point for scrutiny
Assessment officers routinely begin with three documents: GSTR-9, GSTR-9C (where applicable) and the financial statements. Unexplained differences between Table 4 and the sales register, or between Table 6 and the purchase register, are the standard trigger for a notice under Section 61 or an audit under Section 65.
4. It surfaces supplier-side problems while there is still time to act
When Table 8A (auto-populated from the Invoice Management System for FY 2024-25) shows invoices your suppliers reported that your books never recorded — or vice versa — you learn which vendors are filing inconsistently. That intelligence feeds directly into vendor management for the next year.
5. It captures previous-year transactions declared late
Tables 12 and 13 give previous-year transactions declared late their last legitimate home — missed invoices and credit notes land here.
6. It quantifies demands, refunds and advances in one place
Table 15 (demands and refunds), Tables 10/11 (advances) and Table 14 (differential tax) consolidate positions scattered across monthly filings — the cleanest statement of GST posture for businesses with litigation or refund claims.
7. It creates the base document for GSTR-9C
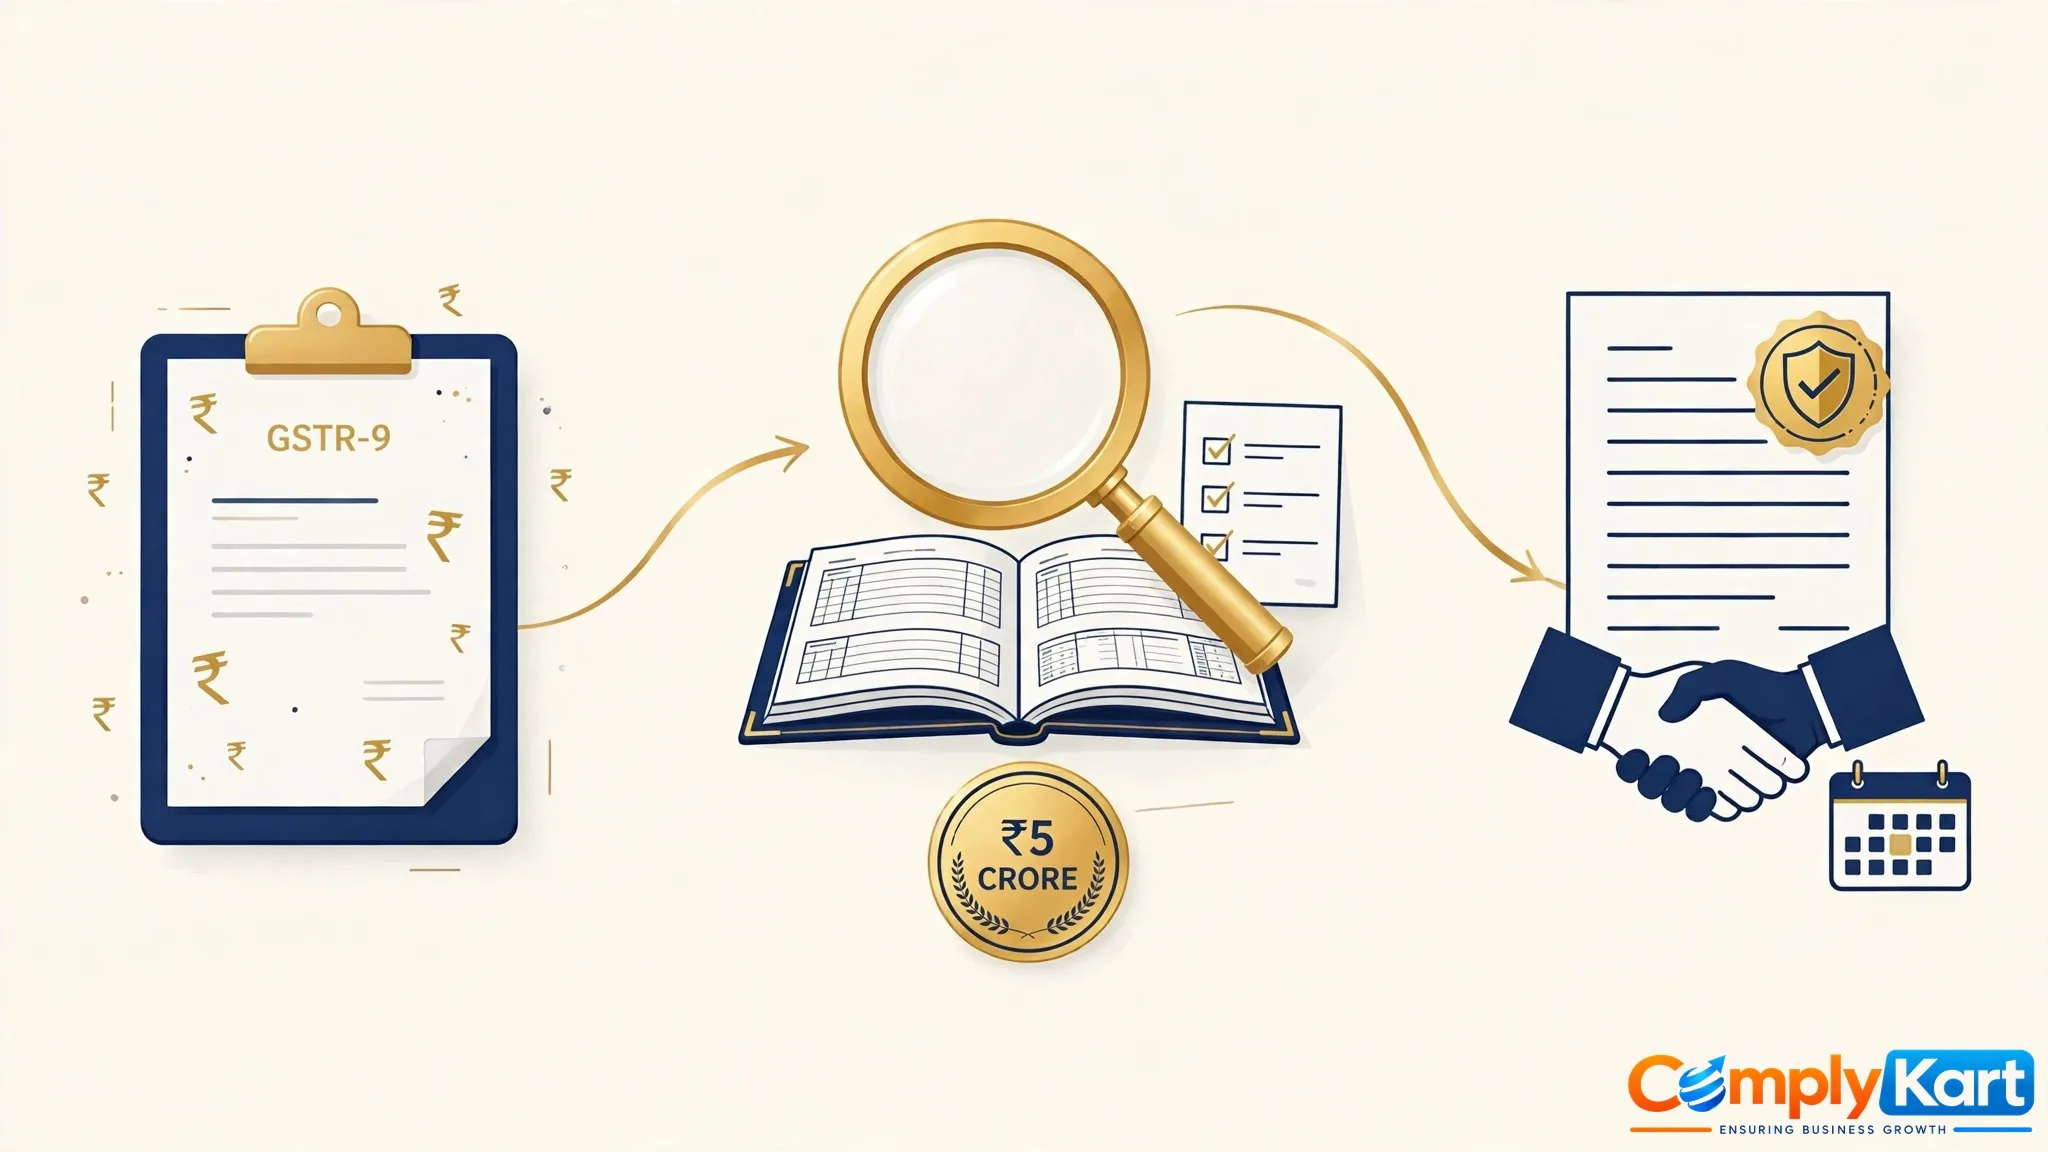
Where turnover exceeds ₹5 crore, the GSTR-9C reconciliation starts from the GSTR-9 figures. A sloppy GSTR-9 guarantees a painful 9C. Getting the annual return right is the cheapest way to keep the reconciliation statement short.
Documents Required
Identity and access: GST portal login credentials for the GSTIN; DSC or EVC of the authorised signatory for submission; the list of all GSTINs under the PAN with their registration and cancellation dates.
Filing records: Filed GSTR-1 and GSTR-3B for all twelve months (or quarters, for QRMP taxpayers) with ARN references; GSTR-2B for all twelve months; any GSTR-1A amendment filings; records of DRC-03 payments made during the year.
Books and registers: Sales register and purchase register for the financial year; debit note and credit note registers; e-way bill summaries; the trial balance, profit and loss account and balance sheet as finalised; HSN-wise summary of outward and inward supplies.
Reconciliation workings: The 3B-vs-books and 2B-vs-books reconciliation sheets; workings for ITC reversals under Rules 37, 37A, 42 and 43; details of demands paid, refunds received or claimed; and last year's GSTR-9 workings for comparison.
GSTR-9 Process — Step by Step
Step 1 — Confirm the obligation
Compute aggregate turnover for the PAN for the financial year, including exempt and export turnover. Confirm every GSTIN under the PAN and its active period. If the total exceeds ₹2 crore, every GSTIN files.
Step 2 — Close the monthly filings first
The portal will not open GSTR-9 until all GSTR-1 and GSTR-3B returns for the financial year are filed. Identify any missing or pending monthly returns and file them — this is the most common reason filings stall in December.
Step 3 — Pull the auto-populated data
On the GST portal, go to Services → Returns → Annual Return, select the financial year, and choose Prepare Online (or Prepare Offline using the GSTN utility). Tables 4, 5, 6, 7, 8A and 9 come pre-filled from filed returns — but auto-populated does not mean correct. Every figure must be checked against the books.
Step 4 — Reconcile outward supplies
Match Table 4 (outward taxable supplies) and Table 5 (exempt, nil-rated and non-GST supplies) against the sales register. Investigate differences: unreported invoices, credit notes booked late, advances adjusted, and GSTR-1A amendments that changed the auto-population.
Step 5 — Reconcile input tax credit
Work through Tables 6, 7 and 8 against the purchase register and GSTR-2B — the longest step. Segregate ITC availed, reversed under each rule, ineligible credit and credit reclaimed. For FY 2024-25, watch Table 8A (IMS-driven, document-date basis) and the new Table 6A1 for cross-year ITC.
Step 6 — Reconcile tax paid
Table 9 compares tax payable as declared in returns against tax actually paid in cash and through credit. Differences here usually trace to DRC-03 payments, interest or late-fee payments, or cash-ledger adjustments made during the year.
Step 7 — Complete the remaining tables
Fill Tables 10–19 from the workings: advances, previous-year transactions, differential tax, demands and refunds, composition-related information, and the HSN-wise summaries of outward (Table 17) and inward (Table 18) supplies. Table 19 captures late fee payable and paid.
Step 8 — Review, preview and submit
Preview the full return as the department will see it. Run a final variance check against the financial statements — unexplained gaps above materiality must be investigated, not filed. Submit with DSC or EVC and download the ARN.
Step 9 — Archive the workings
Save the filed return, the ARN, and the complete reconciliation working papers. These are the first documents an officer asks for in scrutiny, and reconstructing them a year later is far harder than filing them now.
The Table-Wise Walkthrough — All Nineteen Tables, in Plain Words
Part I — Basic details (Tables 1–3). GSTIN, legal and trade names, and the financial year. Pre-filled; verify the period, especially for registrations cancelled mid-year.
Part II — Outward and reverse-charge inward supplies (Table 4). The heart of the return. Table 4 breaks outward supplies into inter-state and intra-state taxable supplies, zero-rated supplies, deemed exports, advances and reverse-charge inward supplies, each with the tax breakup; Table 5 captures exempt, nil-rated and non-GST supplies. For FY 2024-25, GSTR-1A amendments auto-reflect in both.
Part III — Input tax credit (Tables 6–8). Table 6 states ITC availed during the year, split by inputs, input services and capital goods, plus the new Table 6A1 segregating cross-year ITC. Table 7 records ITC reversed and ineligible — including reversals under Rules 37 (non-payment to supplier within 180 days), 37A (supplier's non-filing), 42 and 43 (common credit attribution). Table 8 carries other ITC information: Table 8A is auto-populated (IMS-driven from FY 2024-25), 8B–8D reconcile availed, reversed and net credit.
Part IV — Tax paid (Table 9). Tax payable as declared in returns versus tax actually paid, split across CGST, SGST, IGST and cess, in cash and through credit. Additional tax discovered at this stage is paid via Form DRC-03 — and can now be paid using input tax credit.
Part V — Other information (Tables 10–16). Advances on outward and inward supplies (Table 11); supplies received from composition taxpayers, deemed supplies under Section 143 and goods sent on approval basis (Tables 10 and 16); previous-financial-year transactions declared late (Tables 12–13); differential tax paid on account of Tables 10 and 11 (Table 14); demands and refunds — including refunds claimed, sanctioned, rejected and pending (Table 15).
Part VI — HSN summaries and late fee (Tables 17–19). Table 17 is the HSN-wise summary of outward supplies and Table 18 of inward supplies — for FY 2024-25, HSN cross-verification is enforced for turnovers above ₹5 crore. Table 19 computes late fee payable and paid.
How Long Does It Take?
Stage
Typical time
Obligation check and data gathering
2–4 days
Monthly-filing cleanup (if pending returns exist)
1–3 weeks
Outward-supply reconciliation
3–7 days
ITC reconciliation (the long pole)
1–3 weeks
Tax-paid reconciliation and remaining tables
3–5 days
Review, submission and archiving
2–3 days
Clean books with monthly reconciliations already done: two to three weeks. Unreconciled ledgers in December: six to eight weeks — which is why the working should begin in October, not December.
Fees and Packages
Indicative professional fees for GSTR-9 preparation and filing (practice estimates, against current market):
Starter
Growth
Scale
Best for
Single GSTIN, turnover ₹2–5 cr
2–3 GSTINs or turnover ₹5–20 cr
Multi-state, turnover above ₹20 cr
Indicative fee
₹9,999
₹17,999
₹34,999
Inclusions
Obligation check, table-wise preparation, one reconciliation round, filing and ARN
Everything in Starter, plus full 2B-vs-books ITC reconciliation, variance report, HSN summary preparation
Everything in Growth, plus multi-GSTIN consolidation, prior-year transaction review, scrutiny-ready working papers
Fees track the state of the books — unreconciled ledgers cost more. The table assumes reasonably maintained accounts.
How ComplyKart Helps
Consulting: We confirm whether GSTR-9 applies to each of your GSTINs, compute the aggregate-turnover test correctly across states, and plan the reconciliation approach before the December rush.
Documentation: We gather and organise the twelve months of returns, 2B statements, registers and financials into a single filing file, and build the reconciliation workings table by table.
Filing: We prepare the return online or through the offline utility, walk you through every variance above the materiality threshold, and file with your DSC/EVC — with the ARN archived for your records.
Follow-up: Where the filing surfaces additional liability, we compute and process the DRC-03 payment; where it surfaces excess credit or refund positions, we advise on the next steps.
What we do not do: We do not sign off your books or issue any audit certification — GSTR-9 is self-prepared and self-submitted. We do not represent you in assessments or appeals arising from the filing unless separately engaged, and we do not fabricate figures to force a reconciliation that the books do not support.
What Happens After Filing
Within 30 days: The ARN is your proof of filing — keep it with the financial-year records. If turnover exceeds ₹5 crore, GSTR-9C preparation begins immediately: it can only be filed after GSTR-9 and shares the same 31 December deadline.
Within 6 months: Use the variance analysis from the filing to fix the underlying processes — vendor follow-ups for inconsistent suppliers, monthly 2B matching discipline, and credit-note hygiene. The next financial year's GSTR-9 is already accumulating; the cheapest time to keep it clean is now.
Recurring Compliance
GSTR-9 is annual — one filing per GSTIN per financial year, every 31 December. It sits alongside the monthly GSTR-1 and GSTR-3B cycle, the GSTR-9C reconciliation where applicable, and the income-tax and ROC annual filings. Businesses that run a monthly 2B reconciliation find the annual return takes a fraction of the effort.
GSTR-9 vs the Other Annual Forms
GSTR-9
GSTR-9A
GSTR-9B
GSTR-9C
Who files
Regular taxpayers, turnover > ₹2 cr
Composition taxpayers
E-commerce operators collecting TCS
Regular taxpayers, turnover > ₹5 cr
Nature
Annual return (19 tables)
Simplified annual return
Annual statement of TCS collected
Self-certified reconciliation statement
Deadline
31 December
31 December
31 December
31 December
Filed
Per GSTIN
Per GSTIN
Per GSTIN
Per GSTIN, after GSTR-9
Revision
Not permitted
Not permitted
Not permitted
Not permitted
Common Mistakes
Discovering in December that two months of GSTR-3B were never filed, and losing weeks to the cleanup.
Treating auto-populated tables as correct without checking them against the books.
Filing each GSTIN's turnover test separately instead of aggregating at PAN level.
Ignoring Table 8A mismatches — for FY 2024-25 these are IMS-driven and the department sees the same data.
Booking credit notes in the wrong financial year and creating unreconciled Table 4 differences.
Forgetting the HSN summary tables until the last day, then rushing the classification.
Filing GSTR-9 and assuming the job is done, while GSTR-9C (where applicable) shares the same deadline.
Not archiving the workings — and facing a scrutiny notice a year later with nothing to show.
Penalties
Section 47(2) of the CGST Act levies late fee for missing the 31 December deadline. The tiered structure applicable to annual returns is: ₹50 per day for turnover up to ₹5 crore (capped at 0.04% of turnover), ₹100 per day for turnover between ₹5 and ₹20 crore (capped at 0.04%), and ₹200 per day above ₹20 crore (capped at 0.5%). Interest at 18% per annum applies to any unpaid tax liability. Beyond money, a missing GSTR-9 is one of the standard triggers for a best-judgement assessment and for notices in the following year.
FAQ
Frequently asked questions
23 answers from our consultants.
You pay for our expert's time — document checking, filing, follow-ups — not the government. The government fee goes to the government; our fee is for the work we do so you don't have to figure it out yourself.
If your annual turnover crosses ₹40 lakh (₹20 lakh for services, lower in some states), yes — it's mandatory. But many businesses register voluntarily below the threshold to claim input tax credit and deal with larger clients who insist on GST invoices.
With clean documents, the GSTIN usually comes through in 3-5 working days. Delays happen when the officer raises a query — typically about the address proof or business activity. We respond to queries the same day so nothing stalls.
Every registered regular taxpayer whose aggregate turnover in the financial year exceeds ₹2 crore. Composition dealers, ISDs, TDS/TCS deductors, casual and non-resident taxable persons are outside its scope.
No. From FY 2024-25 onwards, Notification 15/2025-CT exempts taxpayers with aggregate turnover up to ₹2 crore. Filing remains optional — and some businesses file voluntarily for a clean compliance record.
Section 2(6) defines it as the aggregate of taxable supplies, exempt supplies, exports and inter-state supplies of a person with the same PAN, computed pan-India, excluding GST taxes. Exempt and export turnover counts toward the ₹2 crore test.
Yes. The ₹2 crore test aggregates across all GSTINs under the same PAN — ₹2.4 crore in your case. And you file GSTR-9 for each of the three GSTINs.
If aggregate turnover for the year exceeded ₹2 crore, yes — the return covers the period the registration was active. Cancellation ends future liability, not past filing obligations.
If the turnover test is met, yes. And note the specific rule: a person with multiple GSTINs and aggregate turnover above ₹2 crore must file even a nil annual return for GSTINs with no transactions.
Tiered by turnover: ₹50/day up to ₹5 crore, ₹100/day for ₹5–20 crore, ₹200/day above ₹20 crore, each subject to a percentage cap on turnover. Interest at 18% p.a. applies on unpaid tax.
No. The portal opens GSTR-9 only after all GSTR-1 and GSTR-3B returns for the financial year are filed. Clear the backlog first.
Notification 13/2025-CT: Table 8A now pulls from the Invoice Management System on document-date basis; a new Table 6A1 segregates cross-year ITC; GSTR-1A amendments auto-reflect in Tables 4 and 5; Table 8C computation logic was revised; and additional tax dues can be paid via DRC-03 using ITC.
Table 8A auto-populates input tax credit data — from FY 2024-25, driven by IMS on the invoice's document date rather than the reporting period. Mismatches between 8A and your books are visible to the department too, so they need investigation, not ignoring.
Additional liability is paid via Form DRC-03. From FY 2024-25, that payment can be made using input tax credit — previously it had to come from cash.
No. Composition taxpayers file GSTR-9A, the simplified annual return for the composition scheme.
The HSN-wise summaries of outward and inward supplies. For FY 2024-25, HSN cross-verification is enforced for turnovers above ₹5 crore — the classification has to be right, not approximate.
Small, documented differences with clear reasons are normal. Large unexplained gaps — especially in outward supplies or ITC — trigger scrutiny notices. Investigate variances above your materiality threshold before filing.
The GST portal enabled GSTR-9 and GSTR-9C filing for FY 2024-25 on 13 October 2025, with Prepare Online, Prepare Offline and (for 9C) Initiate Filing modes.
Yes. The GSTN offline tool lets you prepare the return in Excel/JSON, validate it locally, and upload it to the portal — useful for large datasets and multi-GSTIN consolidations.
The return can still be filed late with late fee, but there is no carrying forward — each financial year's GSTR-9 stands alone, and the late fee accrues per day until filed.
If your aggregate turnover exceeds ₹5 crore, yes — the self-certified reconciliation statement in Form GSTR-9C is filed alongside GSTR-9, after it, by the same 31 December deadline. Our detailed GSTR-9C guide covers the five-part reconciliation.
31 December 2025. The deadline under Section 44 is the 31st of December following the end of the financial year, unless extended by notification.
No. Unlike GSTR-1, the annual return has no revision mechanism. Once submitted, the figures are final — which is why the pre-filing review matters more here than anywhere else in GST.
What clients say about working with us
Real stories from businesses we've worked with.
Trademark Registration“
Our Trademark was applied in all the classes with a short span of time by Complykart Trademark Experts and I can say the level of expertise and commitment they carry is remarkable. It's an A+ from my side. We are now sticking to ComplyKart only.
Company Registration“
I found the professionalism of the staff at complykart.com, a pleasure to work with. As a foreigner to India, they took the time to explain the documentation and assisted in every question I raised. I was pleased that complykart.com made it easy for my Business.
Merger & Acquisition“
Trust, Commitment, Dedication and responsiveness are the best things with ComplyKart. Thanks for handling our Merger assignment with so much care. After my business disputes, complykart handles all things with own sense of understanding.
GST Practice Lead · Goods and Services Tax · 11+ years experience
Abhishek Sharma leads ComplyKart’s GST practice. He handles GST registrations, monthly filings, input tax credit reconciliation, refunds and department notices for businesses across India. He has guided hundreds of companies through GST audits and assessments.
Last reviewed: 16 November 2026
Get a free consultation
Talk to a ComplyKart professional about GSTR-9 Filing. The first consultation is free.