
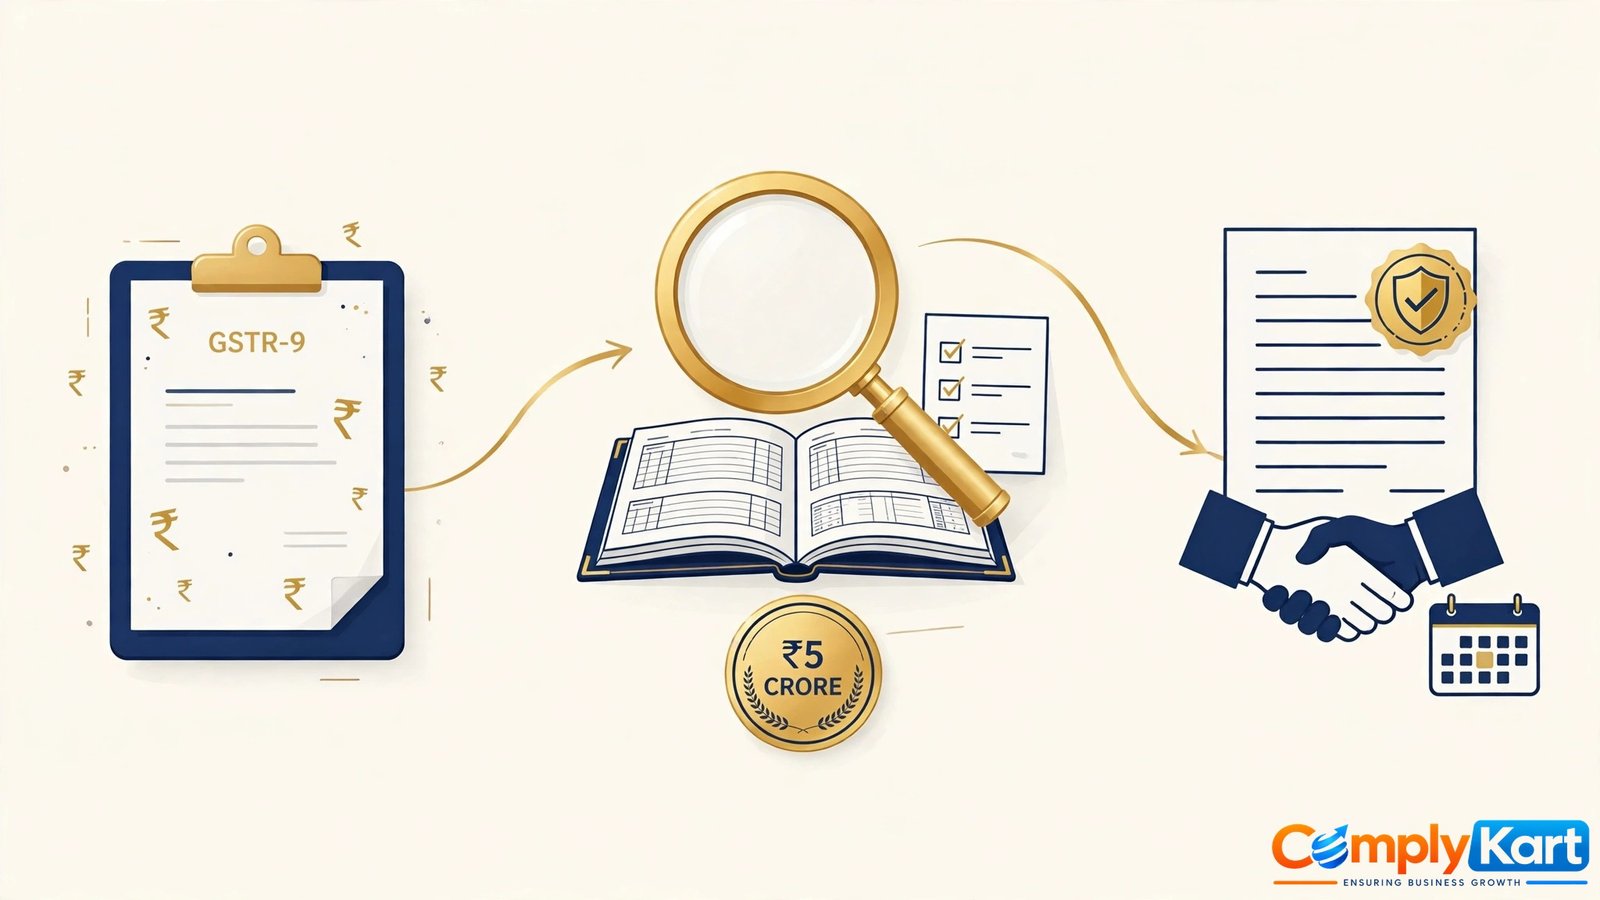
Above ₹5 crore of turnover, the GST annual return comes with a companion: GSTR-9C, a reconciliation statement that ties everything you declared in GSTR-9 back to your audited financial statements. It's due 31 December 2026, it can't be revised after filing, and most of the confusion around it comes from a rule that changed five years ago and never left people's heads.
The short answer: Taxpayers with aggregate turnover above ₹5 crore in FY 2025-26 must file GSTR-9C — a self-certified reconciliation between GSTR-9 and audited financials — along with GSTR-9 by 31 December 2026. Late filing costs ₹200 per day (₹100 CGST + ₹100 SGST), subject to a turnover-based cap.
How is the ₹5 crore GSTR-9C threshold actually measured?
Aggregate turnover above ₹5 crore in the financial year, tested at PAN level across all your GSTINs, all-India. Cross it under one PAN and every GSTIN under that PAN files its own GSTR-9C. Between ₹2 crore and ₹5 crore: GSTR-9 only. Up to ₹2 crore: the annual return itself is optional under the current exemption.
Think of it the way a landlord assesses a joint family: he doesn't ask what each member earns, he asks what the household totals. The department works the same way here. The mistake I see: businesses testing turnover GSTIN-by-GSTIN and concluding each registration is below the limit. The law tests the PAN. Add them up.
Do you need a CA to certify GSTR-9C?
Let's kill the most persistent myth first. Until FY 2019-20, GSTR-9C needed certification by a Chartered Accountant or Cost Accountant. The Finance Act, 2021 removed that requirement, and since FY 2020-21 the statement is self-certified by the taxpayer or authorised signatory.
Self-certified does not mean casual. You remain fully responsible for the accuracy of the reconciliation, and the figures you sign off flow straight into the department's analytics. The CA's signature is gone; the liability isn't. If your books and your returns have never been reconciled line by line, this is the year that gap becomes visible.
What does GSTR-9C actually reconcile?
Three bridges: turnover as per audited financials vs turnover declared in GSTR-9; tax paid as per financials vs tax paid as per GSTR-9; and ITC availed as per books vs ITC claimed in returns. Every difference needs a reason, disclosed in the statement. Unreconciled differences don't vanish — they become the opening questions of your next assessment.
Start with the known trouble spots: credit notes issued but not reflected, ITC reversals under Rules 42 and 43, turnover recognised differently in books vs returns, and HSN-wise reporting mismatches — which are now the most common trigger for system-generated queries. Our GSTR-9 reconciliation guide walks through the companion return's fields so you can see exactly what each bridge connects to.
Two traps to avoid
First: GSTR-9C can't be revised. Once filed, it's final — errors have to be intimated to the officer in writing, and tax shortfalls paid through DRC-03. Get the reconciliation right before you file, not after.
Second: don't file GSTR-9 early to "get it done." Filing the annual return advances your Section 16(4) ITC deadline to the filing date. Finish every legitimate ITC claim first — the October GSTR-3B is your last real vehicle — then file GSTR-9 and 9C together.
A practical note on who does this work: GSTR-9C is a joint exercise between your books team and your GST team, and it fails whenever one side does it alone. The books team knows the financials; the GST team knows the returns. The reconciliation lives in the gap between them. Put both in the room for the first working session, not the last.
The statement itself runs in parts: turnover reconciliation (financials to GSTR-9), tax-paid reconciliation, and ITC reconciliation, each with reasons for differences. You don't need to memorise the table numbers — your preparer does — but you do need to understand that every unexplained difference is a question you're choosing to leave for the assessment.
Which documents do you need ready for GSTR-9C?
The reconciliation goes faster when the papers are in one place before you start. Pull together: the audited trial balance and financial statements for FY 2025-26; month-wise GSTR-1, GSTR-3B and GSTR-2B summaries for the year; the ITC ledger with reversals under Rules 42 and 43 separately identified; the credit note and debit note register; and the HSN-wise outward summary. Whoever prepares the statement — your team or your professional — will ask for these, and chasing them in December is what turns a two-week job into a six-week one.
The runway plan
GSTN enabled GSTR-9/9C filing for FY 2025-26 on 8 October 2026 (advisory dated 13 October 2026), and the 31 December deadline is ten weeks away. One access note: the GSTR-9/9C tile only appears once all your GSTR-1 and GSTR-3B for the year are filed. Some taxpayers are hitting a glitch where the portal still asks for pending returns after everything is filed — if that happens, raise a ticket on the GSTN helpdesk self-service portal instead of re-filing.
Six to eight weeks is the honest runway: chase vendors for missing invoices now, fix GSTR-1 amendments, compute reversals, and reconcile books to returns without December compression. File a correct return in the third week of December and spend the last week on nothing. If the reconciliation is eating your team's bandwidth, our GST returns team files GSTR-9 and 9C for businesses every December.
GSTR-9C: quick answers
What happens if I miss the 31 December GSTR-9C deadline?
Late filing costs ₹200 per day (₹100 CGST + ₹100 SGST), subject to a turnover-based cap — and since GSTR-9C rides with GSTR-9, the same delay hits both filings. Worse, an unreconciled year doesn't disappear: the differences you never explained become the opening questions of your next assessment. Run the numbers on what waiting actually costs you.
Below ₹5 crore turnover — do I file GSTR-9C?
No. Between ₹2 crore and ₹5 crore you file GSTR-9 only; up to ₹2 crore the annual return itself is optional under the current exemption. But test at PAN level across all GSTINs — businesses that test registration-by-registration and conclude each is below the limit are the ones that get caught. New to the system? Start with GST registration done right.
Can GSTR-9C be revised after filing?
No. Once filed, it's final — errors have to be intimated to the officer in writing, and tax shortfalls paid through DRC-03. This is why the reconciliation must be right before you file, not after. Six to eight weeks of runway is honest; December compression is how errors happen.
Does GSTR-9C affect my ITC claims?
Indirectly but critically: don't file GSTR-9 early to "get it done," because filing advances your Section 16(4) ITC deadline to the filing date. Finish every legitimate ITC claim first — our ITC deadline guide walks through the 30 November cut-off — then file GSTR-9 and 9C together. Running the numbers on the year's total compliance? Our compliance fee calculator estimates it in under a minute.
Ten weeks, three bridges, one unrevisable filing. Start now — our team runs GSTR-9 and 9C filings every December, and the filings that go smoothly are always the ones that started in October.

Comments
No comments yet — ask the first question below.
Join the discussion
Questions go straight to our expert desk. Comments appear after a quick review — no spam, no noise.