
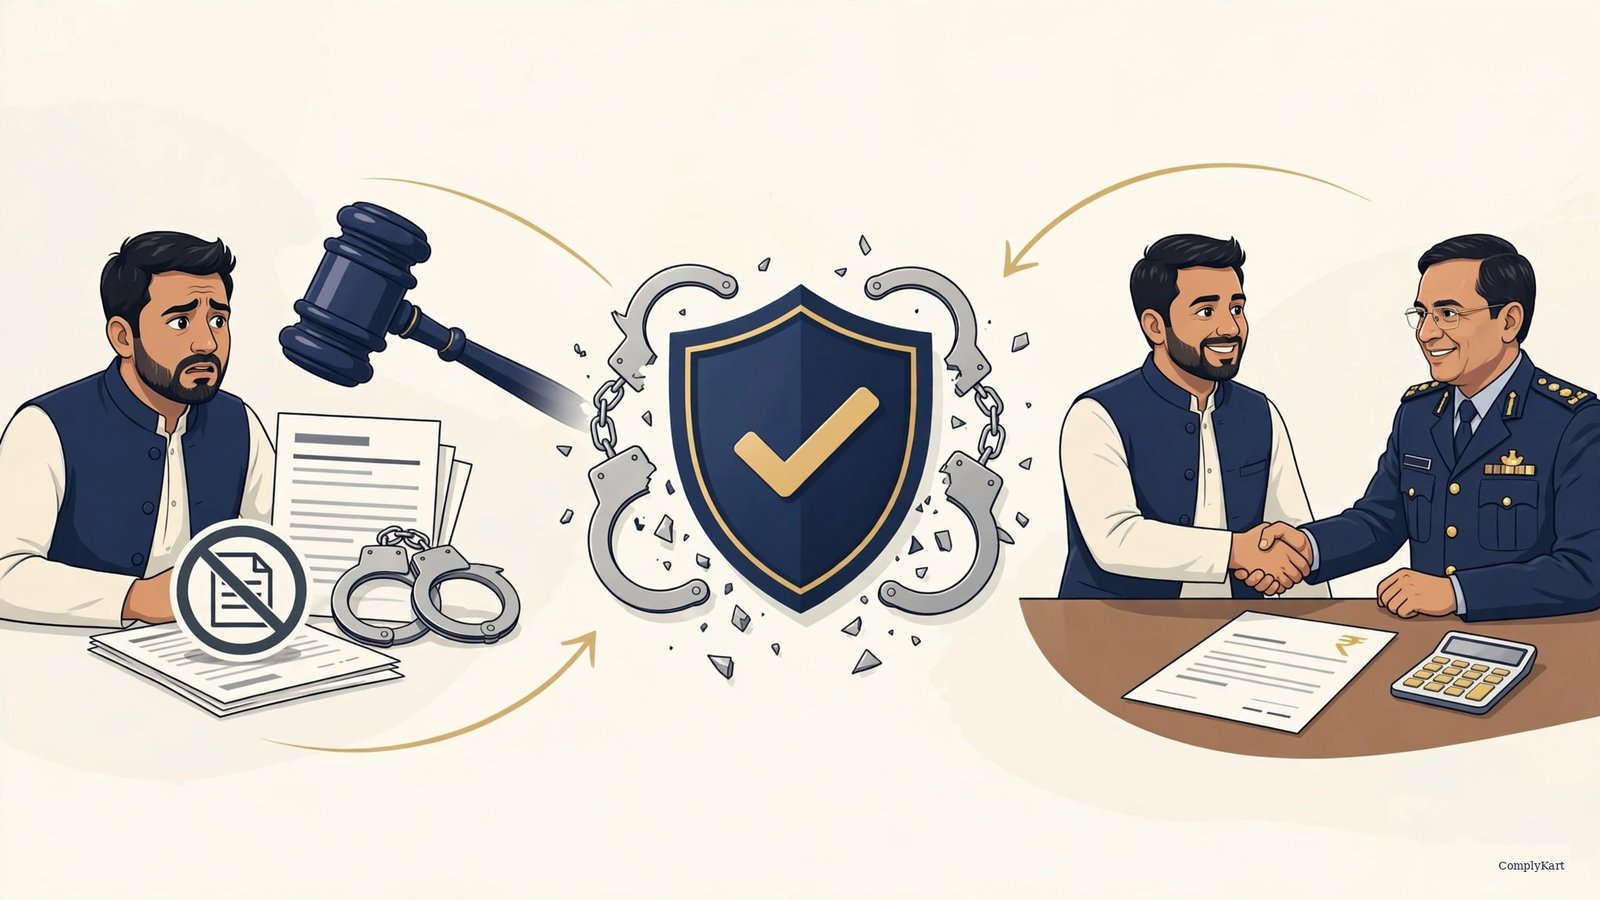
For nine years, Section 69 of the CGST Act sat over every GST-registered business like a storm cloud that rarely rained. The power existed. Officers could arrest for tax evasion above specified thresholds. In practice, arrests were rare — but the threat of them shaped behaviour in ways that had very little to do with compliance and everything to do with fear.
On 8 October 2026, the GST Council, meeting in New Delhi under Finance Minister Nirmala Sitharaman, recommended taking that power away entirely.
Read that carefully. Recommended. Not removed. There is a difference, and it is the most important sentence in this post. I will come back to it.
What the 57th Council actually decided
The headline is decriminalisation, and it comes as a package. First, the arrest power under Section 69 goes — enforcement shifts to civil measures: tax recovery, interest, and proportionate penalties. Second, criminal prosecution would only trigger where alleged evasion exceeds ₹5 crore, up from ₹1 crore today, and would proceed by complaint before a competent court. Third, nine statutory offences are proposed for complete decriminalisation, while 24 others would see their maximum sentences reduced and mandatory minimum prison terms removed.
The monetary thresholds around penalties move too. The general penalty ceiling under Section 125 drops from ₹25,000 to ₹10,000. And the Council has proposed a ₹10,000 minimum threshold for specified show-cause notices, aggregated across CGST, SGST and IGST — officers would have to cross that line before issuing one. Business Today reported that this threshold is expected to apply retroactively to pending cases, which would close roughly 1.23 lakh pending show-cause notices and nearly 11,800 first appeals. That figure is a reported estimate, not a notified fact — treat it as the direction of travel, not a done deal.
There is an analogy that explains the philosophy better than any press release. Think of a landlord dealing with a tenant who pays late. One approach is to threaten eviction every month — it gets attention, but it also poisons the relationship and produces grudging, minimal payments. The other approach is a proper dues-collection process: reminders, interest on late payment, and legal recovery when it matters. The rent still gets collected. The fear goes away. The Council has just voted to move GST enforcement from the first landlord to the second.
What changes for honest businesses
Most of this package is aimed at the middle of the market — businesses that file, pay, and occasionally get things wrong.
Honest mistakes stop looking like crimes. A classification error or a documentation slip that once carried the theoretical shadow of prosecution now faces civil consequences: pay the tax, pay the interest, pay a proportionate penalty. That is how a modern tax system should treat errors. Criminal law was always the wrong tool for a mismatched invoice.
The notice burden should shrink. The ₹10,000 show-cause threshold means officers stop spending their time — and yours — on low-value disputes. Fewer notices, fewer replies to draft, fewer small demands clogging the adjudication pipeline. If you have a pending notice below that line, keep it on your watchlist; if the retrospective application is notified as reported, it could simply disappear.
Refunds get faster. Refund claims are to be acknowledged within 10 days instead of 15, with automated provisional refunds of 90% of eligible claims. Refund eligibility also widens for accumulated credit on specified input services and capital goods. For exporters and inverted-duty businesses, this is the change that touches cash flow — and cash flow is what keeps a business alive.
Input tax credit gets friendlier at the edges. Employers would be able to claim ITC on employee insurance premiums, and the blocked-credit provisions get relaxed. And goods in transit: authorised, intelligence-based interception replaces random checks. Your truck gets stopped because the data flagged something, not because it happened to be on that road.
The one thing I need you to get right
None of this is law yet.
Council recommendations take effect only through notifications, circulars, or amendments to the Act — and the arrest-power removal needs Parliament to amend the CGST Act itself. The Finance Ministry said so in plain words: the relevant circulars, notifications and law amendments "alone shall have the force of law." Most of the process reforms are reported to take effect from 1 April 2027. As of today, the old provisions technically stand.
This is where I see businesses make the expensive mistake. A recommendation is a promise of a direction. It is not a shield you can hold up in front of an officer today. If you have an ongoing dispute or a notice in hand, you fight it under the law as it stands — while tracking the notifications that will carry these changes into force.
There is a useful way to think about it. The Council is like a company's board approving a new policy. The approval is real and the direction is set. But until the circular goes out and the system is updated, the old process runs the floor. Check the CBIC notifications before you change any compliance behaviour.
What to do this quarter
First, do not stop paying attention to notices. The law has not changed, and the department has not stopped working. Every notice still needs a reply on time.
Second, if you are sitting on pending low-value show-cause notices or first appeals, do not withdraw anything yet — but do not spend heavily fighting them either. A short, holding reply that preserves your position is the sensible posture while the threshold notification is awaited.
Third, exporters and businesses with blocked refunds should start preparing cleaner refund documentation now. When 90% provisional refunds arrive, the businesses with reconciled books will get their money first. The ones with mismatched GSTR-1 and GSTR-3B will not.
Fourth, review your classification and valuation positions. The prosecution threshold moving to ₹5 crore does not mean disputes below that vanish — it means they stay civil. Civil disputes still cost money. Getting the position right now is cheaper than defending it later.
The Council also approved, in principle, an optional Annual Return Quarterly Payment scheme for eligible small B2C taxpayers, and confirmed there are no GST rate changes — rates will now be reviewed just once a year at a dedicated meeting. Neither affects your filing this month, but both tell you where the system is heading: fewer touchpoints, less confrontation, more automation.
Nine years in, GST is growing out of its enforcement-first adolescence. The tax still gets collected. The handcuffs, if Parliament agrees, go back in the drawer. That is a better deal for everyone — including the honest officers who would rather recover dues than make arrests.

Comments
No comments yet — ask the first question below.
Join the discussion
Questions go straight to our expert desk. Comments appear after a quick review — no spam, no noise.