
IN BRIEF
Notification No. 02/2026–Central Tax (Rate) is the GST rate amendment that, from 1 November 2026, places retreaded tractor tyres in the 5% GST schedule and confirms that pre-packaged and labelled animal, vegetable and organic fertilisers, expressly including seaweed-extract bio-stimulants registered under Schedule VI to the Fertiliser Control Order, 1985, sit in the same 5% schedule, while other retreaded tyres stay at 18%.
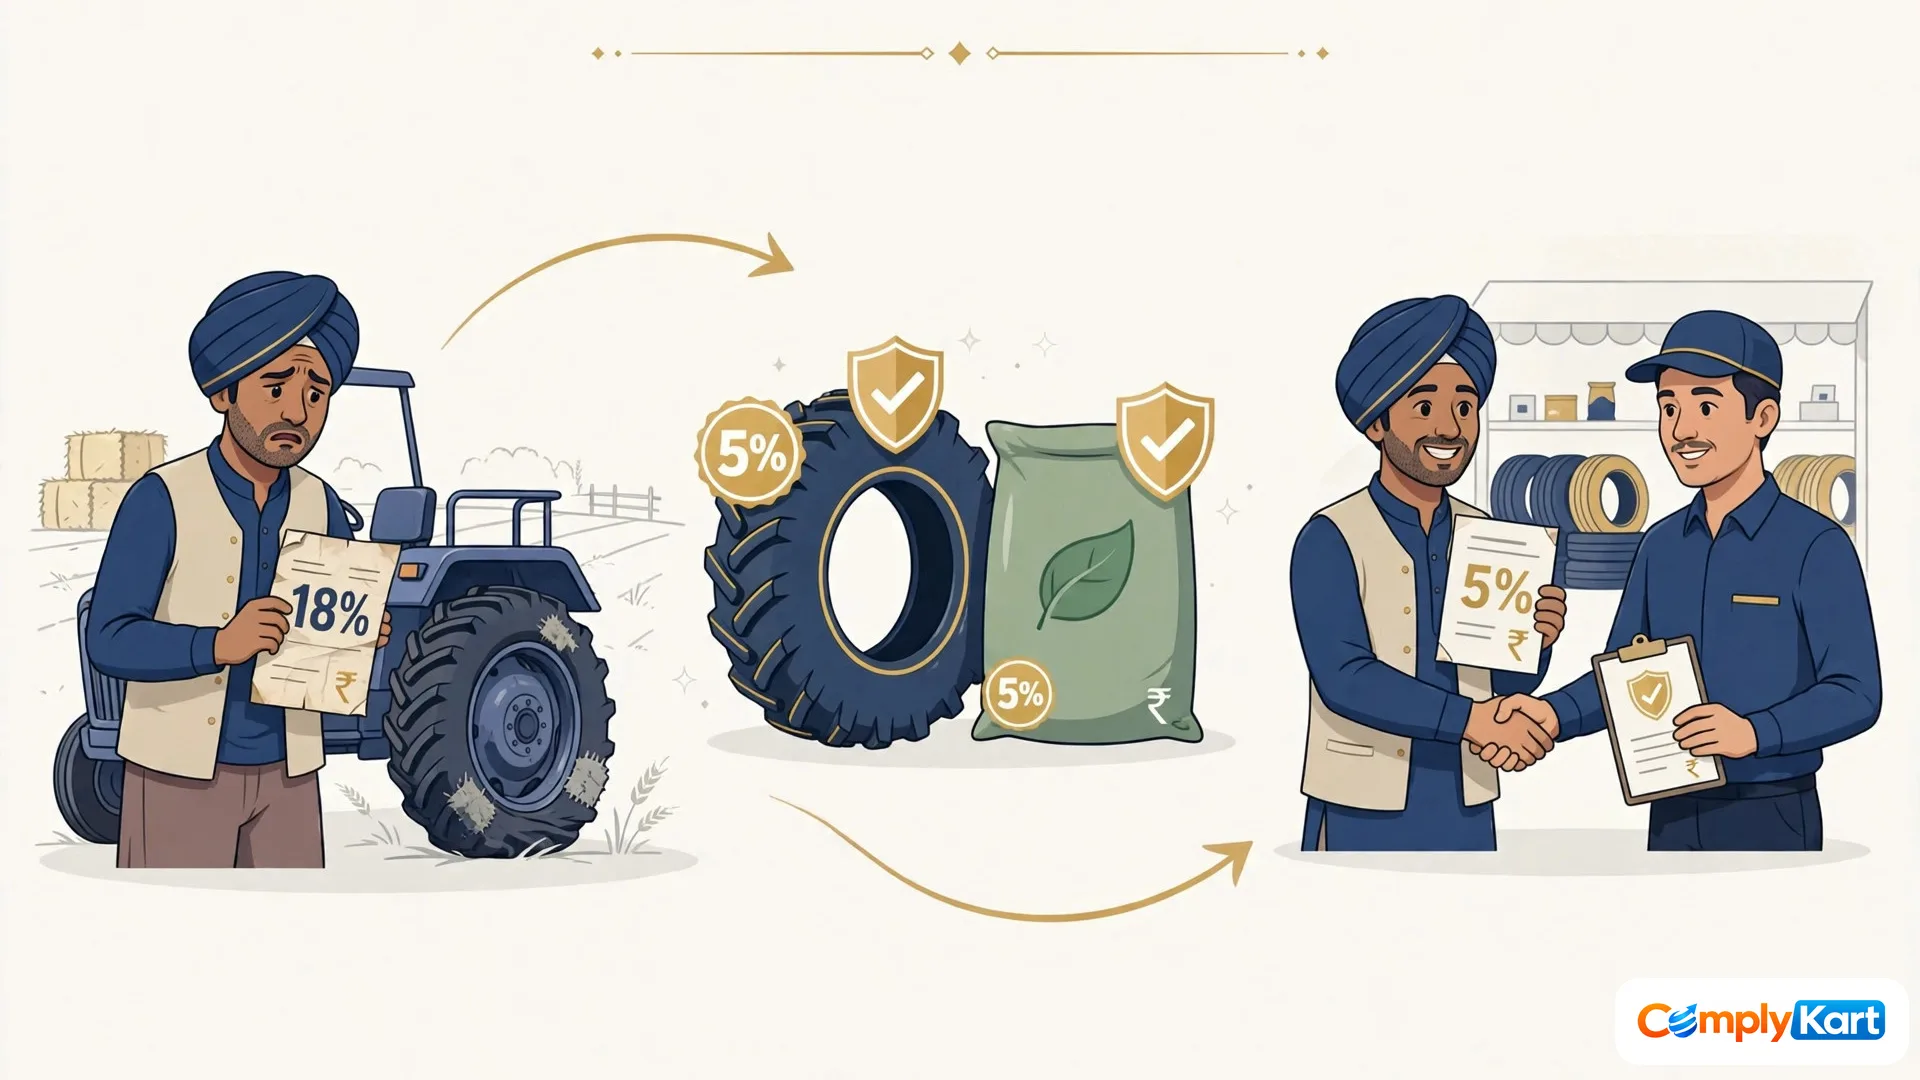
If you run a tractor, tomorrow makes its tyres cheaper to retread. From 1 November 2026, retreaded tractor tyres move from 18% GST to 5%. In the same notification, the government writes seaweed-extract bio-stimulants into the fertiliser entry in plain words. Two changes, one notification, and they are not the same kind of change at all. One is a real rate cut. The other is a clarification that ends an argument. Mixing them up is the easiest way to get your next invoice wrong.
The short answer: from 1 November 2026, retreaded tractor tyres attract 5% GST (2.5% CGST plus 2.5% SGST, or 5% IGST between states), down from 18%. Pre-packaged and labelled animal, vegetable and organic fertilisers stay at 5%, and seaweed-extract bio-stimulants registered under Schedule VI to the Fertiliser Control Order, 1985 are now expressly included. Every other retreaded or used tyre stays at 18%.
One notification, two very different changes
Notification No. 02/2026–Central Tax (Rate), dated 27 October 2026 (G.S.R. 921(E)), amends the GST rate notification No. 9/2025–Central Tax (Rate). It was issued on the GST Council's recommendations, under section 9(1) and section 15(5) of the CGST Act, and it takes effect on 1 November 2026. Matching IGST and UTGST notifications were issued alongside it. Here is the whole notification in one table.
| What changed | Where in the notification | Effect from 1 November 2026 |
|---|---|---|
| Fertiliser entry rewritten | Schedule I (2.5% CGST), Serial No. 237 | All pre-packaged and labelled animal, vegetable and organic fertilisers sit in the 5% schedule; seaweed bio-stimulants expressly included |
| New tyre entry created | Schedule I (2.5% CGST), new Serial No. 272A, heading 4012 | "Retreaded tractor tyres" move into the 5% schedule |
| Old tyre entry narrowed | Schedule II (9% CGST), Serial No. 138 | Retreaded tractor tyres are carved out; everything else in that entry stays at 18% |
Read the table and the pattern is clear. The fertiliser change rewrites words inside an entry that was already in the 5% schedule. The tyre change physically moves goods from one schedule to another. That is why one saves you money and the other mostly saves you arguments.
The tyre change: 18% down to 5%
Until 31 October 2026, a retreaded tractor tyre sat inside the Schedule II entry for retreaded or used pneumatic tyres of rubber. That entry carries 9% CGST, which means 18% in total inside a state (9% plus 9%) and 18% IGST between states. From 1 November, the same entry reads "retreaded or used pneumatic tyres of rubber (other than retreaded tractor tyres)". The words in brackets do all the work. Tractor retreads leave the 18% entry, and the new Serial No. 272A catches them in the 2.5% schedule. Two halves of 2.5% make 5%.
Retreading deserves its own entry, and the shoe analogy explains why. A retreaded tyre is not a used tyre. It is a worn casing given a new tread, the way a cobbler resoles a good shoe instead of throwing it away. The casing is the same, the working surface is new, and the job costs a fraction of a new tyre. Farmers retread because a tractor tyre is too expensive to replace every time the tread wears down. Until now the tax code lumped that resoled tyre in with genuinely used tyres. From tomorrow it has its own line, at less than a third of the old rate.
Here is what that means on a real bill. Take a round-number illustration, not a real deal: a retreader bills four retreaded tractor tyres at a taxable value of ₹40,000. At the old 18%, the GST was ₹7,200 and the farmer paid ₹47,200. At the new 5%, the GST is ₹2,000 and the bill is ₹42,000. The saving is ₹5,200 on one set of tyres. That is real money in a farming household, and it arrives right before the rabi season puts tractors to their hardest work.
One honest caution. A rate cut is not an automatic price cut. The saving reaches the farmer only if the retreader reprices the bill at 5%. If your dealer hands you a November invoice still showing 18% on retreaded tractor tyres, ask why. The notification leaves no room for the old rate on these goods after 1 November.
The fertiliser change: same rate, clearer words
Do not let anyone sell you the fertiliser change as a price cut. It is not one. Serial No. 237 already sat in the 2.5% schedule, so pre-packaged and labelled fertilisers were already at 5% in total. What the notification does is rewrite the entry to read "all goods i.e. animal or vegetable fertilisers or organic fertilisers pre-packaged and labelled", and then add an explanation that settles one specific doubt: sea-weed extract based bio-stimulants, as registered under Schedule VI to the Fertiliser (Inorganic, Organic or Mixed) (Control) Order, 1985, are included in this entry.
Two conditions carry the whole entry, and both must hold. First, the fertiliser must be pre-packaged and labelled. Loose fertiliser sold out of an open sack does not take this entry. Second, for a seaweed bio-stimulant, registration under Schedule VI to the Fertiliser Control Order is part of the definition. A bio-stimulant product that is not so registered falls outside this express inclusion, and its classification needs care rather than assumption. If you sell bio-stimulants, check your registration paper before you change a single rate in your billing software. The entry rewards the registered product and says nothing kind about the unregistered one.
Which rate applies to your goods?
| Goods | GST from 1 November 2026 | Why |
|---|---|---|
| Retreaded tractor tyres (heading 4012) | 5% | New Serial No. 272A in the 2.5% schedule |
| Pre-packaged and labelled animal, vegetable or organic fertilisers | 5% | Rewritten Serial No. 237 in the 2.5% schedule |
| Seaweed-extract bio-stimulants, Schedule VI registered | 5% | Expressly included in Serial No. 237 by explanation |
| Other retreaded or used pneumatic tyres (car, truck, etc.) | 18% | Still in Serial No. 138 of the 9% schedule |
| Solid or cushion tyres, tyre treads, tyre flaps | 18% | Still in Serial No. 138 of the 9% schedule |
Notice what the notification does not touch. New tractor tyres are a different entry and nothing here changes them. Only the retreaded tractor tyre moves. If a dealer quotes you 5% on a new tyre or on a retreaded truck tyre by pointing at this notification, the notification does not support that quote.
October invoice, November delivery: which rate wins?
The awkward deals are the ones straddling the change. A farmer orders retreads in October, the retreader delivers in November, and payment lands somewhere in between. Section 14 of the CGST Act answers this, and its rule is simpler than it looks: count how many of the three events — supply, invoice, payment — fall before the change and how many after. Two or more before means the old rate. Two or more after means the new rate.
| Your situation | Events before 1 November | Rate that applies |
|---|---|---|
| Delivered and invoiced in October, paid in November | Supply + invoice | Old 18% — the invoice date governs |
| Invoiced in October, delivered and paid in November | Invoice only | New 5% — the payment date governs |
| Advance paid in October, delivered and invoiced in November | Payment only | New 5% — two events fall after the change |
So if you took an advance from a farmer in October for retreads you will deliver next week, the new 5% rate applies to that supply, even though the money arrived under the old regime. And if you delivered and invoiced in October and are simply waiting for payment, the old 18% stands. Do not reissue October invoices at 5% to look generous. The tax follows the events, not the goodwill.
A checklist for retreaders, dealers and fertiliser sellers
If you bill any of these goods, do these five things before your first November invoice. First, split your rate master: one line for retreaded tractor tyres at 5%, a separate line for all other retreaded and used tyres at 18%. One shared "retreaded tyres" line is now a guaranteed error. Second, check the heading on your retreaded tractor tyre line reads 4012. Third, if you sell bio-stimulants, file the Schedule VI registration alongside the rate entry so anyone auditing the bill can see why 5% was charged. Fourth, reprice your printed price lists and your billing software together — a price list at 5% with software still charging 18% will produce angry customers and wrong returns in equal measure. Fifth, warn your regular farmer customers that the saving is on the invoice, not in cash back, so nobody arrives expecting a refund on an October bill.
Five mistakes to avoid
- Charging 5% on every retreaded tyre. The cut covers tractor tyres only. A retreaded truck or car tyre stays at 18%.
- Calling the fertiliser change a rate cut. The rate was already 5%. What changed is the wording, and the express inclusion of registered seaweed bio-stimulants.
- Selling loose fertiliser at the packaged rate. The entry says pre-packaged and labelled. Loose sales do not qualify.
- Reissuing October invoices at 5%. Section 14 fixes the rate by the supply, invoice and payment dates. A delivered-and-invoiced October deal stays at 18%.
- Leaving one "retreaded tyres" line in your software. Tractor and non-tractor retreads now live in different schedules. One line cannot hold two rates.
What has not changed
Three things stay exactly as they were. New tyres of every kind are untouched by this notification. The 18% rate on other retreaded tyres, solid tyres, treads and flaps is untouched. And the fertiliser rate itself is untouched — only its description is wider and clearer. The government has done something narrow and useful here: it has given one farming input a genuine cut and one farming input a clean definition, in the same stroke. Check your invoice line by line against the table above, and tomorrow's first bill under the new rates will be right.
If you need to get registered before you start billing at the new rates, our GST registration guide walks through the process, and GST return filing covers the GSTR-3B mechanics for reporting the changed rates. The GST rate list for 2026 puts this change in context with the September rate overhaul, and our scrap GST guide and 1 November discount and refund changes guide cover the other notifications landing the same day. The compliance fee calculator can help you size the cost of staying current.
Frequently asked questions
What is the GST rate on retreaded tractor tyres from 1 November 2026? 5% in total — 2.5% CGST plus 2.5% SGST within a state, or 5% IGST between states — under new Serial No. 272A of Notification No. 02/2026–Central Tax (Rate). Before 1 November 2026 the rate was 18%.
Do seaweed bio-stimulants attract 5% GST? Yes, if they are seaweed-extract based bio-stimulants registered under Schedule VI to the Fertiliser Control Order, 1985, and sold pre-packaged and labelled. Both conditions matter; the notification's explanation names the registration expressly.
Has the GST rate on fertilisers changed? No. Pre-packaged and labelled animal, vegetable and organic fertilisers were already in the 5% schedule. The notification rewrites the entry and expressly includes registered seaweed bio-stimulants; it does not cut the rate.
Does the 5% rate apply to retreaded truck tyres? No. Only retreaded tractor tyres moved to the 5% schedule. Other retreaded or used pneumatic tyres, solid or cushion tyres, tyre treads and tyre flaps remain at 18% under Serial No. 138.
I paid an advance in October for retreads delivered in November. Which rate applies? The new 5% rate. Under section 14 of the CGST Act, supply and invoice fall after the change while only payment falls before it, so two of the three events are after 1 November 2026 and the new rate governs.

Comments
No comments yet — ask the first question below.
Join the discussion
Questions go straight to our expert desk. Comments appear after a quick review — no spam, no noise.